From the editor
tkal is a daily synthesis of the credit, demand, and capex cascades I've been running for myself. Receipts published weekly: every dated call gets graded, blindly, against what actually happened. The premise is that most market writing is unfalsifiable by design — vague enough to be re-narrated after the fact. This is the opposite. The conviction level is on the call. The horizon is on the call. The falsifier — the thing that would prove it wrong — is on the call. If the call misses, it's in the scorecard. If it hits, also in the scorecard. The newsletter is what the model saw this week; the scorecard is whether the model has been right. Not investment advice. Positions may exist in the names discussed.
The Read
Seven of seven nights collected, and the clearest finding was an absence: data-centre component revenue rose 182% while prices per bit more than doubled and no bit count exists.
the money doubled, the bits went quiet
01 · Signal
value is accelerating, volume is unmeasured
Dell'Oro reported data-centre IT semiconductor and component revenue up 182% in the second quarter, then warned in the same release that memory and storage prices per bit had more than doubled and that revenue growth is not a bit-shipment measure. Korean export prints and Taiwan distributor records carry the same denominator problem. Across 43 merged evidence items in the first complete collection week of this series, not one carries a bit count.
Two markets, one denominator, and the denominator is the number nobody publishes.
02 · Signal
the consumer lane cracked in four geographies
Omdia put US PC shipments up 1.0% in the second quarter, named channel buy-ahead as the cause, and forecast an 18.4% payback already under way against a 10.7% full-year decline. Counterpoint has Brazil smartphone shipments down 11% in the first half, a third independent geography breaching the same price elasticity. Apple added a flat $100 to every iPhone and raised China storage tiers by as much as RMB 3,500, lifting older models rather than cutting them.
A 1.0% quarter that Omdia itself calls borrowed, against an 18.4% payback already running.
03 · Signal
the ai lane passed its only real test
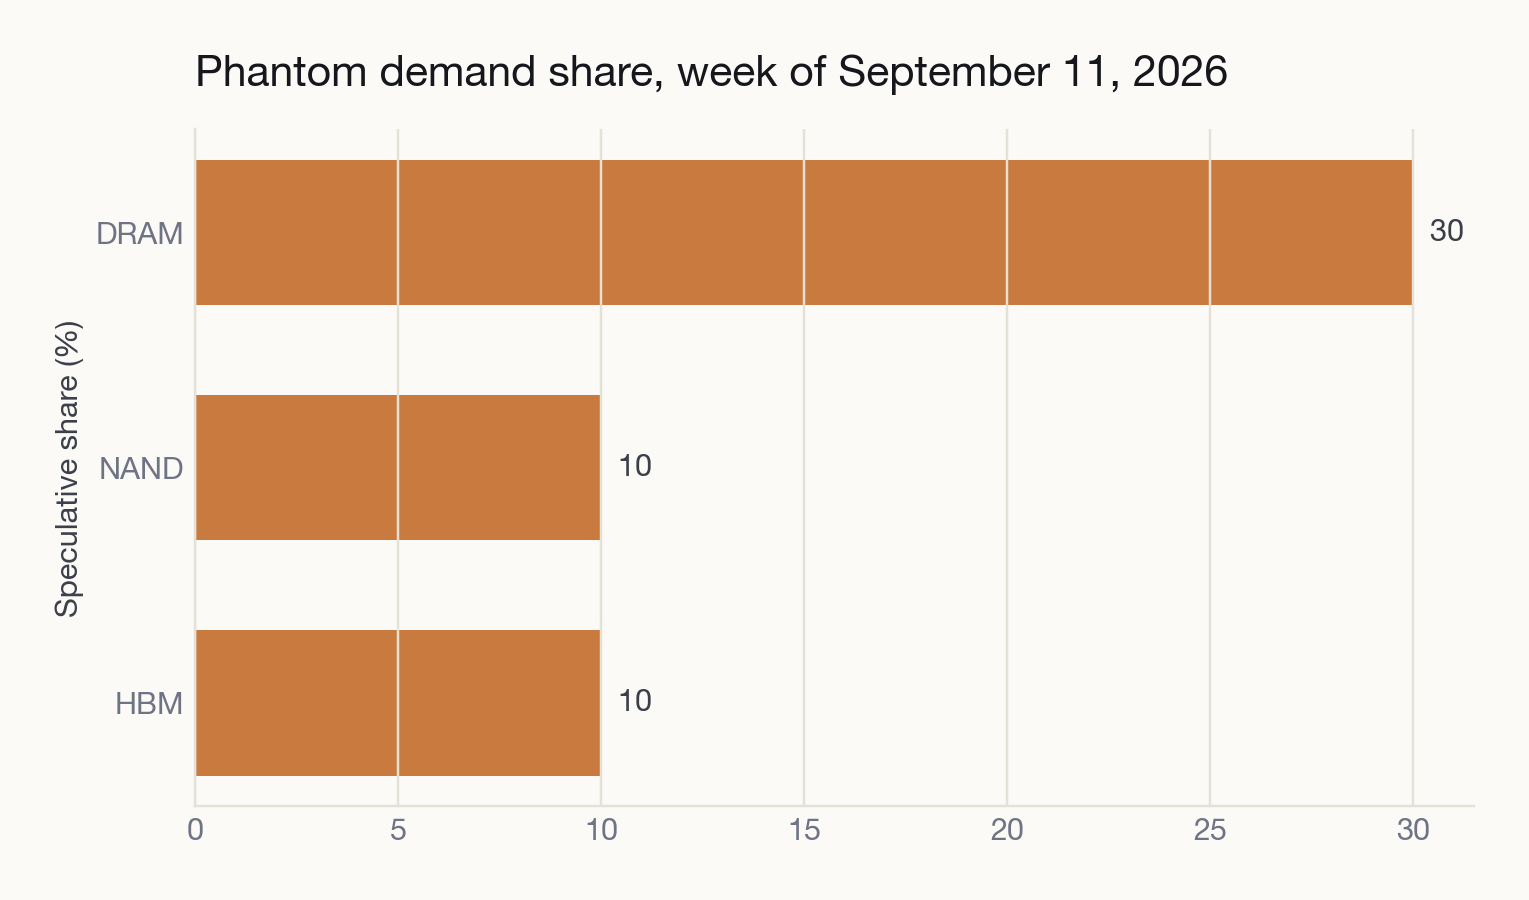
HPE disclosed record purchase commitments above $30B on multi-year agreements that assure supply rather than price, and volunteered that a backlog review found no double booking. That is the only direct test anyone ran on the phantom-demand hypothesis this week, and it came back negative. Oracle energised 850 MW with $664B of remaining performance obligations. The phantom track agrees: 10% speculative content on HBM against 30% on DRAM.
One audited backlog outranks four quarters of revenue growth nobody can convert into bits.
The Call · Bits Or Nothing By Oct 31
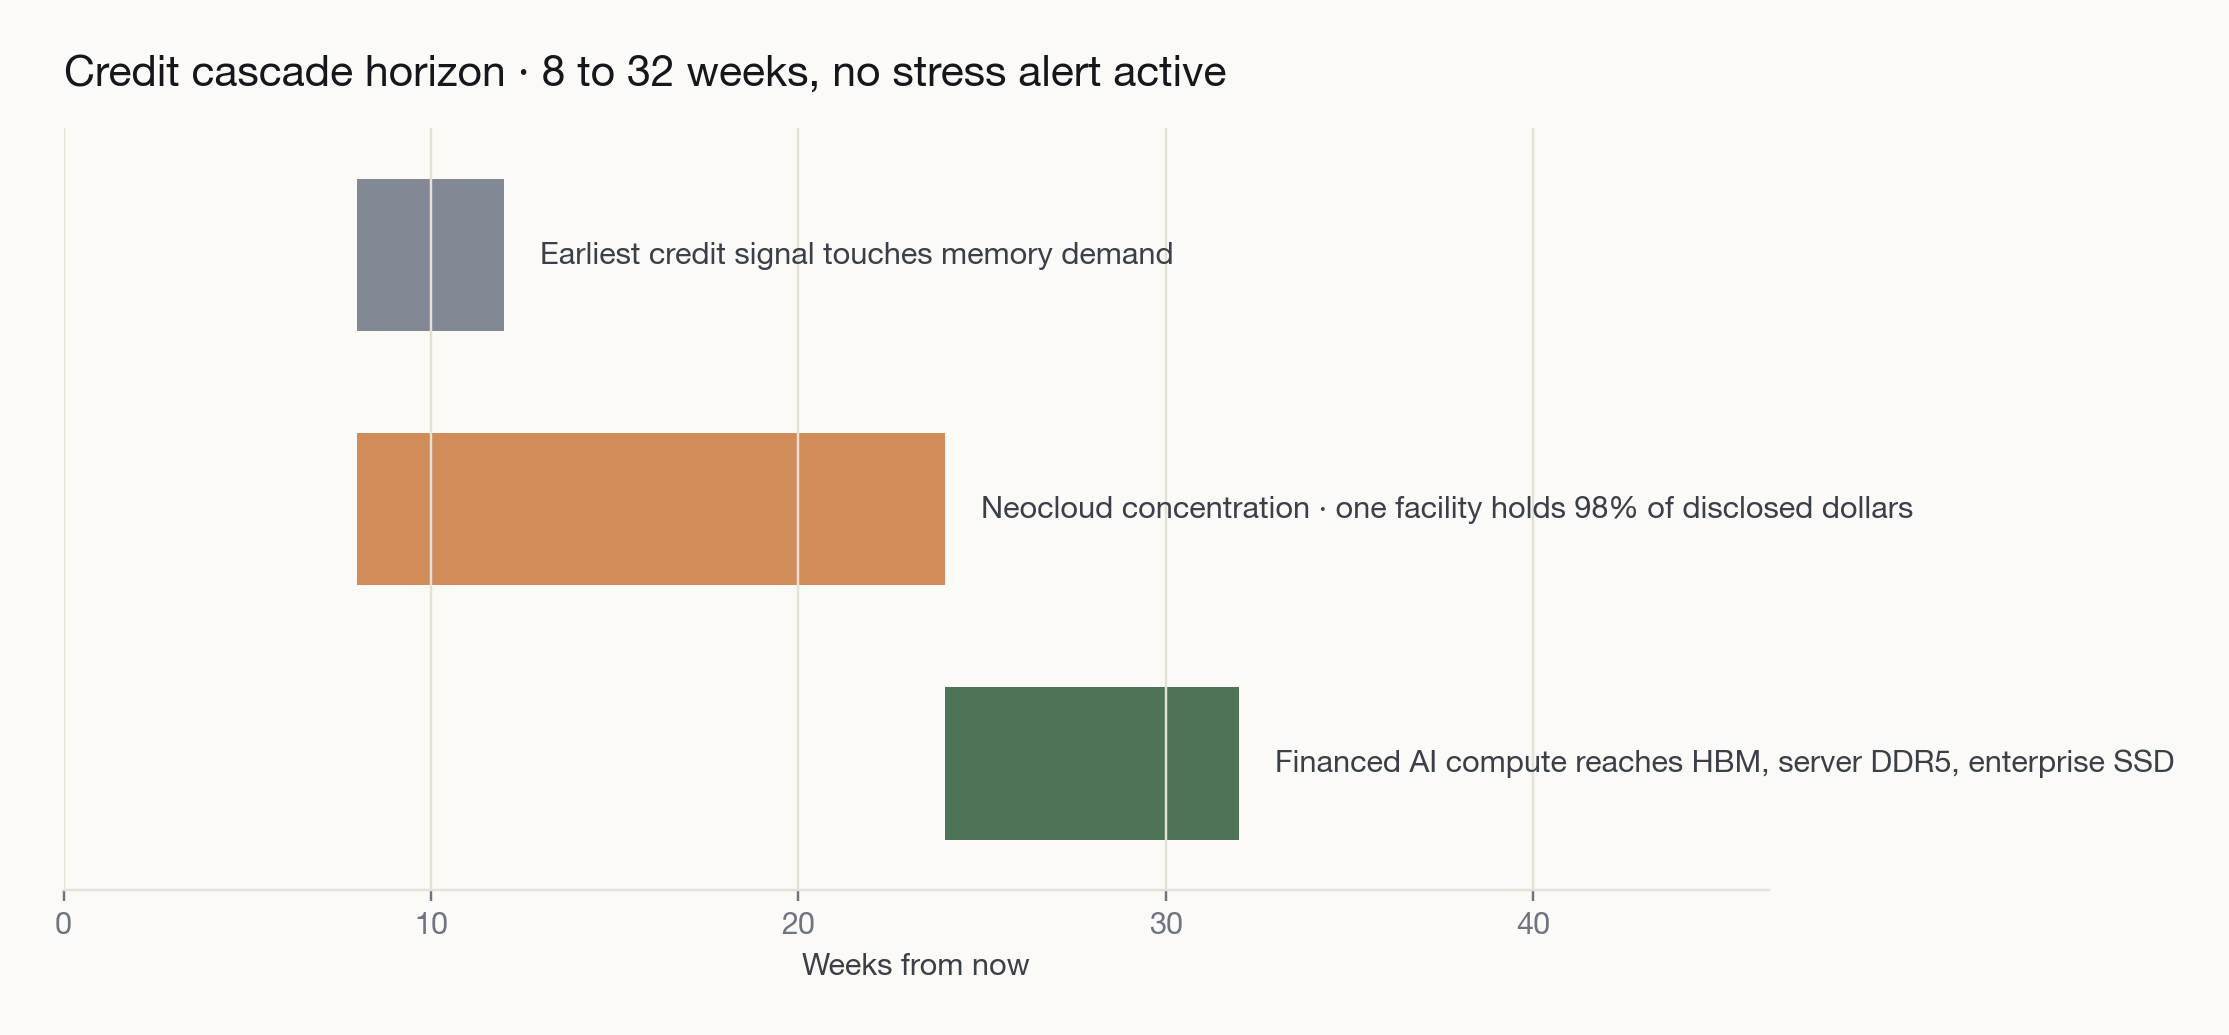
Credit conditions are stable, no stress alert is active, and the lead-lag horizon runs 8 to 32 weeks, so the binding constraint this quarter is measurement rather than financing. The Q3 supplier inventory print due by is the nearest hard read on whether that value growth carried any bits.
Before the Q3 supplier inventory print due . The durable NAND lane is enterprise and OEM contract, not the channel tier. Averaging the two into one read would be wrong at both ends. Enterprise TLC contract ASPs are rising while 512Gb channel wafer prices posted the steepest weekly decline in the series. Apple is reported to have signed a long-term agreement with Kioxia, possibly without a price ceiling. The licensed wafer price series has been dark 11 days, so the reversal trigger on the lean posture cannot fire. Watch Kioxia, SanDisk, Micron and Phison.
§
Already shipping, not a forward event. Treat Chinese leading-generation mobile DRAM as addressable-market erosion rather than a cycle position. The China growth increment is no longer reachable by tracked vendors. CXMT reached mass production of LPDDR6 in the Xiaomi 18 Fold, a non-Huawei flagship, which breaks the assumption that domestic Chinese DRAM stays a generation behind. LPDRAM is the weakest demand row in the file and the outlook layer emits no LPDRAM row at all. Watch the mobile mix at Samsung, SK hynix and Micron.
§
Two consecutive weeks with no capital-spending figure disclosed. The hyperscaler capex grid is carried, not confirmed. Read the buildout through megawatts and contracts, not through the aggregate dollar figure. The $685B aggregate is 14 days old and falls from $762.5B only because Oracle is restated at its guided run-rate. This was a complete 7-of-7 collection week, so the absence is real rather than a collection artefact. DeepSeek V4.1 Flash is the live counter-signal, stated to cut HBM requirement to a quarter for comparable work. Watch HBM commentary from SK hynix, Micron and Samsung.