
The setup
ASML walked into the print with a stock that had already re-rated hard into the number — shares had run toward the high-$1,700s / ~€1,650 on AI-capex optimism, and the options market was pricing a mid-single-digit move. The bar wasn't the headline sales line, which ASML guides tightly and rarely misses; it was forward demand signal. After a 2025 defined by China-export overhangs and a soft memory patch, the question analysts actually wanted answered was whether hyperscaler and foundry capex is translating into durable litho orders — or whether 2026 was a pull-forward that fades into 2027.
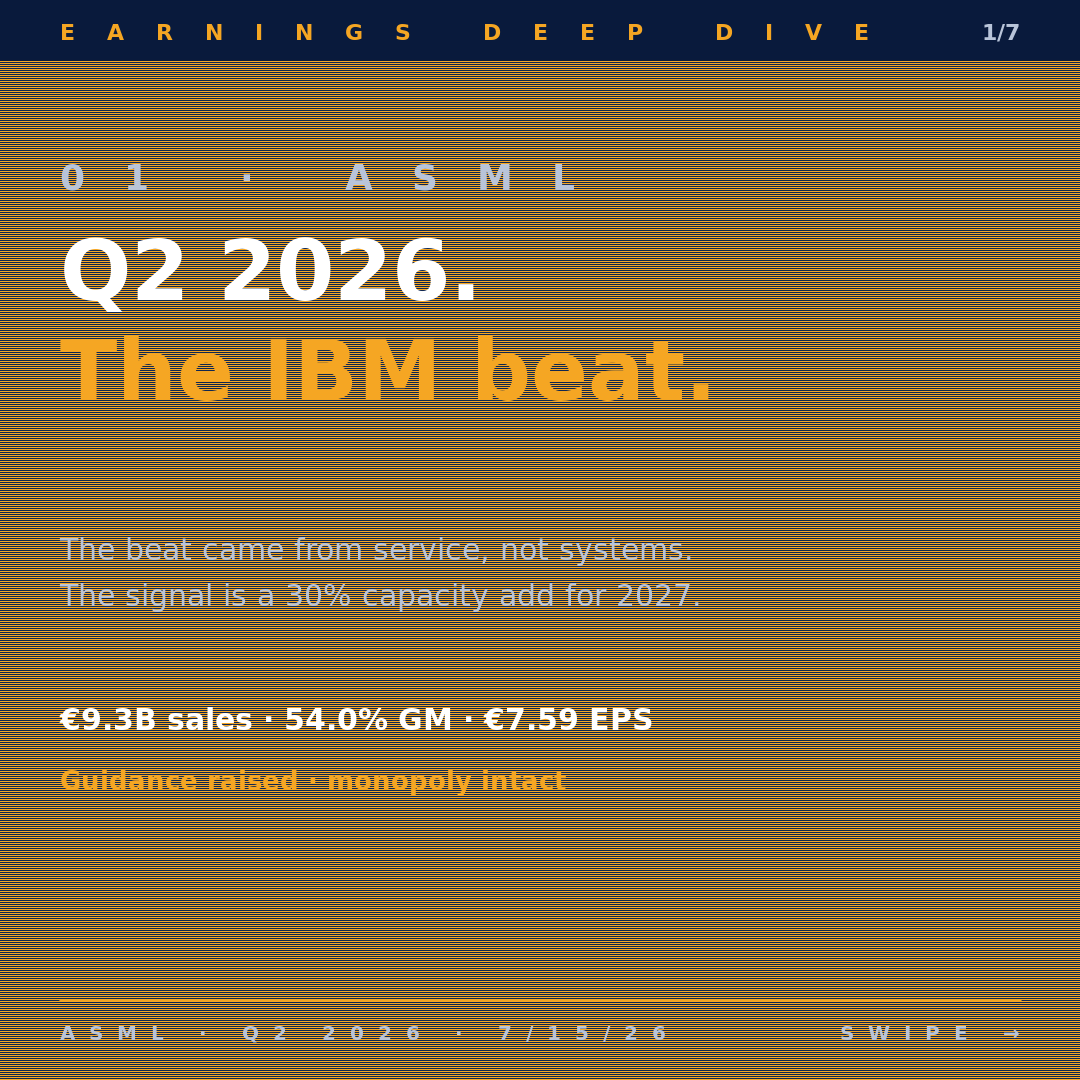
The answer, in a sentence: demand is not fading, and management put capacity money behind that view.
The numbers
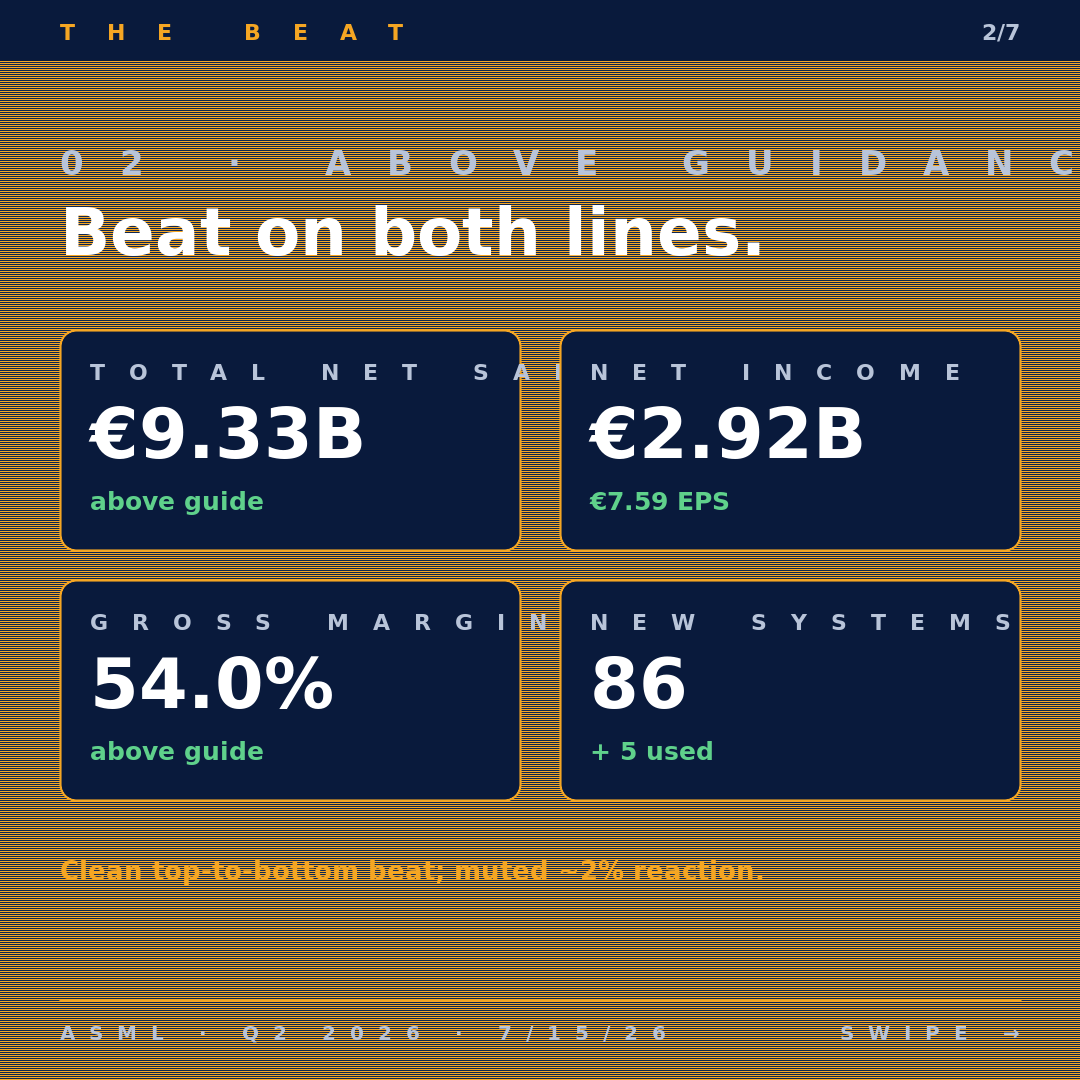
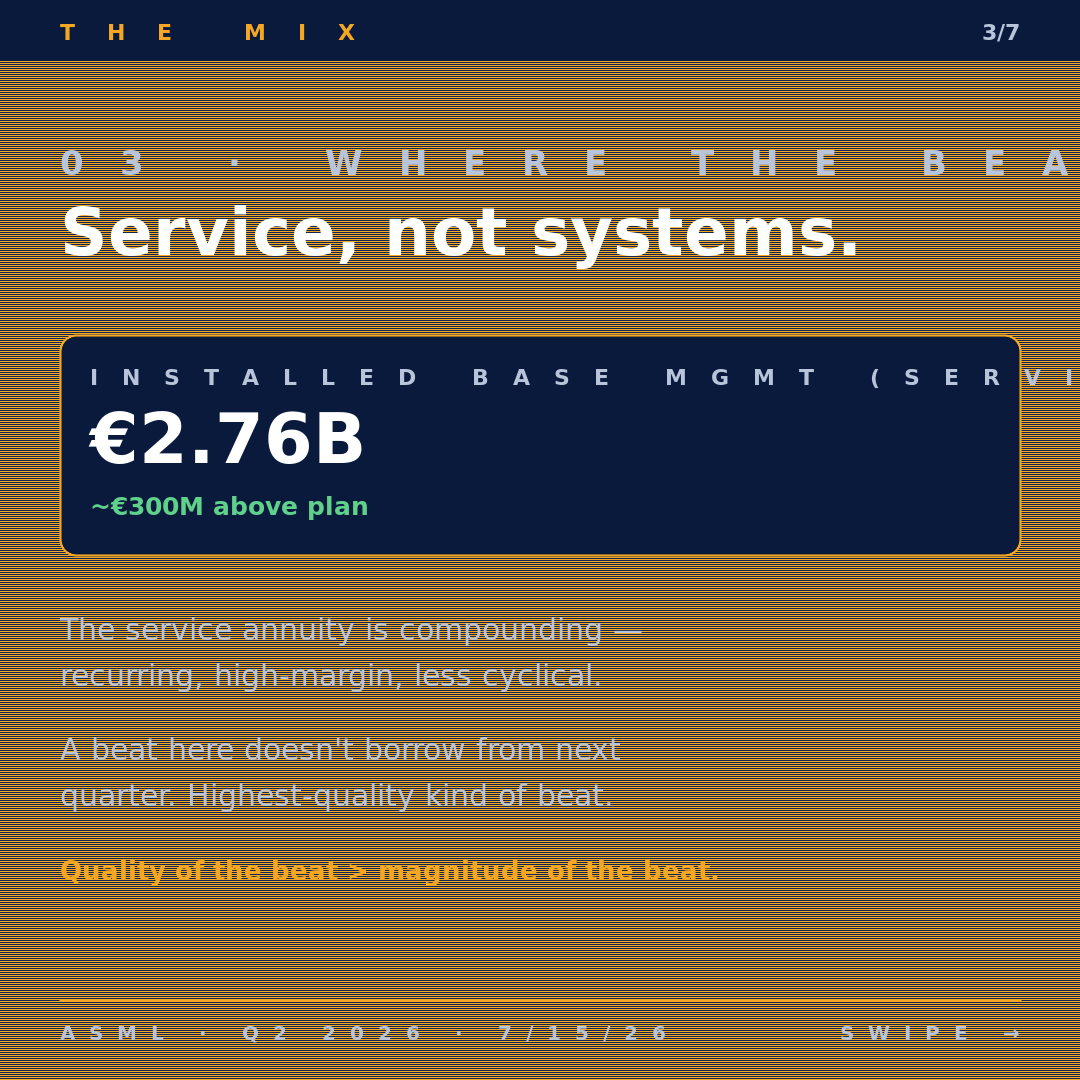
Q2 total net sales came in at €9.33B against a gross margin of 54.0%, both above the guided range, with net income of €2.92B and basic EPS of €7.59. The composition matters more than the beat: the upside was carried by Installed Base Management (IBM) sales of €2.76B — service and field upgrades — which ran roughly €300M above plan. New-system units were 86 (plus 5 used). This was a services-led beat on a stable systems base, which is a higher-quality mix than a lumpy tool pull-in.
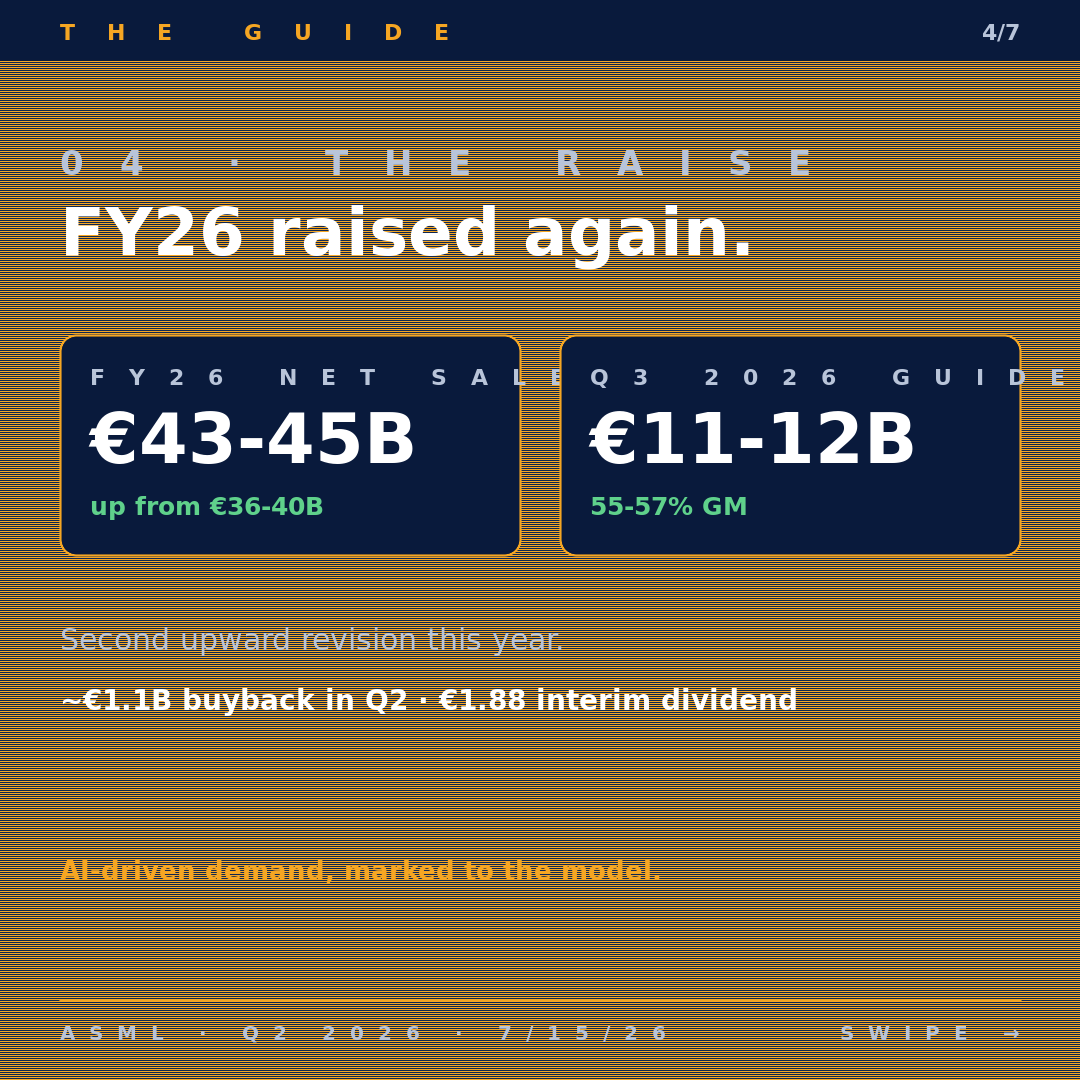
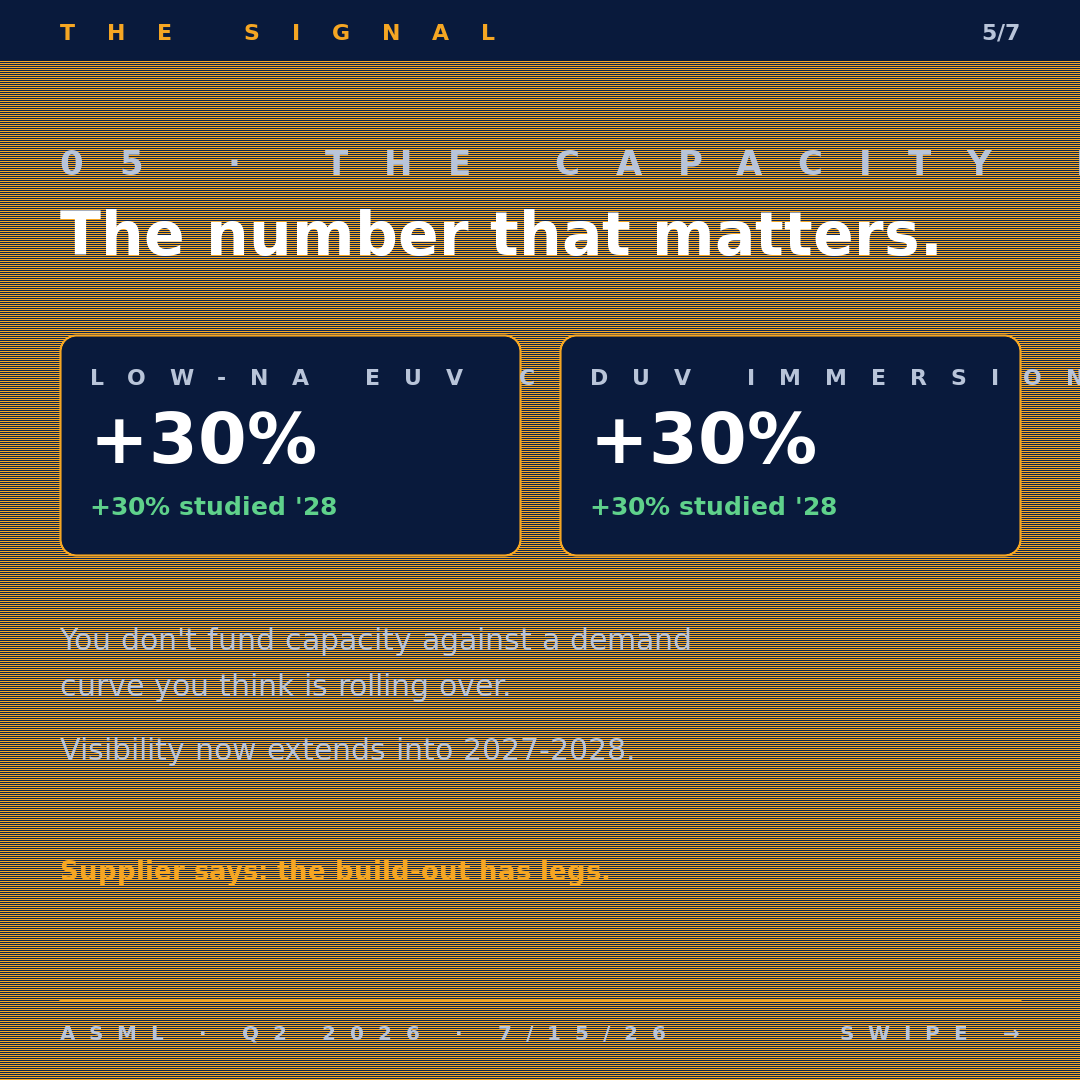
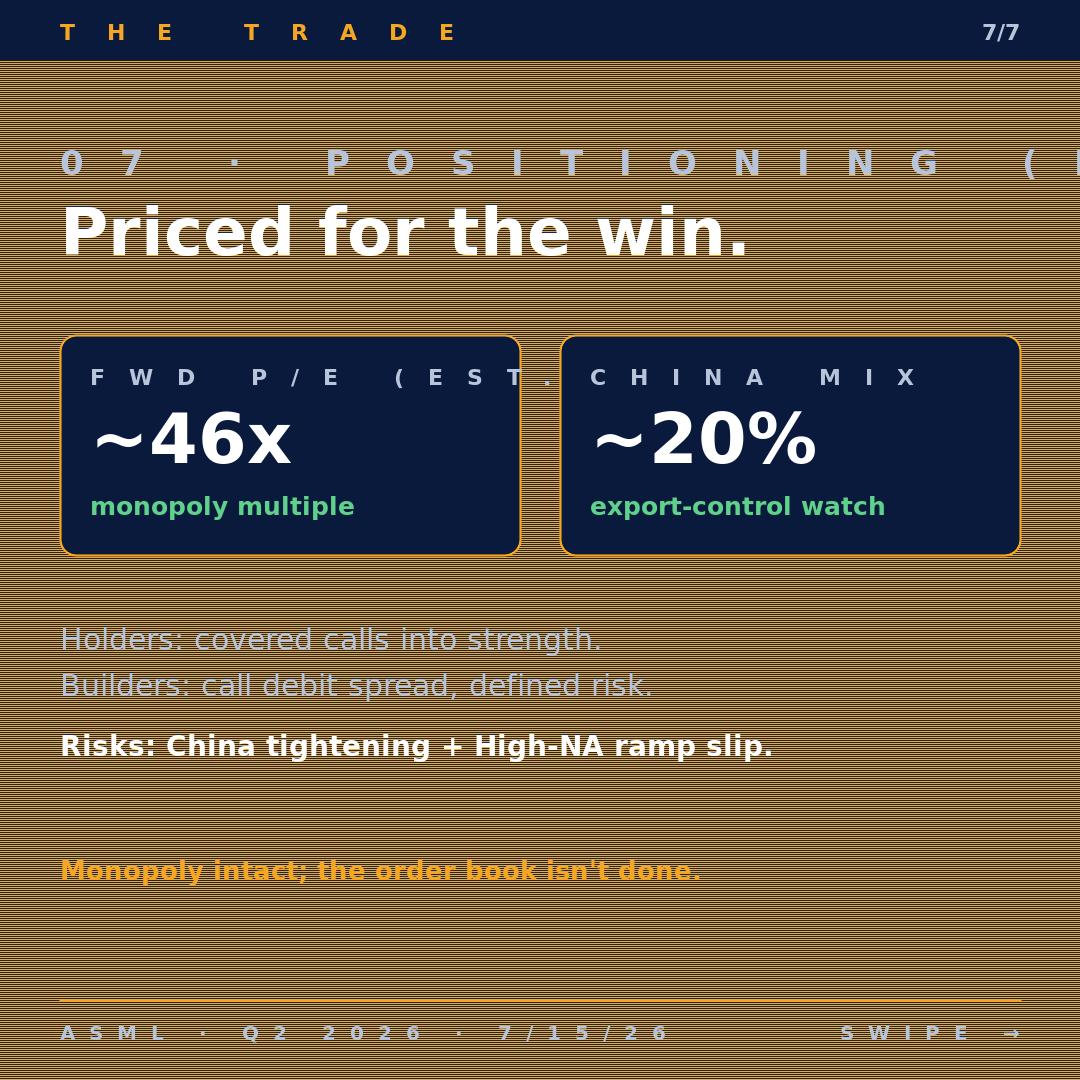
The guide is where the real move was. Q3 2026 is set at €11.0–12.0B in sales with a 55–57% gross margin — a step-up that implies a materially stronger back half. And full-year 2026 was raised to €43–45B at 54–56% GM, up from a prior €36–40B frame — the second upward revision this year. Capital return continued alongside: ~€1.1B of buyback executed in Q2 under the 2026–2028 program, and a €1.88/share interim dividend payable . China held at ~20% of sales. Shares traded up ~2% on the day (ADS ~$1,815 unverified) — a contained reaction that tells you a lot of good news was already in.
The rest of this dive is for paid subscribers.
The headline numbers are above. The 6 sections below carry the mechanism, the peer read, the valuation work, and the dated tests that decide it.
- What's actually driving it
- How peers read this
- Valuation reality check
- What we'd watch from here
- Listed-market read-through
- Bottom line
Already a subscriber? Sign in.