From the editor
This issue covers to 7, 2026. Figures come from original company releases, Korea's trade statistics and research firms; Transcend's and ADATA's remarks are read through Taiwanese press reports in Chinese, and AMD's call remarks through a press report. Samsung's results and a DIGITIMES Research report dated predate the window and are used as context. Stances on named companies are analytical positioning, not recommendations to buy or sell any security. Data limits this week: 9 of 16 demand lanes are unavailable to the pipeline; the hyperscaler capex grid is stale, with Microsoft, Meta and Oracle figures carried from August and September; the pipeline's credit read is stable with no verified stress event, but six unverified stress reports, including note pricing at a GPU-cloud borrower and an AI-developer financing, leave it one verified confirmation from tightening; six of seven collection nights are present; TLC/QLC NAND, DDR5 and server contract tables have been silent for 39 days, so those tapes rest on spot and supplier commentary.
The Read
Transcend says suppliers flagged limited early-2027 DRAM supply while Chinese vendors' phone shipments fall and AMD plans for fewer PCs in 2027, even as AMD's data center revenue rose 97%.
allocations tighten, the consumer gives way
Watch · the week in 3 minutes
01 · Signal
the ai side keeps compounding
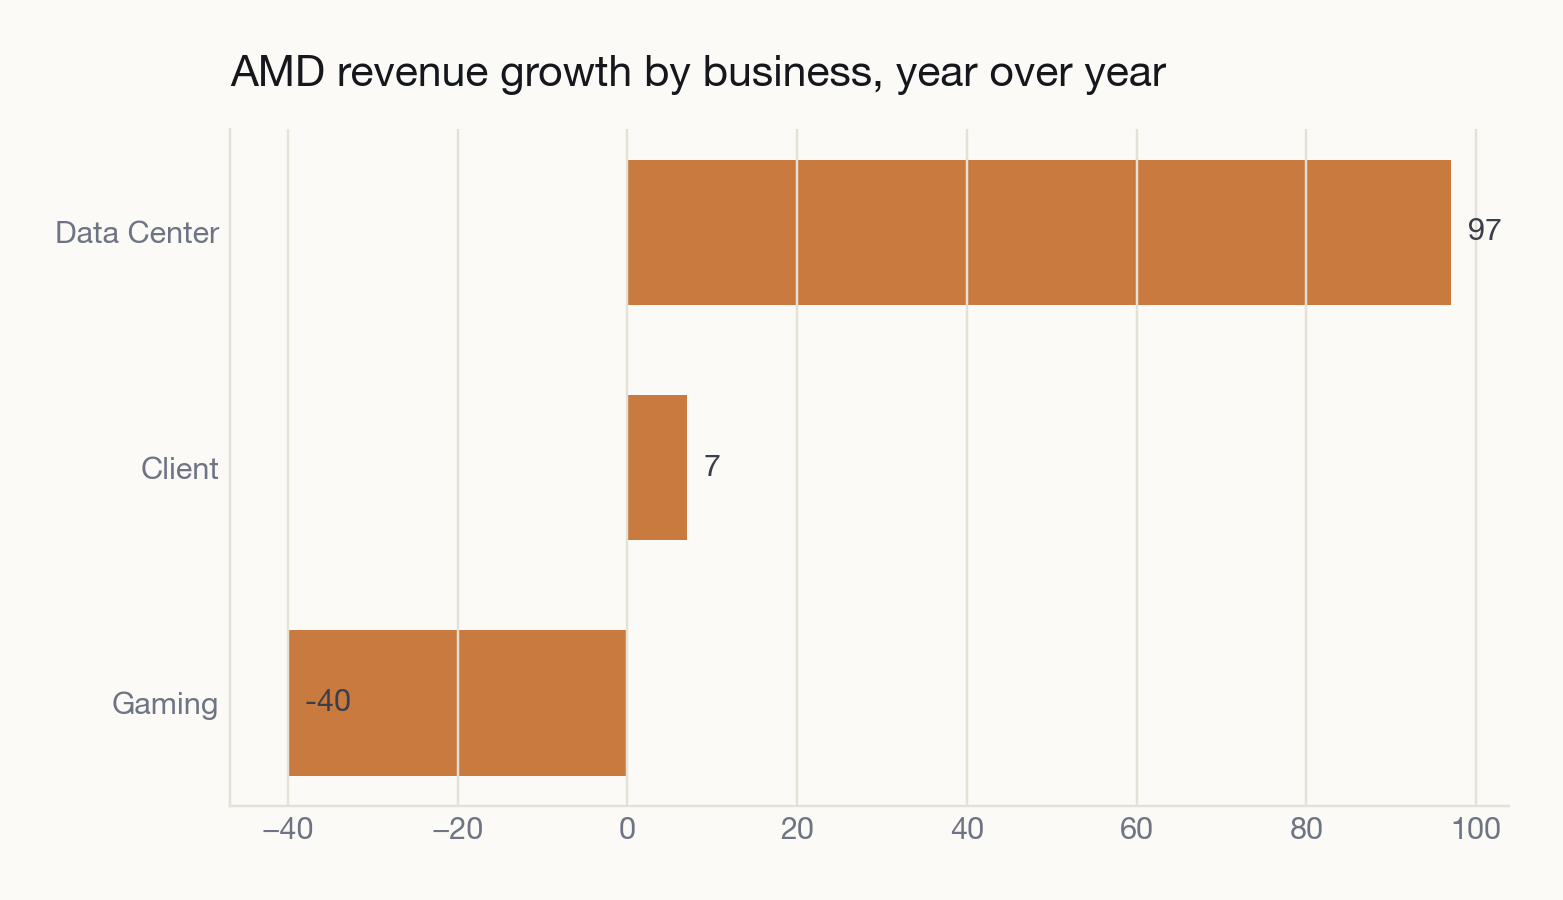
AMD's Data Center revenue was a record $8.5 billion in the third quarter, up 97% year over year, and AMD expects fourth-quarter revenue of about $17 billion, a company forecast. Korea's semiconductor exports rose 259.4% to USD 56.44 billion in October, second only to September's record USD 60.3 billion, per the trade ministry's report. Samsung said on that AI-driven demand in 2027 will far exceed industry supply, also a company forecast.
AMD revenue growth by business, year over year · YoY revenue growth (%), as reported · Q3 2026SOURCE · company releases, frozen bundle
The data center side is still compounding. Inside AMD, the consumer lines already split: client up 7%, gaming down 40%.
02 · Signal
phone shipments fall, and AMD plans for fewer PCs
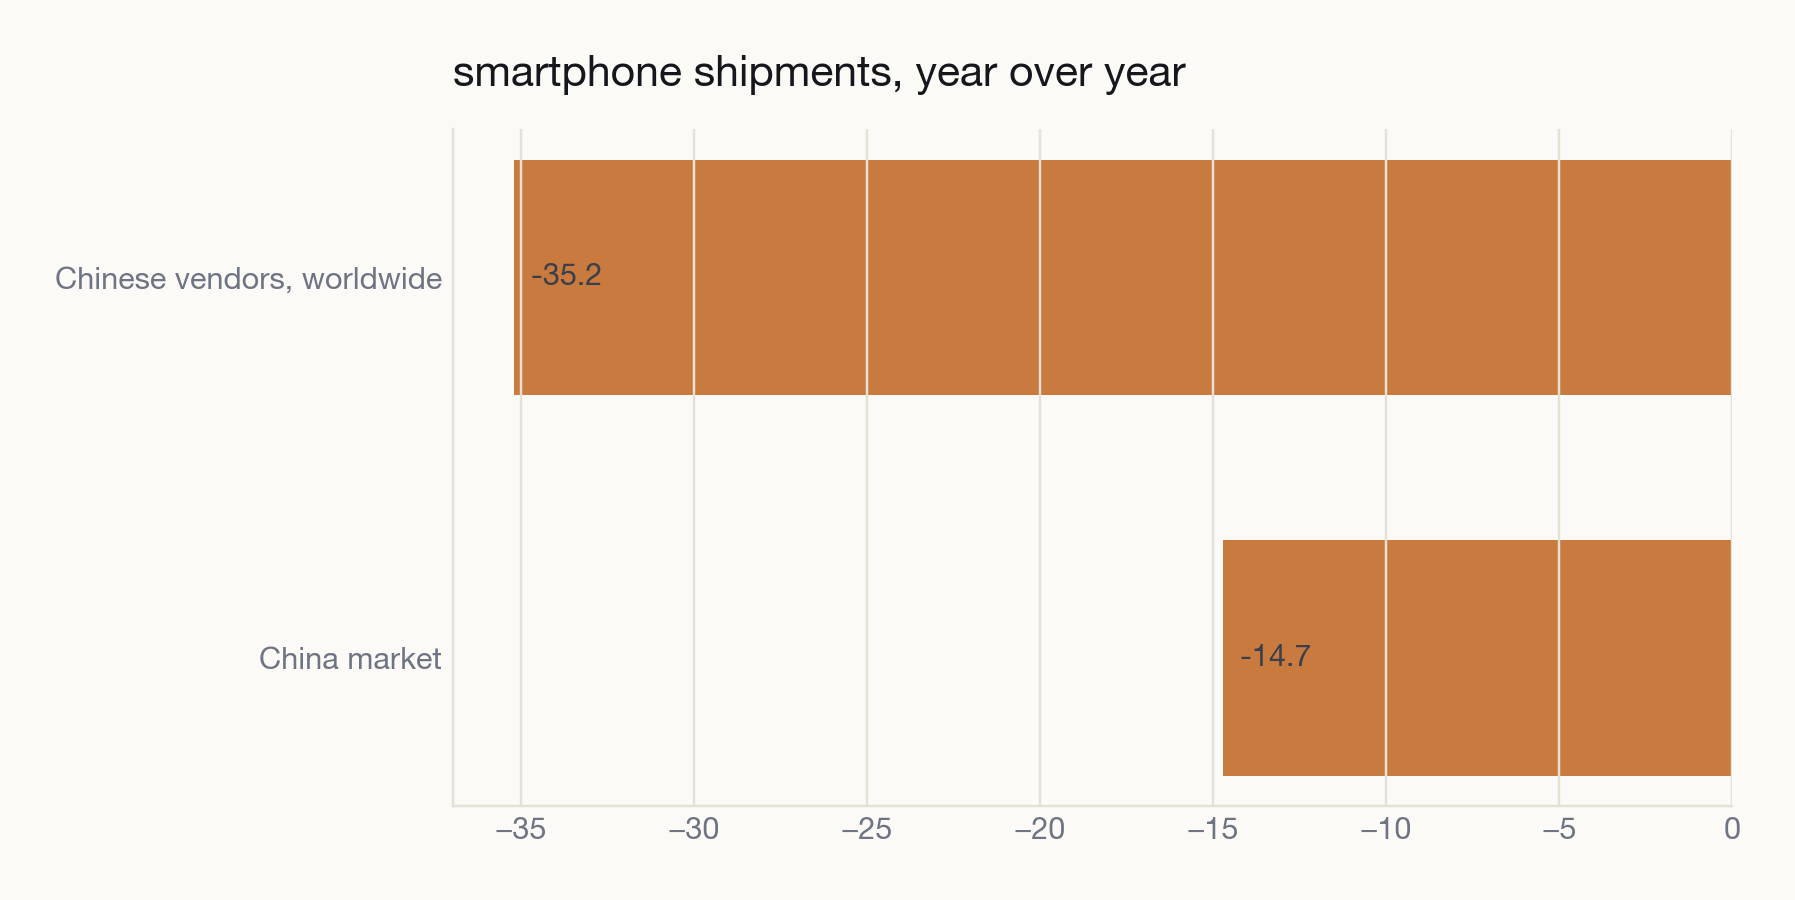
A DIGITIMES Research report dated counts 114.7 million smartphones shipped by Chinese vendors in the third quarter, down 35.2% year over year, with their overseas shipments down more than 40%. On its third-quarter call, AMD said it is planning for PC unit shipments to decline by a double-digit percentage in 2027, after PC sell-through slowed late in the quarter on higher memory and component costs. TrendForce expects reballed memory in 3–4% of smartphones in 2026 and 7–9% in 2027, particularly entry-level and budget models.
smartphone shipments, year over year · YoY unit shipment change (%), DIGITIMES Research · Q3 2026SOURCE · company releases, frozen bundle
Phone shipments are already falling and AMD is planning for fewer PCs, while suppliers flag tighter supply. Which side gives first is open.
03 · Signal
module makers hear tighter supply, and see a ceiling
Transcend's chairman said on that suppliers have told the company first-half 2027 supply will be limited and first-quarter supply may fall further, that room for further memory price rises is limited, and that he expects the fourth quarter to look like the third. ADATA expects fourth-quarter revenue slightly below the third quarter as customers settle year-end inventory, while saying next year's DRAM shortage may be worse than this year's and that large cloud providers already hold most capacity.
Suppliers are flagging tighter supply at the module makers' door, yet the makers expect a flat or softer quarter, not a surge.
The Call · Korea's November Chip Exports Against October
The call: Korea's semiconductor export total in the trade ministry's first monthly report is at or above October's USD 56.44 billion in the comparable reported period result published from 2026-11-10 through 2026-12-07. It fails if the same observation is below October's USD 56.44 billion. Only that observation grades the call, with a measurement dated from 2026-12-01 through 2026-12-07 on the same series and basis. If no comparable observation is published by 2026-12-07, the call is void. This tests Korea's November chip export total against October only. The reported accounting period is 2026-11-01 through 2026-11-30.
Through the trade ministry's November report, this issue's graded call. Samsung: constructive, on its own forecast for 2027 demand; SK hynix: no company-specific source this week, so no stance. Korea's chip exports are a public monthly read on the export value of Korea's chip industry, and October's USD 56.44 billion sat below September's record USD 60.3 billion. What would change it: a November figure below October's as weaker phone and PC demand reaches the suppliers. Samsung said on that it expects AI-driven demand in 2027 to far exceed industry supply, a company forecast. Korea's average daily exports of all goods, adjusted for working days, rose 76.1% in October, below the 93.7% headline, so calendar effects move these monthly figures.
§
Before TrendForce's next weekly spot update, which the pipeline expects around . Micron and Samsung on client DDR5: neutral. The pipeline's only BUY, client DDR5 at Samsung and Micron, is provisional and reconciled to HOLD, because tightening allocations meet contracting client demand. What would change it: DRAM spot breaking below contract on TrendForce's next weekly update, or a flat November PC DDR4 contract print around , either of which the pipeline flags would put client DRAM on NAND's path. TrendForce reported on that DDR4 spot prices remained above suppliers' official quotes despite weak demand, fueling correction expectations. The pipeline moved HBM from BUY back to HOLD this week until a renewed HBM supply read arrives; its HBM segment state stays Tightening.
§
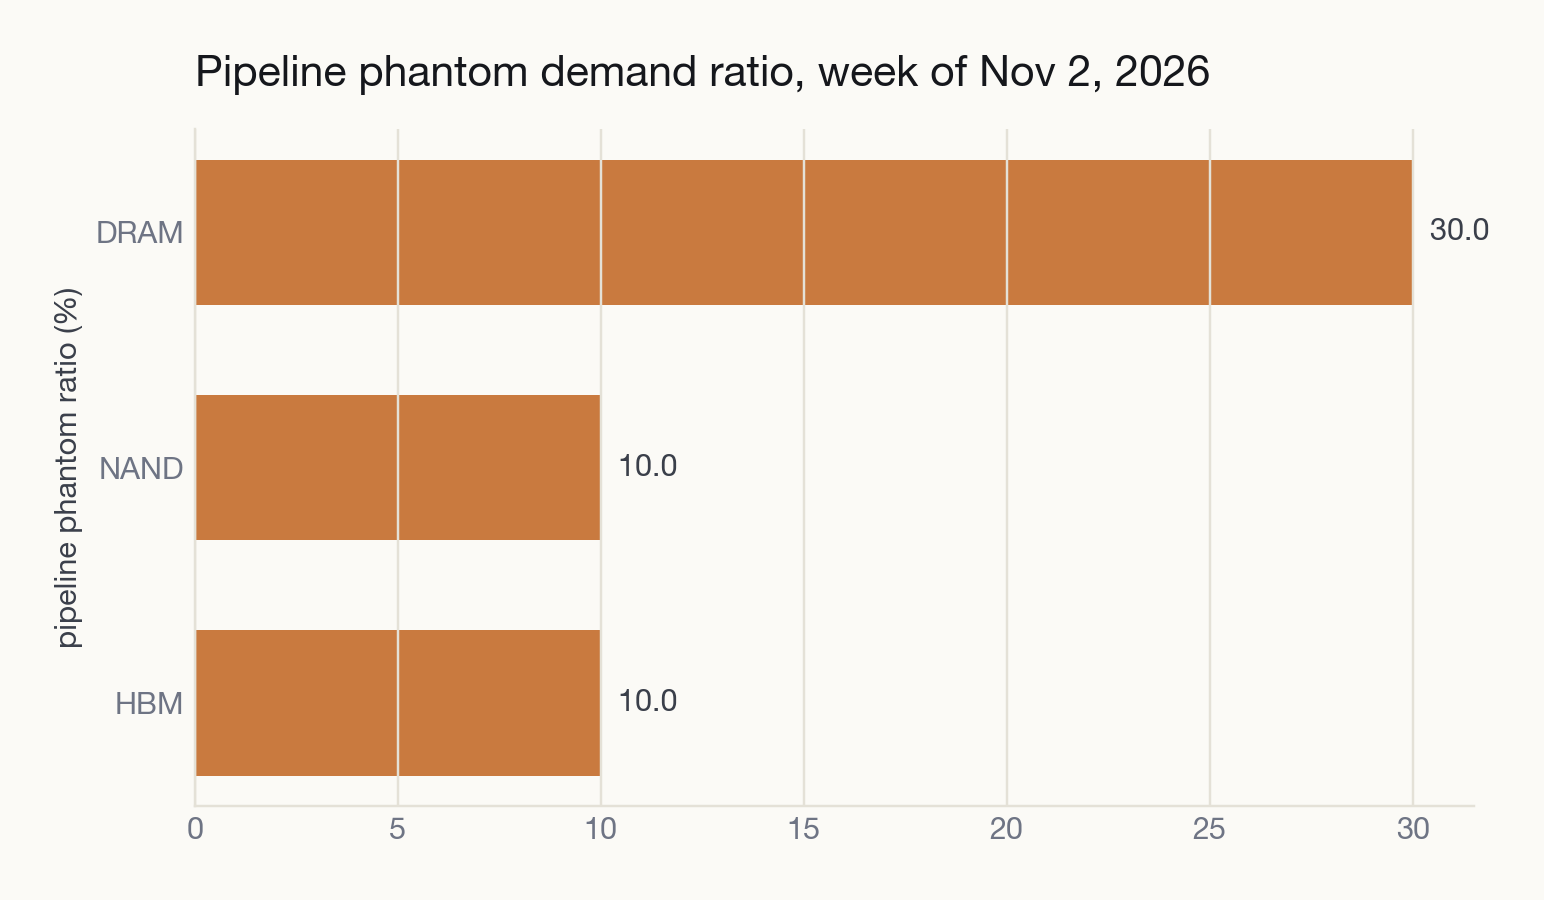
Into the first quarter of 2027, as suppliers set allocations. Transcend and ADATA: neutral. Both describe tight DRAM supply into 2027, and both expect a flat or softer fourth quarter. Channel NAND: cautious, as a lane rather than a name; the pipeline holds channel TLC at committed volumes, buys China client SSD below plan, and grades channel TLC demand quality as phantom. What would change it: TrendForce's TLC wafer spot turning up week over week. TrendForce says Double 11 discounts are unlikely to revive NAND demand. The pipeline counts enterprise SSD as the one firm NAND leg, on 2027 supply already committed under long contracts, but has no direct instrument for it. It also holds client DDR4 at committed volumes while that contract still rises, and China LPDDR while channel quotes stay flat.
Sources
Transcend says suppliers flagged limited early-2027 DRAM supply — news.cnyes.com