From the editor
tkal is a daily synthesis of the credit, demand, and capex cascades I've been running for myself. Receipts published weekly: every dated call gets graded, blindly, against what actually happened. The premise is that most market writing is unfalsifiable by design — vague enough to be re-narrated after the fact. This is the opposite. The conviction level is on the call. The horizon is on the call. The falsifier — the thing that would prove it wrong — is on the call. If the call misses, it's in the scorecard. If it hits, also in the scorecard. The newsletter is what the model saw this week; the scorecard is whether the model has been right. Not investment advice. Positions may exist in the names discussed.
The Read
AI memory is going under 2027 contracts while PCs fall 21% and phones a record 22%, and the book now has no buy anywhere ahead of the contract print.
ai memory under contract, consumer memory rolls over
01 · Signal
consumer demand destruction turns significant
Counterpoint has Q3 PC shipments down 21% and sees the Q4 decline deepening to 27%. IDC has smartphones down 22%, a record drop it ties to the memory crisis. China smartphone shipments hit a 14-year low, with Huawei and Apple bucking the downtrend. Chinese phone makers are turning to recycled DRAM in budget models after the first-half stock build. The demand pipeline escalated consumer destruction to SIGNIFICANT.
Units fell more than a fifth at today's memory prices. The consumer lane is now hard data, not a forecast.
02 · Signal
the ai side locks into 2027 and splits from client
Samsung reportedly has about 80% of its 2027 memory output under long-term agreements, all HBM included, which shrinks the open market. Supermicro lifted its revenue forecast. The demand balance still reads MODERATE_UP for HBM at +3.2 and server DDR5 at +2.6, while client DDR5, client DDR4 and LPDDR all slipped to slightly down. HBM share is reportedly shifting toward Samsung on HBM4. Last week's Micron HBM buy was withdrawn, so HBM is a hold across vendors.
The split is inside DRAM now. Server and HBM hold up while every client lane tips slightly down.
03 · Signal
channel nand falls as china supply grows
Channel TLC fell further: its demand balance moved to -2.50 from -1.72, the reversal score is 4, and wafer spot has dropped two weeks running while contract forecasts still call for +15-20%. The supply side moved NAND to PASS. China supply is growing on both sides: YMTC passed Samsung in China NAND share, 38.5% to 33.5%, and is adding LPDDR5 at Fab 2, while CXMT plans to lift DRAM capacity from about 320k to 420k+ wafers a month within a year.
Contract forecasts point up and the channel points down. The October print decides which one the book believes.
The Call · Consumer Memory Rolls Over
The book holds no buy, and the read is that consumer memory is rolling over while AI memory goes under 2027 contracts. The October contract print around is the test: a DRAM or NAND miss against the +15-20% forecasts confirms it, and a NAND print at or above +15% breaks it.
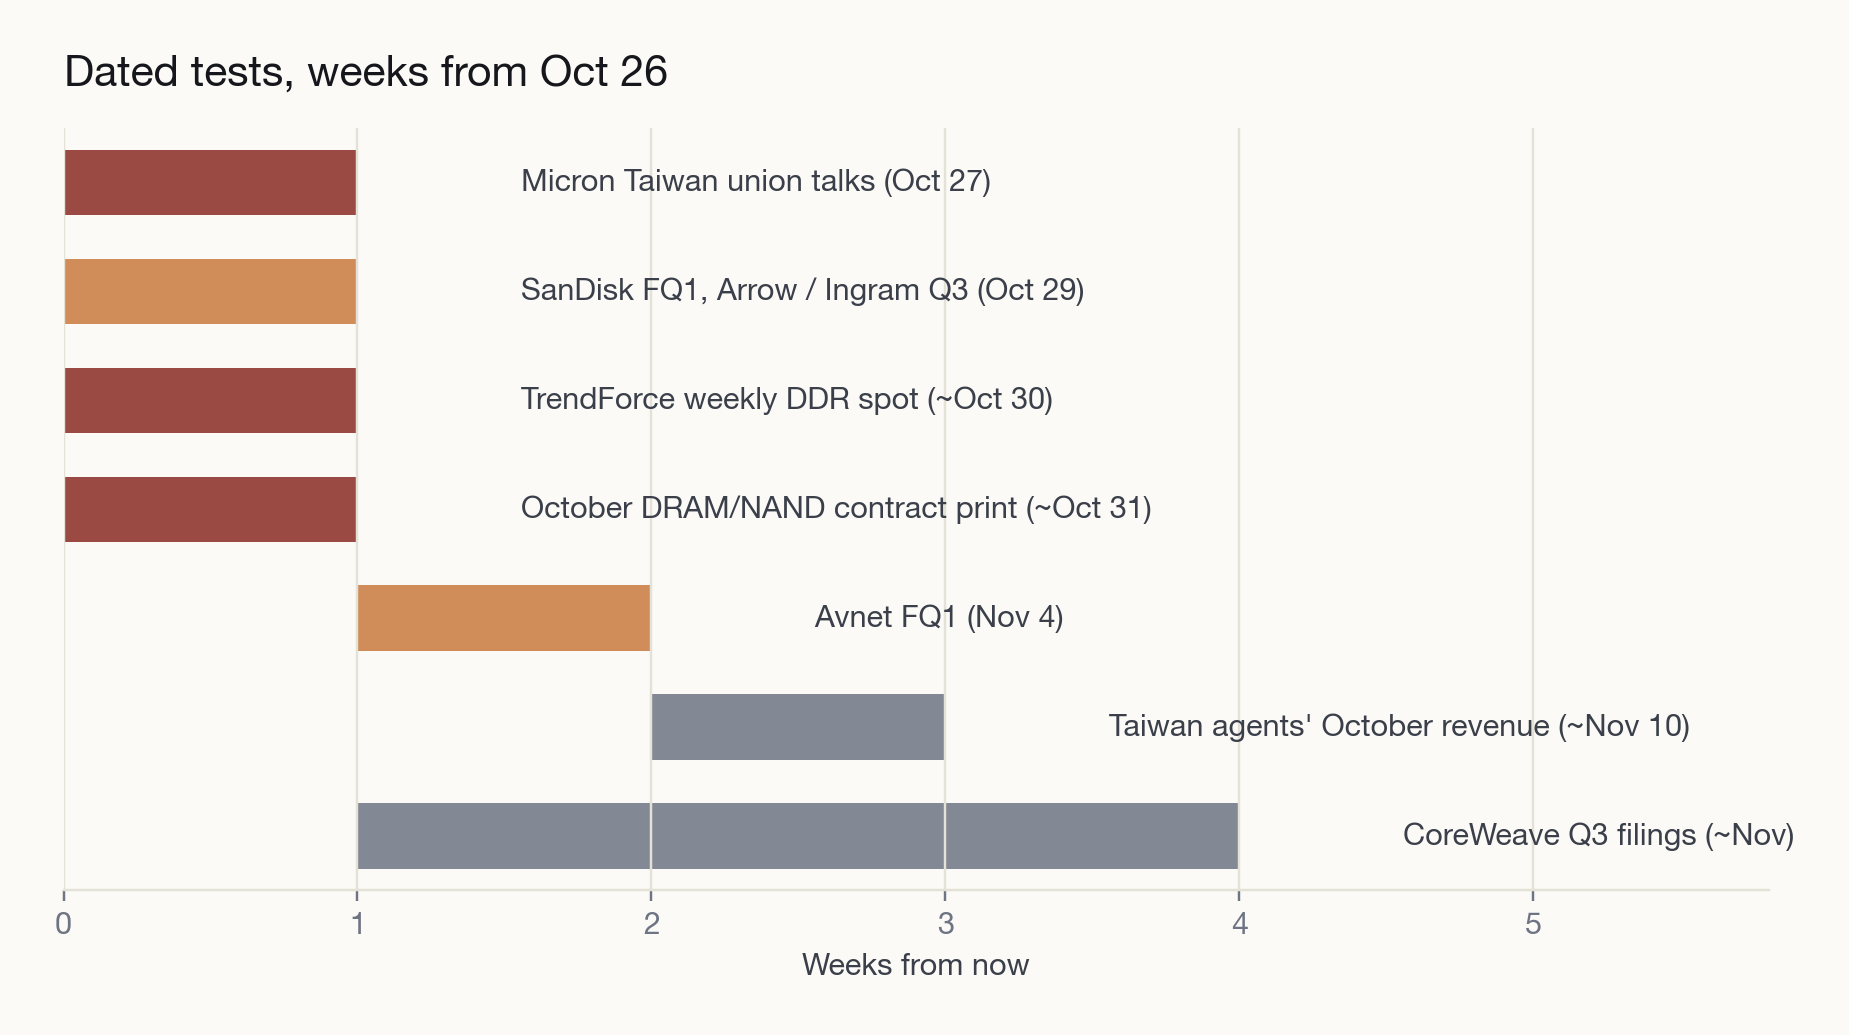
Between the Micron talks and SanDisk on . Read enterprise SSD through SanDisk, not through supply talk. Signs of eSSD allocation tightening would move the lane off hold. Fourth-quarter eSSD talks are struggling to push increases above 30%. Micron's Taiwan Taoyuan union talks resume , and labor escalation would tighten DRAM supply against a book with no buy. Micron and SanDisk are the names to watch.
§
Across the spot and contract prints. Treat client DDR as the disputed lane. A second weekly spot decline trips the client DDR trigger, and a contract miss confirms the rollover. China module quotes already fell, and DDR4 is trading weak under a 0.84% mainstream spot gain. NAND contract forecasts sit at +15-20% against falling wafer spot. Samsung, SK hynix and Kioxia are the read-through names.
§
By the Taiwan memory agents' October revenue, around . Watch for pull-forward payback. Agent revenue down month over month while contract prices rise would confirm it. Avnet reports FQ1 on , and a book-to-bill below 1.0 or rising inventory would point the same way. Arrow and Ingram report around .