From the editor
tkal is a daily synthesis of the credit, demand, and capex cascades I've been running for myself. Receipts published weekly: every dated call gets graded, blindly, against what actually happened. The premise is that most market writing is unfalsifiable by design — vague enough to be re-narrated after the fact. This is the opposite. The conviction level is on the call. The horizon is on the call. The falsifier — the thing that would prove it wrong — is on the call. If the call misses, it's in the scorecard. If it hits, also in the scorecard. The newsletter is what the model saw this week; the scorecard is whether the model has been right. Not investment advice. Positions may exist in the names discussed.
The Read
AI memory is sold out to 2027 while PC and phone units fall about 20% on price, and the book's one buy is now Micron-only, facing an labor deadline.
ai memory sold out, consumer demand breaks
01 · Signal
micron fills the ai book on its own
Micron says HBM bookings are fully taken through 2027 and its new Taichung fab's 2027 capacity is sold out. It opened a second Taichung HBM assembly and test fab, with a Singapore plant planned for 2027. Its long-term agreements rose to 26 from 16 in June, mostly backed by customer cash deposits. Microsoft's Maia 300 moves to eight HBM4 stacks per chip. The support is first-party now, but the buy narrowed: Samsung and SK hynix HBM4 fell to HOLD.
Better support, narrower bet. One supplier now carries the only buy, and the 2027 pull-forward question is still open.
02 · Signal
consumer demand breaks on price
Three Tier-1 trackers printed the same quarter. IDC has Q3 PC shipments down 20.1% and Gartner down 22.4%, both tied to memory costs raising prices. Counterpoint puts smartphones down 20% year over year, the lowest in 14 years, and IDC has China smartphones down 15.4%. Supply still squeezes the other way: Nanya's 3Q DRAM ASP rose more than 60% quarter over quarter on lower bit shipments. The demand pipeline moved destruction to MEDIUM confidence.
Client DRAM contract prices still rise on supply exit while the units that use them fall. One of those gives first.
03 · Signal
channel nand trades below official for a third week
Traders in China dumped channel NAND below official prices for a third week, and the channel TLC reversal score rose to 4, risk HIGH. China-sited supply is growing: YMTC climbed to No. 3 in global NAND shipments with a 16.5% share and filed for a STAR-market IPO, and SK hynix/Solidigm is seeking a wider US tool-export licence for its Dalian fab. Longsys says DRAM and NAND price gains narrowed markedly in 3Q26. Enterprise SSD reads tight on supply evidence only.
Enterprise SSD tightness is a supply story with no demand read behind it. The channel is where the softening shows first.
The Call · Micron HBM, Provisionally
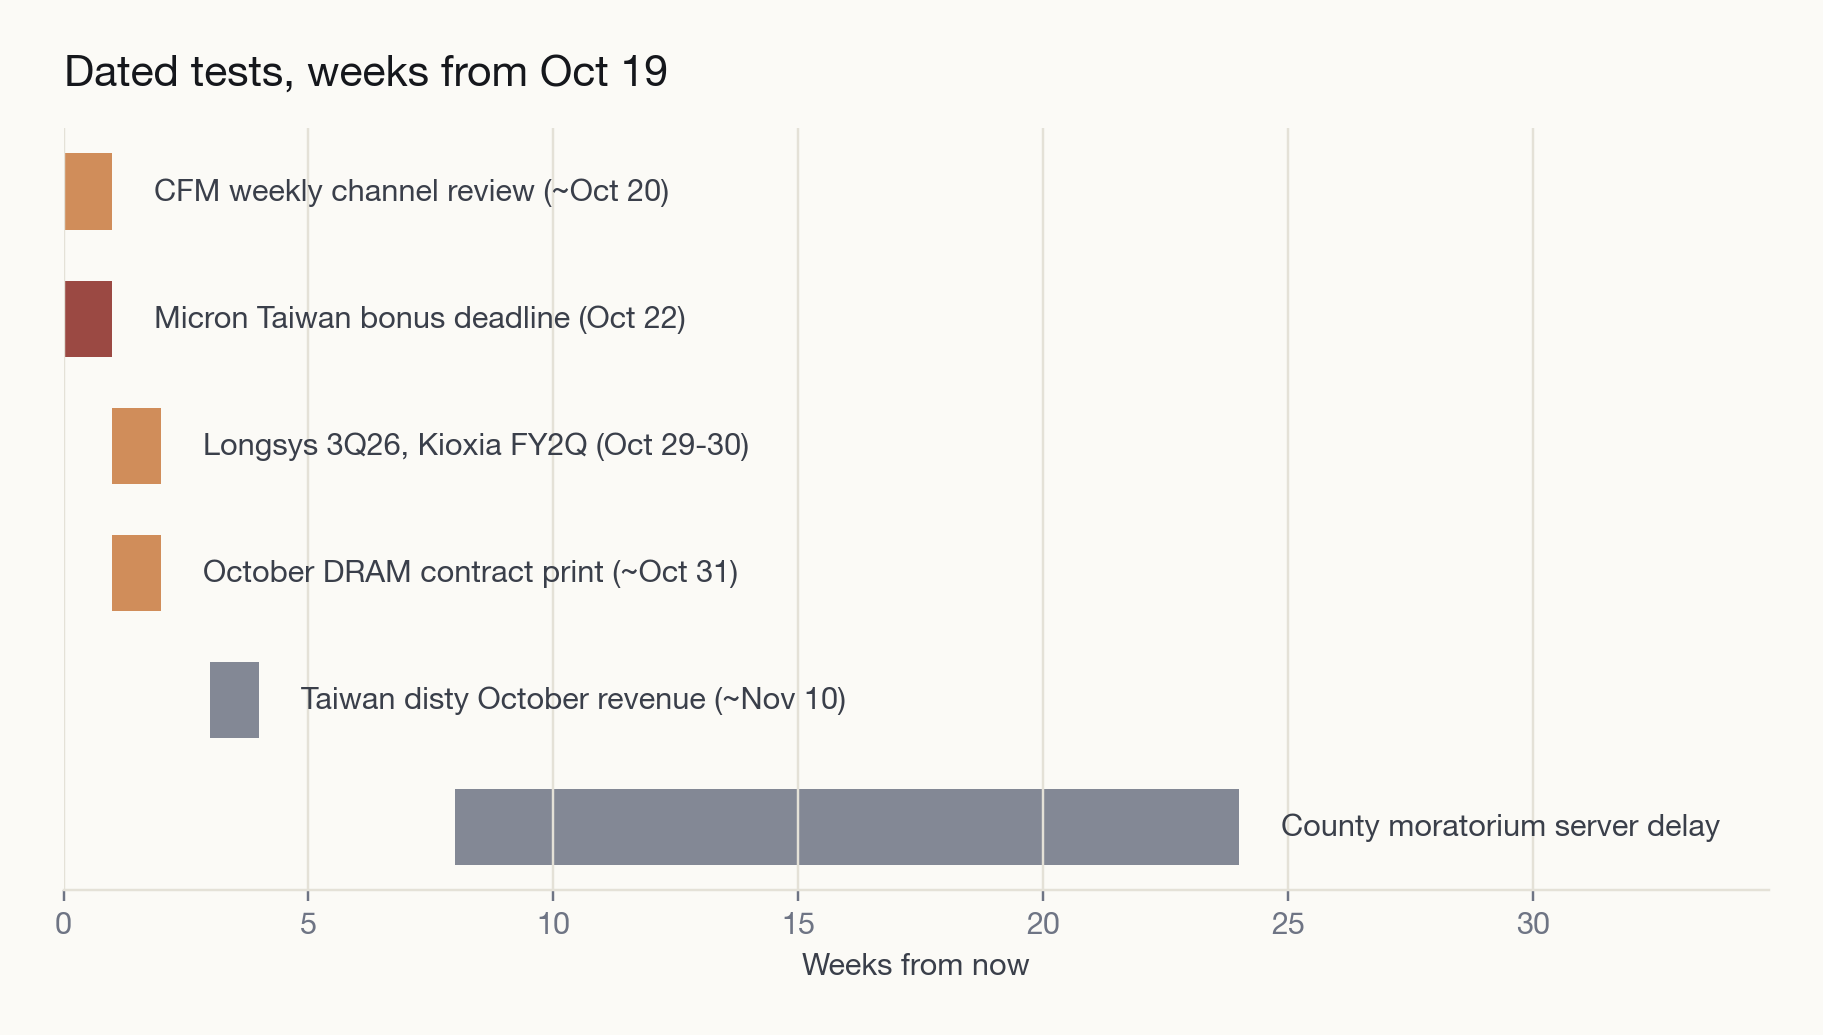
The book stays defensive, and its one buy, 2027 HBM from Micron, is now a single-supplier call. The Micron Taiwan bonus deadline is the first test; a strike or output loss fires the reversal.
By the Micron Taiwan bonus deadline. Read Micron's 2027 HBM story through Taiwan supply continuity, not bookings. A strike notice, work stoppage or disclosed output loss breaks the only buy. The union rally is . Micron's second Taichung HBM assembly and test fab is open and Singapore is planned for 2027, so Taiwan carries the near-term output. Samsung and SK hynix HBM4 sit at HOLD.
§
At the CFM weekly channel review, around . Treat it as the channel NAND test. A wider gap between trade and official wafer prices, or eMMC/UFS cuts above 64GB, confirms liquidation. CFM already shows eMMC at 64GB and below under pressure while DRAM modules still rise. YMTC's No. 3 rank and the Dalian licence request both add China-sited NAND supply. Kioxia and SanDisk are the names to watch.
§
Across the -31 prints. Longsys decides whether narrower gains turn into channel price declines. The end-October DRAM contract print shows whether the client DRAM premium has closed. Longsys reports 3Q26 on and Kioxia FY2Q on , where eSSD supply easing or price cuts would reverse the enterprise SSD tilt. Contract at or above DDR4 spot around closes the premium. The DRAM contract table is 48 days stale.