From the editor
tkal is a daily synthesis of the credit, demand, and capex cascades I've been running for myself. Receipts published weekly: every dated call gets graded, blindly, against what actually happened. The premise is that most market writing is unfalsifiable by design — vague enough to be re-narrated after the fact. This is the opposite. The conviction level is on the call. The horizon is on the call. The falsifier — the thing that would prove it wrong — is on the call. If the call misses, it's in the scorecard. If it hits, also in the scorecard. The newsletter is what the model saw this week; the scorecard is whether the model has been right. Not investment advice. Positions may exist in the names discussed.
The Read
Hyperscalers are pulling enterprise SSDs at 16-week lead times while China traders dump hoarded wafers at January prices, and Micron's print is the first first-party test of which side holds.
the enterprise ssd buy meets its first test
01 · Signal
enterprise pulled, the channel dumped
The NAND side of the split got sharper this week. TrendForce has North American cloud providers raising enterprise SSD forecasts, with fourth-quarter orders possibly above the third, and lead times at 16 weeks against 8 in a balanced market. In the same week CFM reported China traders selling down hoarded wafer stock, with some prices back to January levels. That is the first after-the-fact proof that earlier channel buying was stocking. The catch: every enterprise SSD read traces to one publisher.
The only buy in the book rests on one research house, and the channel it would lean on is liquidating.
02 · Signal
the open market keeps shrinking
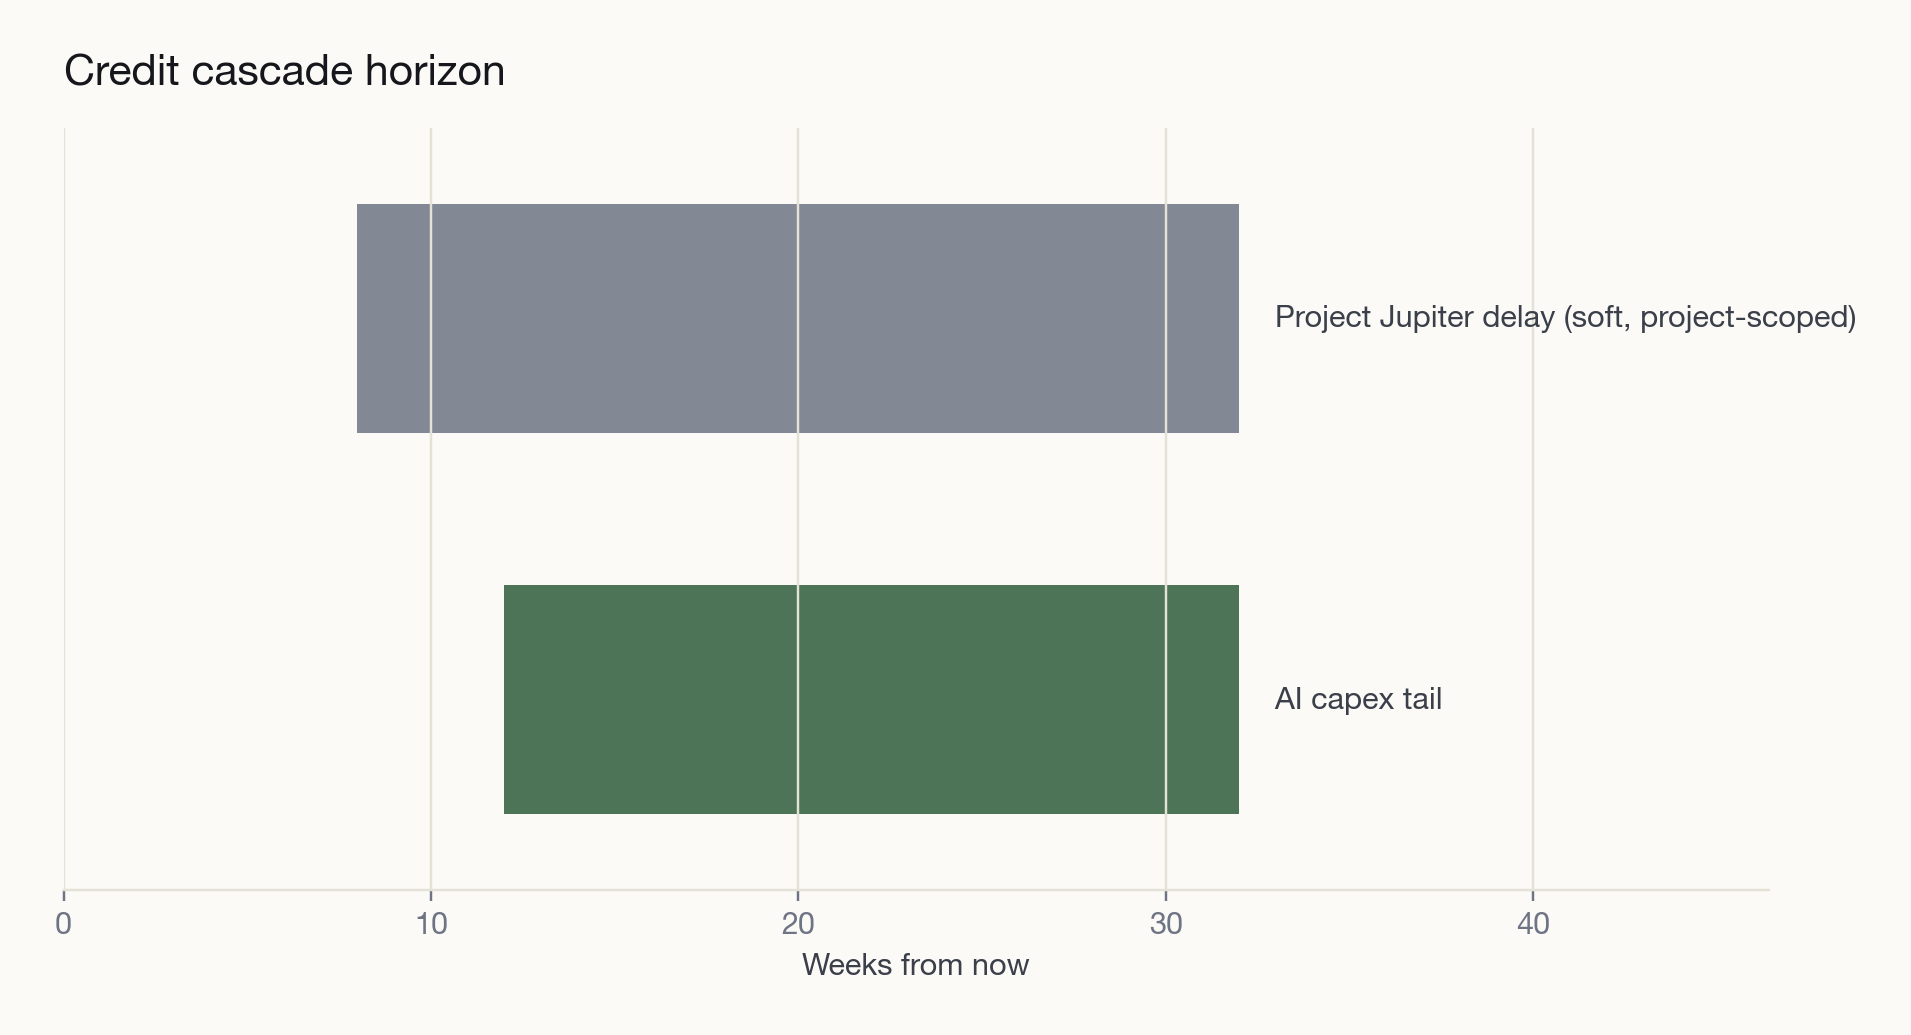
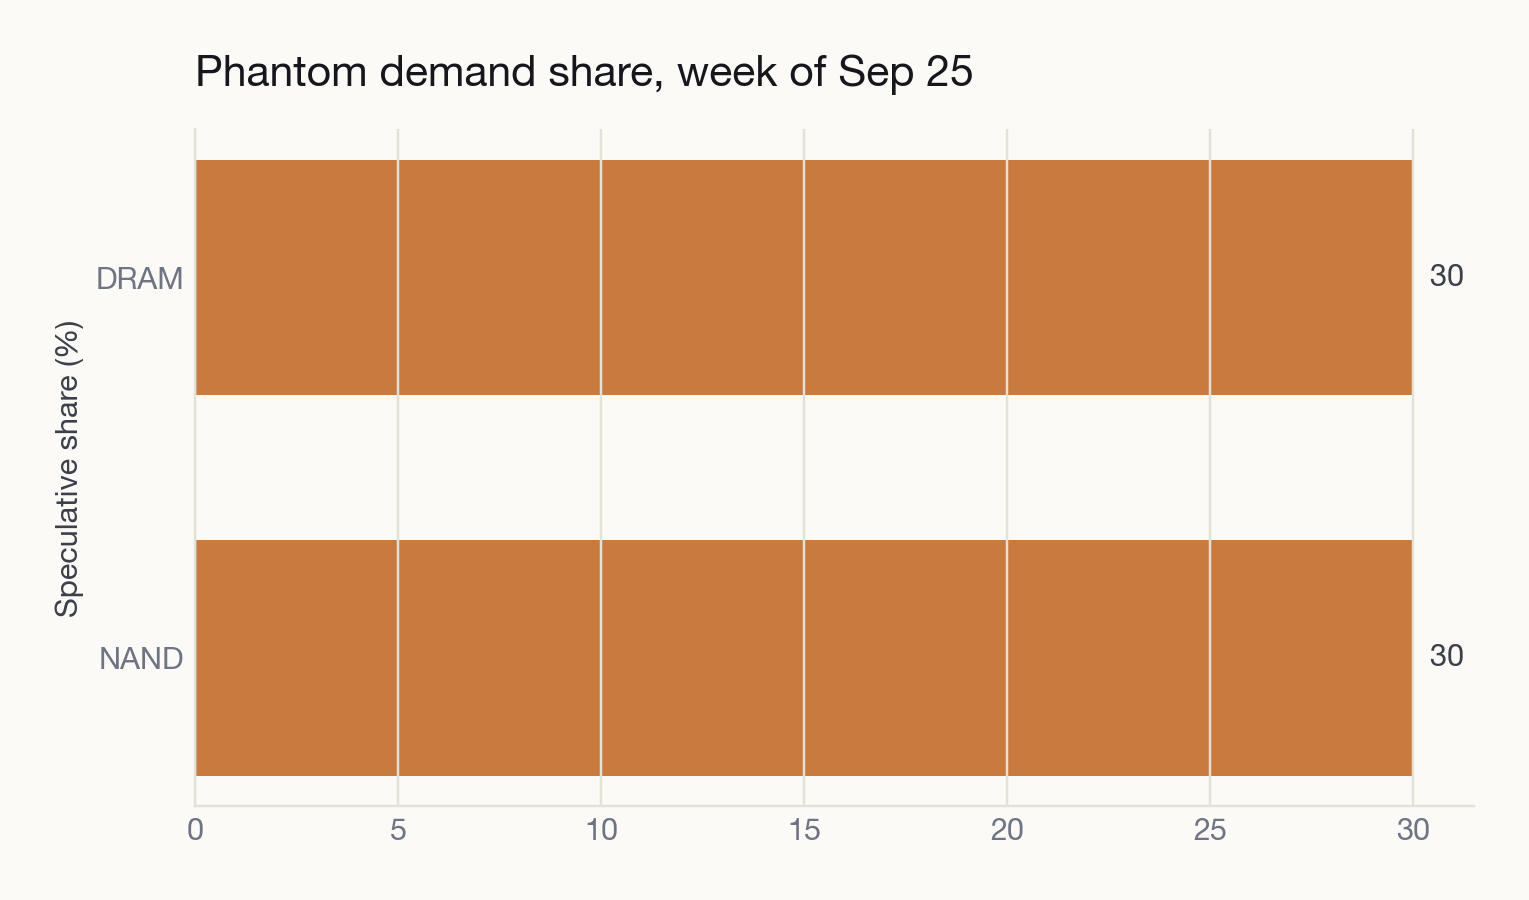
Memory makers are moving 50 to 70 percent of capacity into three- to five-year contracts. Micron is locking HBM4 output into 16 strategic customer agreements with fixed price ceilings rather than selling it spot. Buyers are receiving partial allocations at 30 to 50 percent fill rates, which confirms tightness and invites duplicate orders. Financing stays stable: one delayed Oracle project, Project Jupiter with Blue Owl, is the only drag, and its effect would land around the first half of 2027. The HBM demand lane itself carried no data this week.
Partial fills reward over-ordering, so tight supply and real demand are no longer the same measurement.
03 · Signal
china fills the share the majors vacate
The majors are pointing conventional capacity at HBM. Samsung is reported planning about 250,000 HBM wafers a month in 2027, with HBM rising to roughly 40 percent of its DRAM output. CXMT announced G5 DRAM mass production at an 11.95nm half-pitch, with at least 50 percent more gross die, and capacity reported heading to about 420,000 wafers a month by 2027. On the NAND side, a Munich court found Micron infringed two YMTC utility models. Team Group conceded talk of Chinese chips entering the channel.
Every wafer the majors move to HBM is conventional share left open, and CXMT is now scaling into it at a competitive node.
The Call · Micron FQ4,
The enterprise SSD read is the only buy the pipeline carries, and it is provisional because one publisher supports it and the QLC demand lanes carried no data. Micron's fiscal fourth-quarter print on is the first first-party test: data-center NAND softening or customer inventory builds would unwind it.
Before Micron's fiscal fourth-quarter print on . The durable lane to be positioned for is enterprise and datacenter NAND, but treat it as provisional until a first-party source confirms it. Every enterprise SSD read this week traces to one research house. Micron's data-center NAND commentary is the first first-party test; softening or customer inventory builds would unwind the read for Micron, SanDisk, Kioxia and Samsung's enterprise lines alike. The 4Q eSSD contract settlements near are the second check: flat or below 3Q breaks it.
§
Before the first post-holiday CFM NAND weekly, around . Read channel NAND as a liquidation, not a dip, and don't blend it with enterprise strength. China traders are selling hoarded wafer stock and some prices are back at levels, which trips the pipeline's channel reversal indicator. Wafer prices below January with no restock after the holiday would extend it. Longsys still quotes tight supply upstream while the spot floor trades below it.
§
Before Taiwan distributors report September revenue, to 10. Treat server DDR5 as the one DRAM lane where supply and demand agree, and watch it for double orders. Fill rates of 30 to 50 percent invite duplicate ordering. A sequential revenue decline at WPG, WT or Supreme while contract quotes rise would mark the peak for SK hynix, Micron and Samsung server lines. Client DDR5, DDR4 and mobile memory sit at the price customers will pay; branded DDR4 is already correcting.