From the editor
tkal is a daily synthesis of the credit, demand, and capex cascades I've been running for myself. Receipts published weekly: every dated call gets graded, blindly, against what actually happened. The premise is that most market writing is unfalsifiable by design — vague enough to be re-narrated after the fact. This is the opposite. The conviction level is on the call. The horizon is on the call. The falsifier — the thing that would prove it wrong — is on the call. If the call misses, it's in the scorecard. If it hits, also in the scorecard. The newsletter is what the model saw this week; the scorecard is whether the model has been right. Not investment advice. Positions may exist in the names discussed.
The Read
The 2027 memory book is being written in hundred-billion-dollar contracts, and the first buyers have started refusing this quarter's price.
first refusals arrive while the 2027 book fills
Watch · the week in 3 minutes
01 · Signal
the 2027 book is being written in contracts
Three commitments landed inside one window. NVIDIA and SK Group signed a $500B-plus multi-year cloud and HBM commitment supporting 2GW-scale Vera Rubin from 2027. Samsung and Broadcom signed a $200B five-year MOU covering HBM, 2nm foundry and advanced packaging. Micron carries 16 strategic customer agreements running 2026 to 2030, about 20% of its DRAM and roughly a third of its NAND, against $22B-plus in prepayment. Underneath all of it sits $762.5B of Big Five capex for 2026, up 77% year over year, with about $450B of that directed at AI infrastructure.
Capacity contracted through 2030 stops responding to this quarter's price. That is the whole bull case, and its whole fragility.
02 · Signal
the first refusals arrive
DDR4 1Gx8 3200 spot printed $42.45 on , an all-time series high and roughly double where it sat in May. The shipments underneath it went the other way. Xiaomi's Q2 adjusted net fell 42.6% year over year on memory cost, with smartphone shipments down 26% at a record average selling price. OPPO and vivo then declined Samsung's Q3 LPDDR5X offer outright. That is the first contract refusal of this cycle, and refusals lead shipment cuts rather than follow them.
A record price set by brokers and refused by buyers is not a price. It is an inventory position.
03 · Signal
nand supply is being built on both sides
NAND runs tight on demand the pipeline reads as genuine, and this week the supply answer arrived from both geopolitical directions at once. Kioxia and SanDisk announced a third Kitakami fab, with Japanese government subsidies covering about a third of a multi-trillion-yen investment. YMTC filed a record RMB 33B STAR Market IPO, holds roughly 14% of Q2 global NAND share at about 200,000 wafers a month, and runs 267-layer Xtacking 4.0 in mass production at 78.7% gross margin. Washington also removed CXMT and YMTC from the Pentagon restricted list.
Today's tightness is real. The capacity that answers it is being poured in Iwate and Wuhan at the same time.
The Call · Credit Stress, Near Term
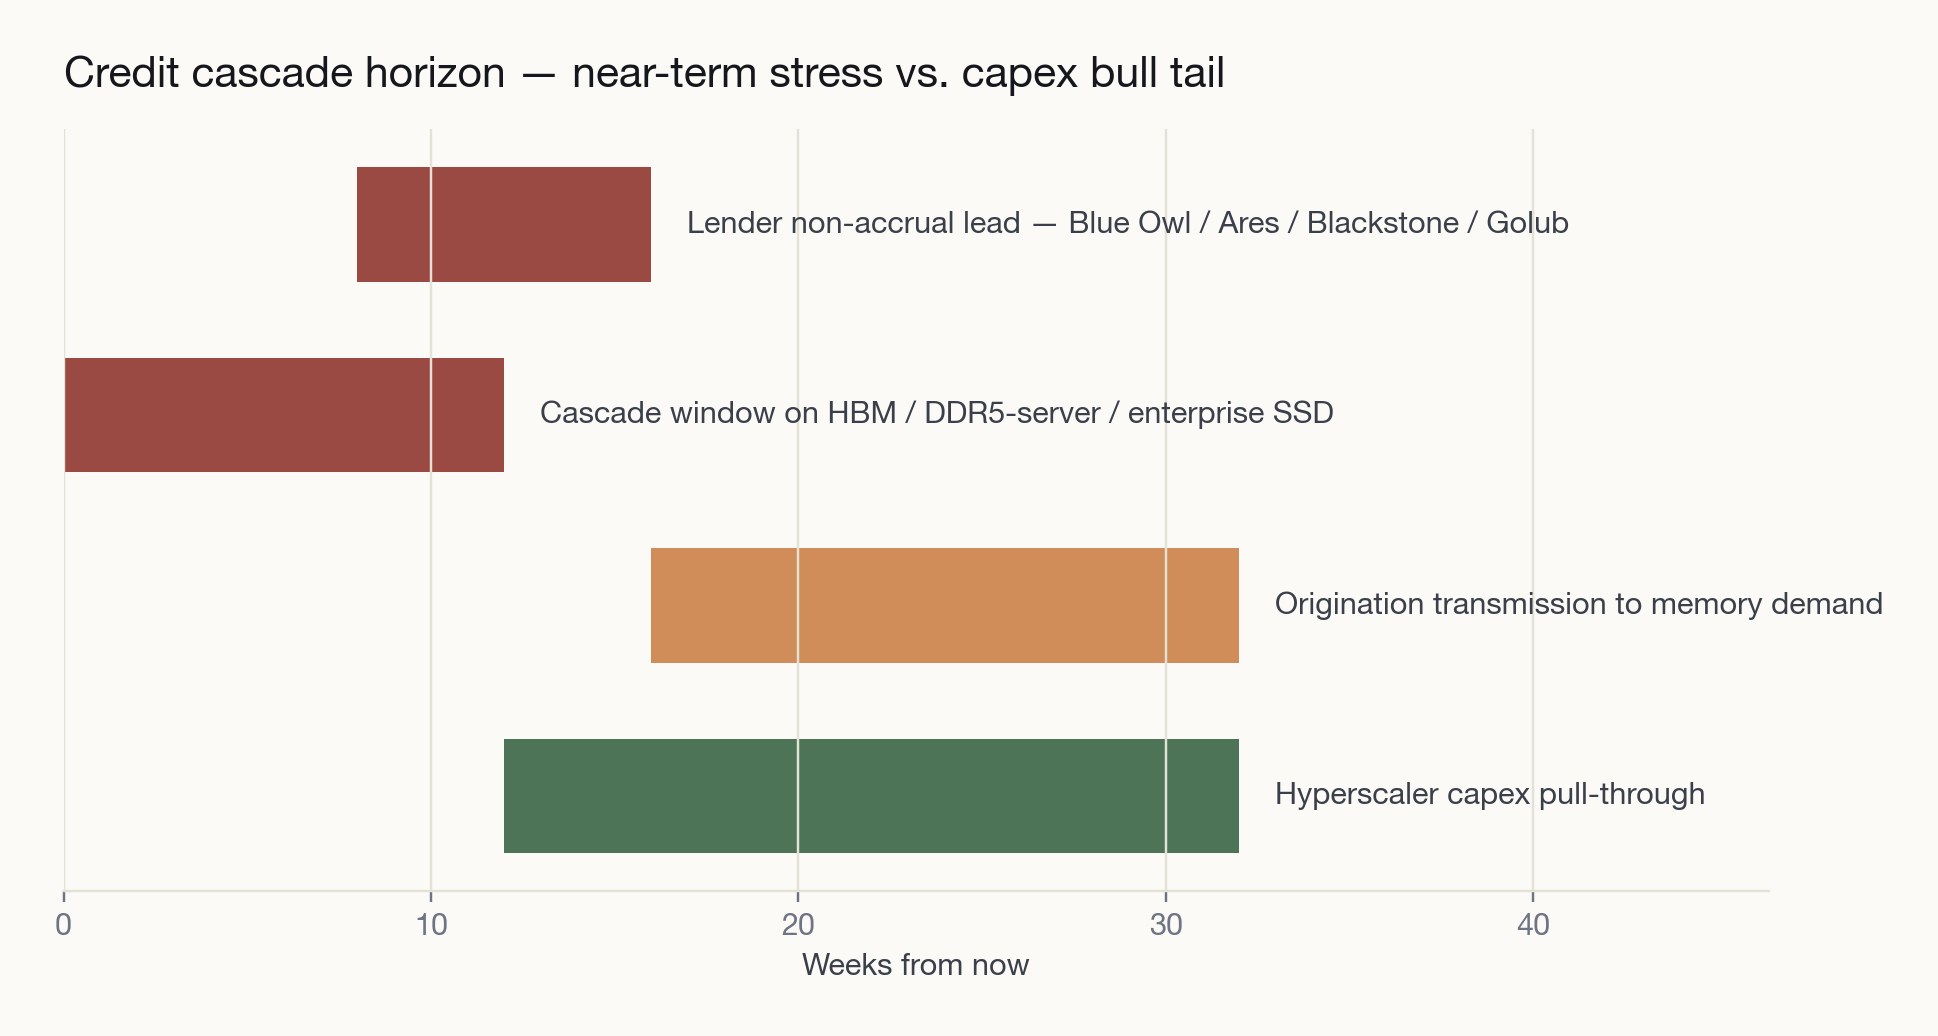
Four lenders sit in the non-accrual registry, Blue Owl, Ares, Blackstone and Golub, on a Q2 2026 default cohort that reached a five-year high of 2.8%. Blue Owl led the $2.4B IREN AI-factory financing on , which puts one balance sheet on both sides of the transmission, and the pipeline now reads the cascade horizon on HBM, server DDR5 and enterprise SSD at twelve weeks rather than the usual sixteen to thirty-two.
Before the Micron F4Q26 print. This is the single dated event that re-prices HBM, DRAM and NAND at the same time. The read to hold going in is that HBM and server DDR5 stay hard-allocated, not that every DRAM line does. The pipeline's two reversal triggers are both tied to this print, and fire on a flat-to-down HBM or NAND ASP guide for F27, or a revenue midpoint below $50B. Micron, SK hynix and Samsung carry this read.
§
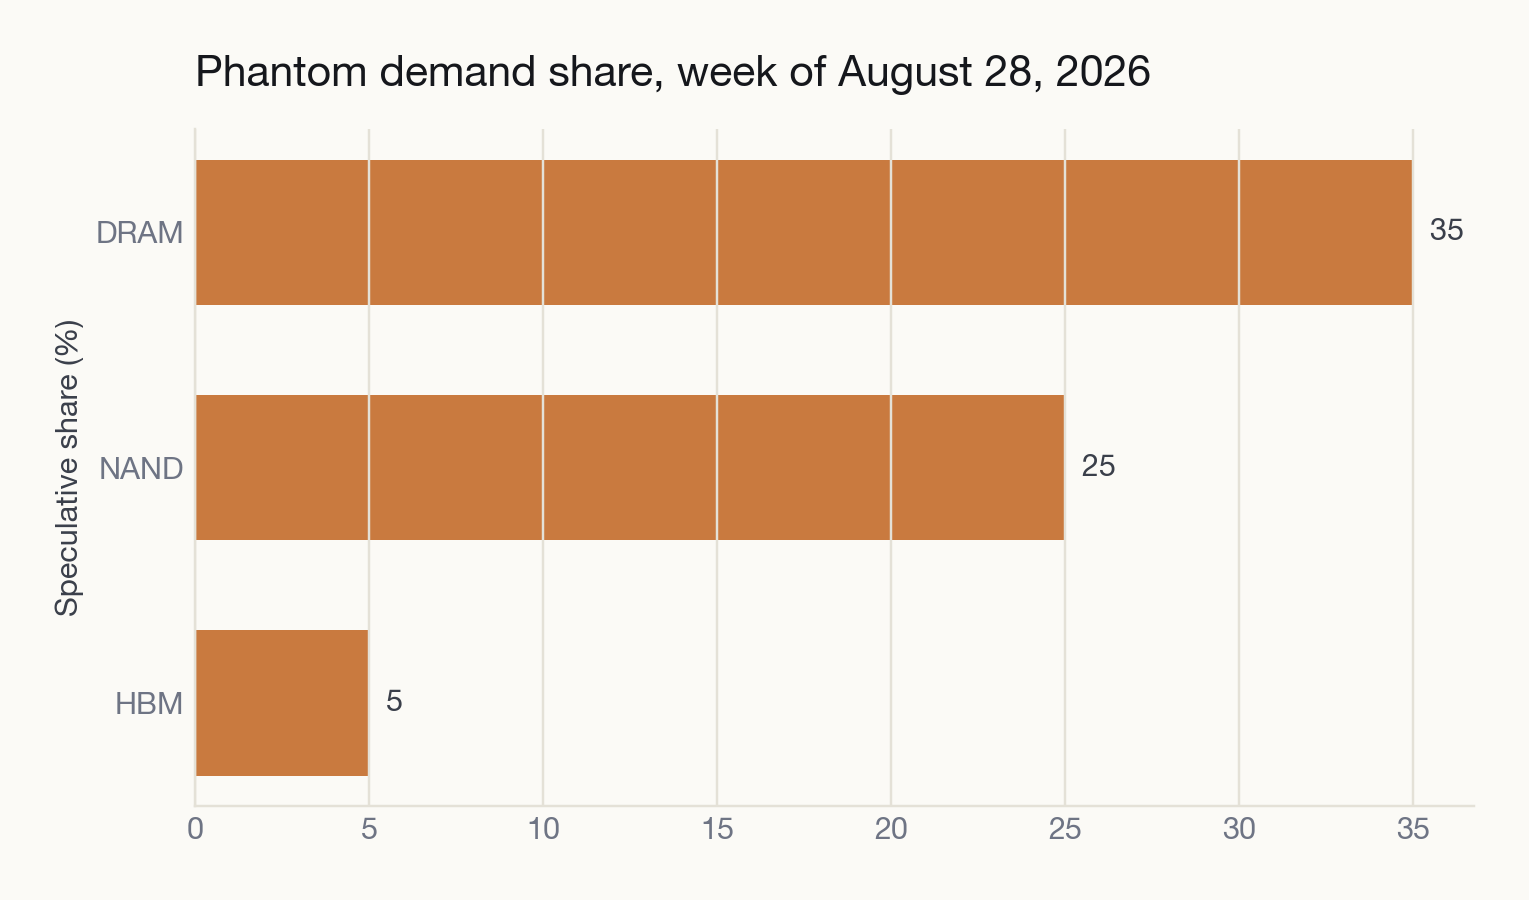
Now, on the commodity DDR4 client lane. A record spot and falling end shipments cannot both be demand. The commodity DDR4 lane reads as an inventory position held at the broker tier, not a supply story, until those two lines meet. DDR4 1Gx8 3200 printed $42.45 on against Xiaomi shipments down 26% and OPPO and vivo refusing Samsung's Q3 offer. The falsifier is spot below $38 for two consecutive weeks, or a second named tier-one OEM refusal. Samsung, SK hynix and Micron commodity lines carry this.
§
By the Blue Owl BDC filing. Credit is the one place this week's evidence cuts against the AI lane. What to watch is whether the non-accrual number stays an aggregate or acquires a borrower's name. AI datacenter buildout is credit-financed rather than balance-sheet-financed this cycle, which the pipeline scores as low structural durability. A named borrower moves HBM, server DDR5 and enterprise SSD demand from stressed to cascading. SK hynix, Micron, Samsung, Kioxia and SanDisk carry the downstream exposure.