From the editor
tkal is a daily synthesis of the credit, demand, and capex cascades I've been running for myself. Receipts published weekly: every dated call gets graded, blindly, against what actually happened. The premise is that most market writing is unfalsifiable by design — vague enough to be re-narrated after the fact. This is the opposite. The conviction level is on the call. The horizon is on the call. The falsifier — the thing that would prove it wrong — is on the call. If the call misses, it's in the scorecard. If it hits, also in the scorecard. The newsletter is what the model saw this week; the scorecard is whether the model has been right. Not investment advice. Positions may exist in the names discussed.
The Read
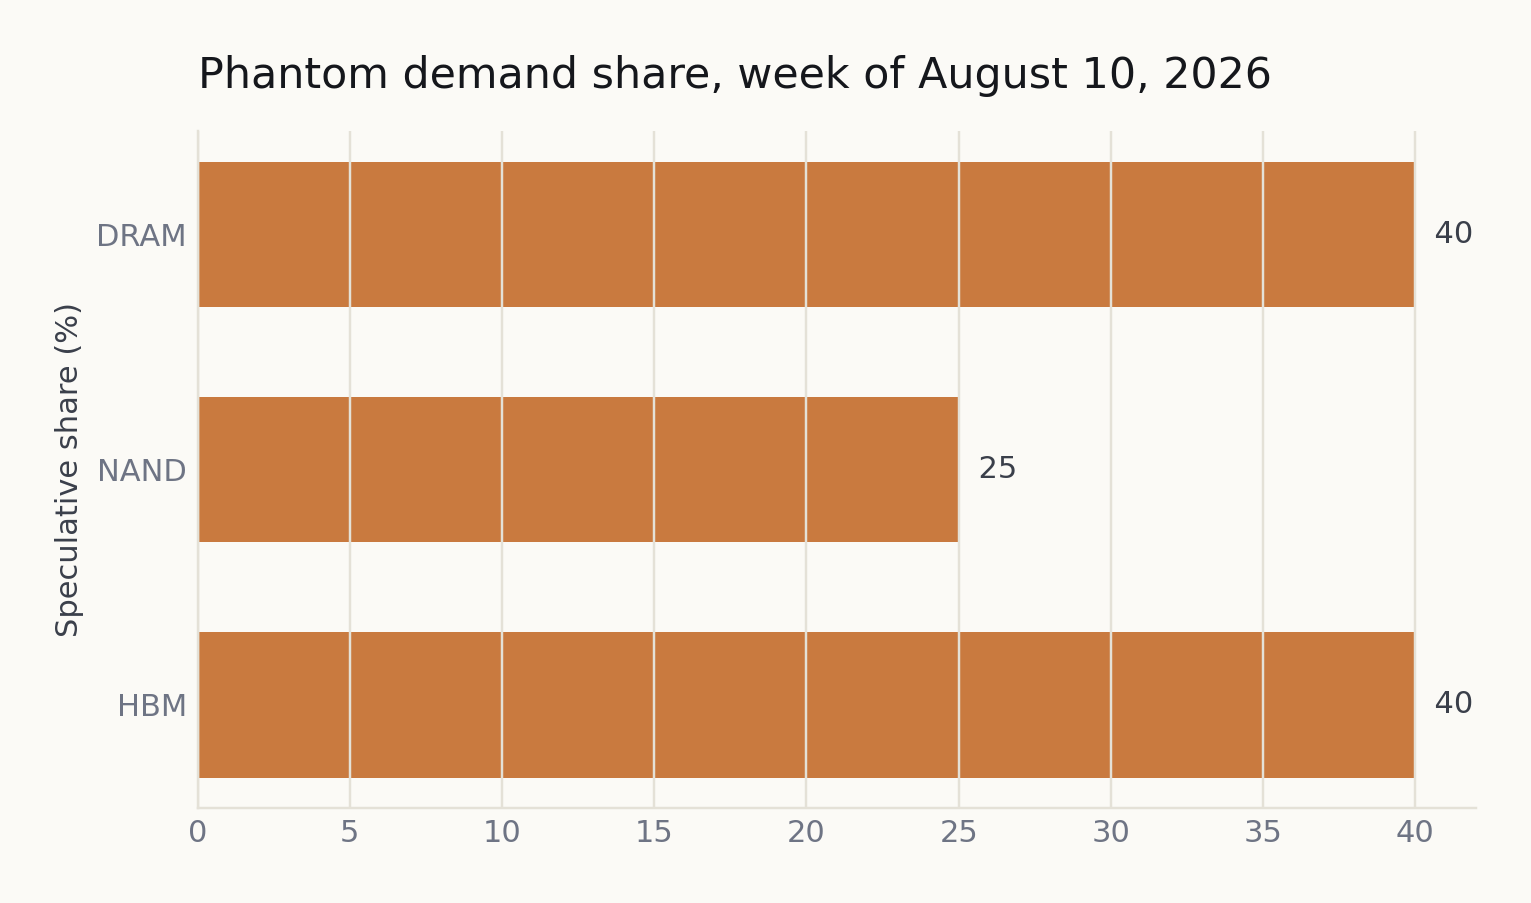
Supply tightened in every lane at once this week, but forty percent of the pull on HBM and server DDR5 is phantom, and the credit clock starts in twelve weeks.
tightening everywhere, verified in one lane
Watch · the week in 3 minutes
01 · Signal
the biggest hike of the cycle, with no price anchor
Samsung is guiding roughly +20% average QoQ on Q3 2026 DRAM, the largest single-quarter hike of this cycle, and SK hynix has scrapped price ceilings on long-term agreements outright. The 2027 book is already sold out across DRAM and HBM, with buyers receiving only 60 to 70 percent of requested allocation. The problem is verification: TrendForce's weekly memory pricing table has been silent for 44 days, which removes the primary triangulation anchor on that +20% number.
A hike this large with no independent print behind it is a claim, not yet a clearing price.
02 · Signal
hbm's supplier gap narrowed from both ends
Samsung's HBM4 yield reached roughly 80 percent, up from under 60 percent at February mass production, hitting its year-end target early. SK hynix still leads at 50 to 55 percent share, but the substitution gap that was locked in its favor has closed materially. TSMC is running 5.5x reticle CoWoS in volume above 98 to 99 percent yield and doubling capacity annually. Against that, a newly unified ~2,500-worker union across Icheon and Cheongju is a supply tail on the same product scope.
The scarcity that priced HBM was partly a yield story at one vendor. That part is thinning.
03 · Signal
consumer breaks while enterprise absorbs
Global PC shipments fell 4.9 percent YoY in Q2 to 68.2 million units, the first decline after nine straight quarters of growth. Smartphones fell 6.7 percent by IDC and 11 percent by Counterpoint, the weakest Q2 in thirteen years, with Xiaomi, OPPO and Vivo cutting 2026 targets by up to 30 percent. Enterprise SSD took 48 percent of Q2 NAND bits against 26 percent a year earlier, and SanDisk's NBM contracts now lock about half of FY27 bits.
Destruction on one side, contractual lock-up on the other. Blended memory strength hides both.
The Call · Phantom Fraction 20-40%
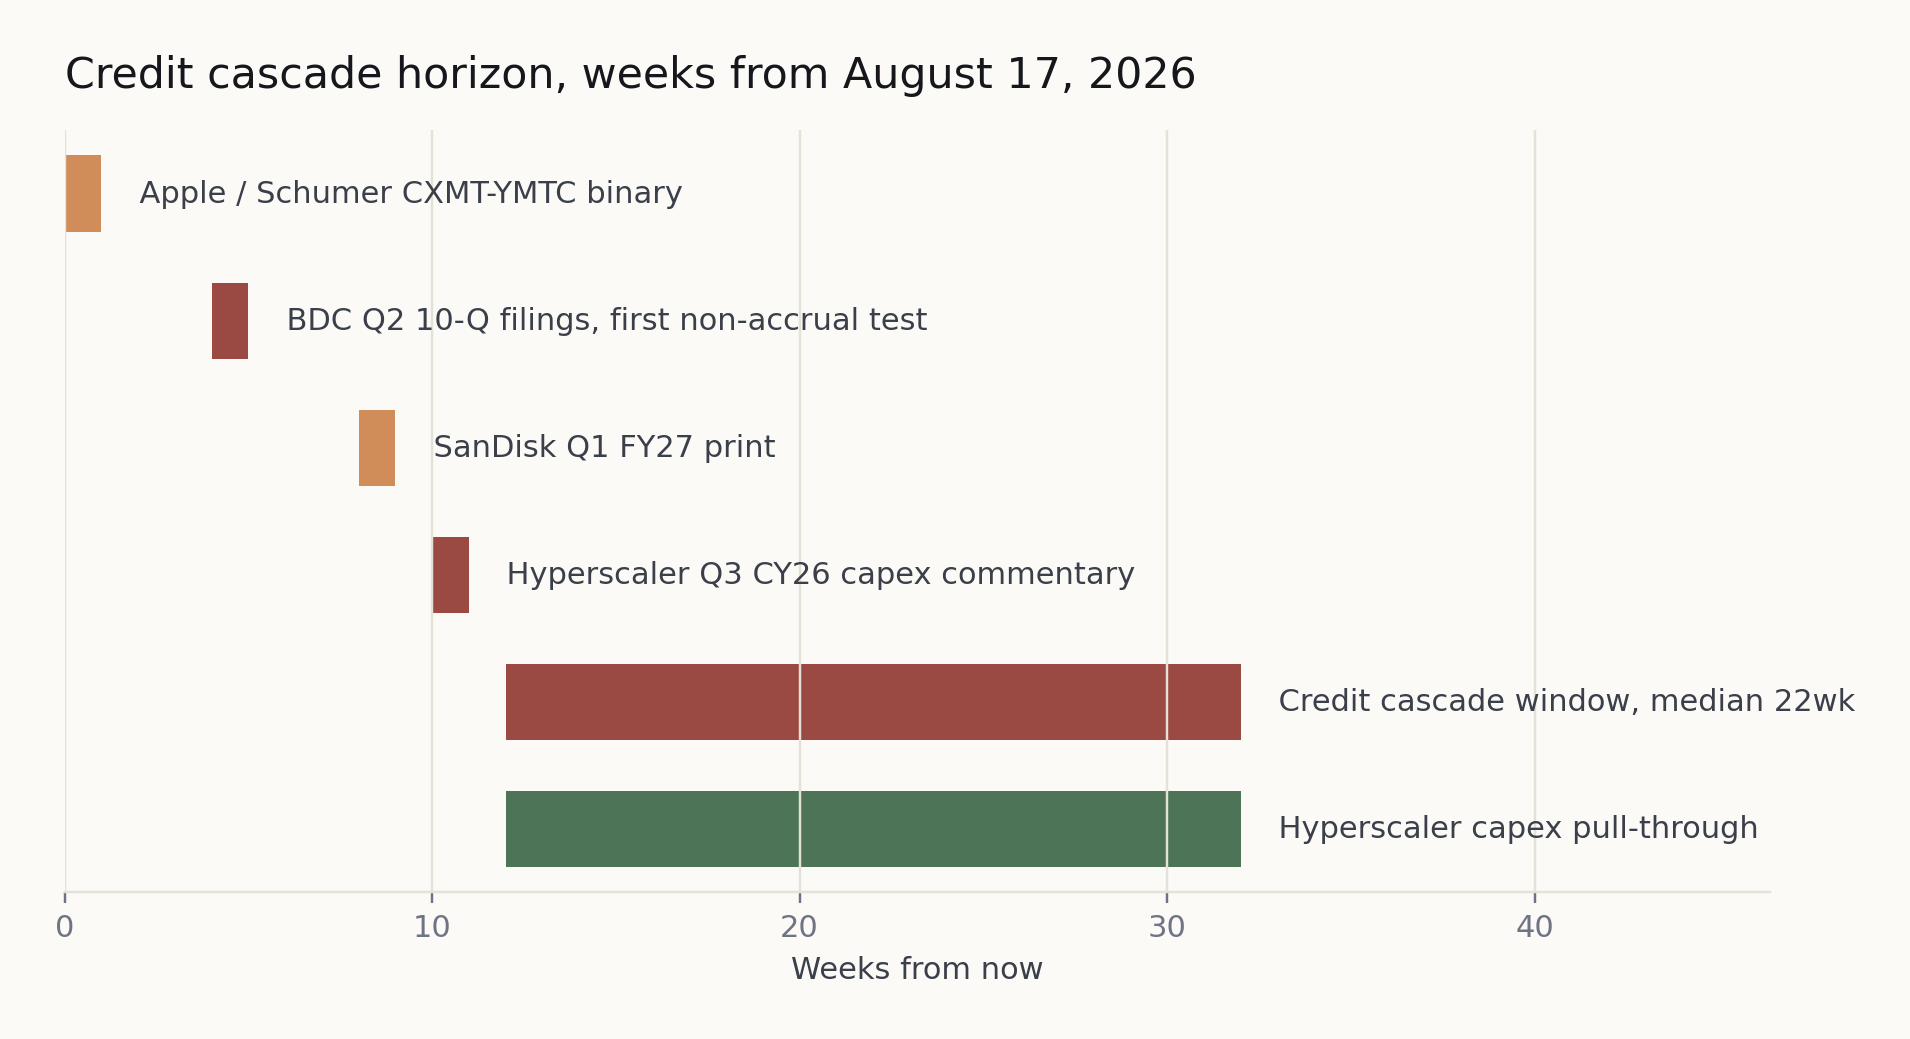
We read 20 to 40 percent of HBM and server DDR5 order pull as phantom, sourced from 2027 allocation acceptance and Foxconn pull-in language rather than committed builds. The falsifier is dated: Amazon, Meta, Microsoft and Alphabet Q3 CY26 capex commentary around . If that commentary echoes Alphabet's August sustainability pushback rather than reaffirming the plan, this deficit narrative is repricing, not extending.
Before the Apple response on CXMT and YMTC. Treat the China substitution story as confirmed rather than prospective, and stop reading blended DRAM strength as uniform across lanes. CXMT DRAM is now inside HP, Asus and Acer notebooks sold outside the US, the first Tier-1 OEM confirmation, and CXMT has filed a $4.2B Shanghai IPO with 10B RMB of 2026 equipment purchasing. The tracked-vendor China TAM is shrinking underneath Samsung, SK hynix and Micron even while their server lanes tighten. The binary swings LPDDR5X capture globally.
§
Through the SanDisk Q1 FY27 print. The durable NAND lane to watch is enterprise and datacenter, not the commodity tier, and the contract lock-up is the thing that carries it. SanDisk and Western Digital's NBM multiyear agreements cover roughly 50 percent of FY27 bits and two thirds of FY28 bits across eight customers with financial guarantees, though the floor terms are undisclosed. Enterprise SSD demand rides colocation credit with a 24-week lead and low stress sensitivity. Kioxia, Micron and Samsung sit on the same enterprise pull; the commodity tier does not.
§
Before the BDC Q2 10-Q filings. Credit is a structural headwind at a 12 to 32 week remove, not a current-quarter modifier. Watch the filings for the first AI-infrastructure non-accrual. Credit conditions turned STRESSED this week with a median lead-lag of 22 weeks, placing peak pull-through in Q1 to Q2 2027. Valor Equity, Apollo and Brookfield are each dragged by shared Nvidia GPU-collateral impairment exposure inside the $500B MOU cohort. A first BDC non-accrual or a GPU-SPE bond wide of guidance would flip the near-term flag and put 10 to 20 percent HBM compression 12 to 16 weeks out.