From the editor
tkal is a daily synthesis of the credit, demand, and capex cascades I've been running for myself. Receipts published weekly: every dated call gets graded, blindly, against what actually happened. The premise is that most market writing is unfalsifiable by design — vague enough to be re-narrated after the fact. This is the opposite. The conviction level is on the call. The horizon is on the call. The falsifier — the thing that would prove it wrong — is on the call. If the call misses, it's in the scorecard. If it hits, also in the scorecard. The newsletter is what the model saw this week; the scorecard is whether the model has been right. Not investment advice. Positions may exist in the names discussed.
The Read
sandisk printed an 84.6% datacenter margin the same week idc showed pcs down 4.9% and phones down as much as 11%. the two memory demand lanes are no longer converging.
ai lane absorbs, consumer lane cracks
Watch · the week in 3 minutes
01 · Signal
sandisk confirms the enterprise nand floor
sandisk's q4 fy26 print realized an 84.6% gross margin on $8.97b of revenue, with datacenter revenue up 437% year over year. that is a tier-0 confirmation of enterprise nand pricing power, not a forecast. arrow electronics echoed it, raising its q3 guide with explicit allocation on ddr5 and enterprise ssd. the demand under datacenter nand is real, and it is being rationed at the ask price.
the enterprise nand bid is a receipt now, not a thesis.
02 · Signal
hbm is sold out, and quieter than that sounds
hbm stays sold out through 2026 on roughly $725 to 800b of hyperscaler capex, up 77% year over year, with cowos packaging exhausted. power and site access, not memory, are the binding limit. but the supply-side tightening belief was cut to low conviction this week. the nvidia hbm anchor has gone silent for 45-plus days and the trendforce lane has stayed quiet with it. the demand read is loud, the confirming supply chatter is not.
sold out is the demand read. the supply lane going dark is the one to sit with.
03 · Signal
cxmt crosses into hp, asus and acer
cxmt dram is now shipping inside hp, asus and acer notebooks sold outside the us, the first tier-1 global pc oem volume ramp for chinese dram. it lands on top of hard consumer destruction. idc put q2 pcs down 4.9% and smartphones down 6.7%, with counterpoint at down 11%. substitution is moving from qualification to volume, and the market it substitutes into is shrinking underneath it.
the china substitution story stopped being a projection this week and became a shipment.
The Call · Apple / Schumer 8/21 binary
by august 21 apple answers the bipartisan schumer letter demanding it reject cxmt and ymtc memory. a hard commit preserves tracked-vendor lpddr5x capture at apple globally. silence or a soft answer re-prices the whole substitution math and hands the china suppliers the opening.
Into the TrendForce Q4 refresh on . the durable lane to be positioned toward is enterprise and datacenter nand, not the commodity consumer tier. sandisk and western digital carry the cleanest read on that pricing power. sandisk realized 84.6% gm with datacenter revenue +437% yoy; arrow raised its q3 guide with explicit ddr5 and essd allocation. micron and kioxia sit in the same density-mix tailwind, while samsung's 400+ layer qlc yield is the open question.
§
Before Apple's answer to the Schumer letter. treat cxmt and ymtc substitution as transitioning from projection to volume, not as a contained china-only story. it caps how much blended-dram strength should be read into sk hynix, micron and samsung consumer exposure. cxmt dram is now inside hp, asus and acer non-us notebooks; cxmt tracks ~350k wspm by year-end, near micron, with an hk ipo pending. idc q2 pcs -4.9% and smartphones -6.7% to -11% is the demand backdrop it lands into.
§
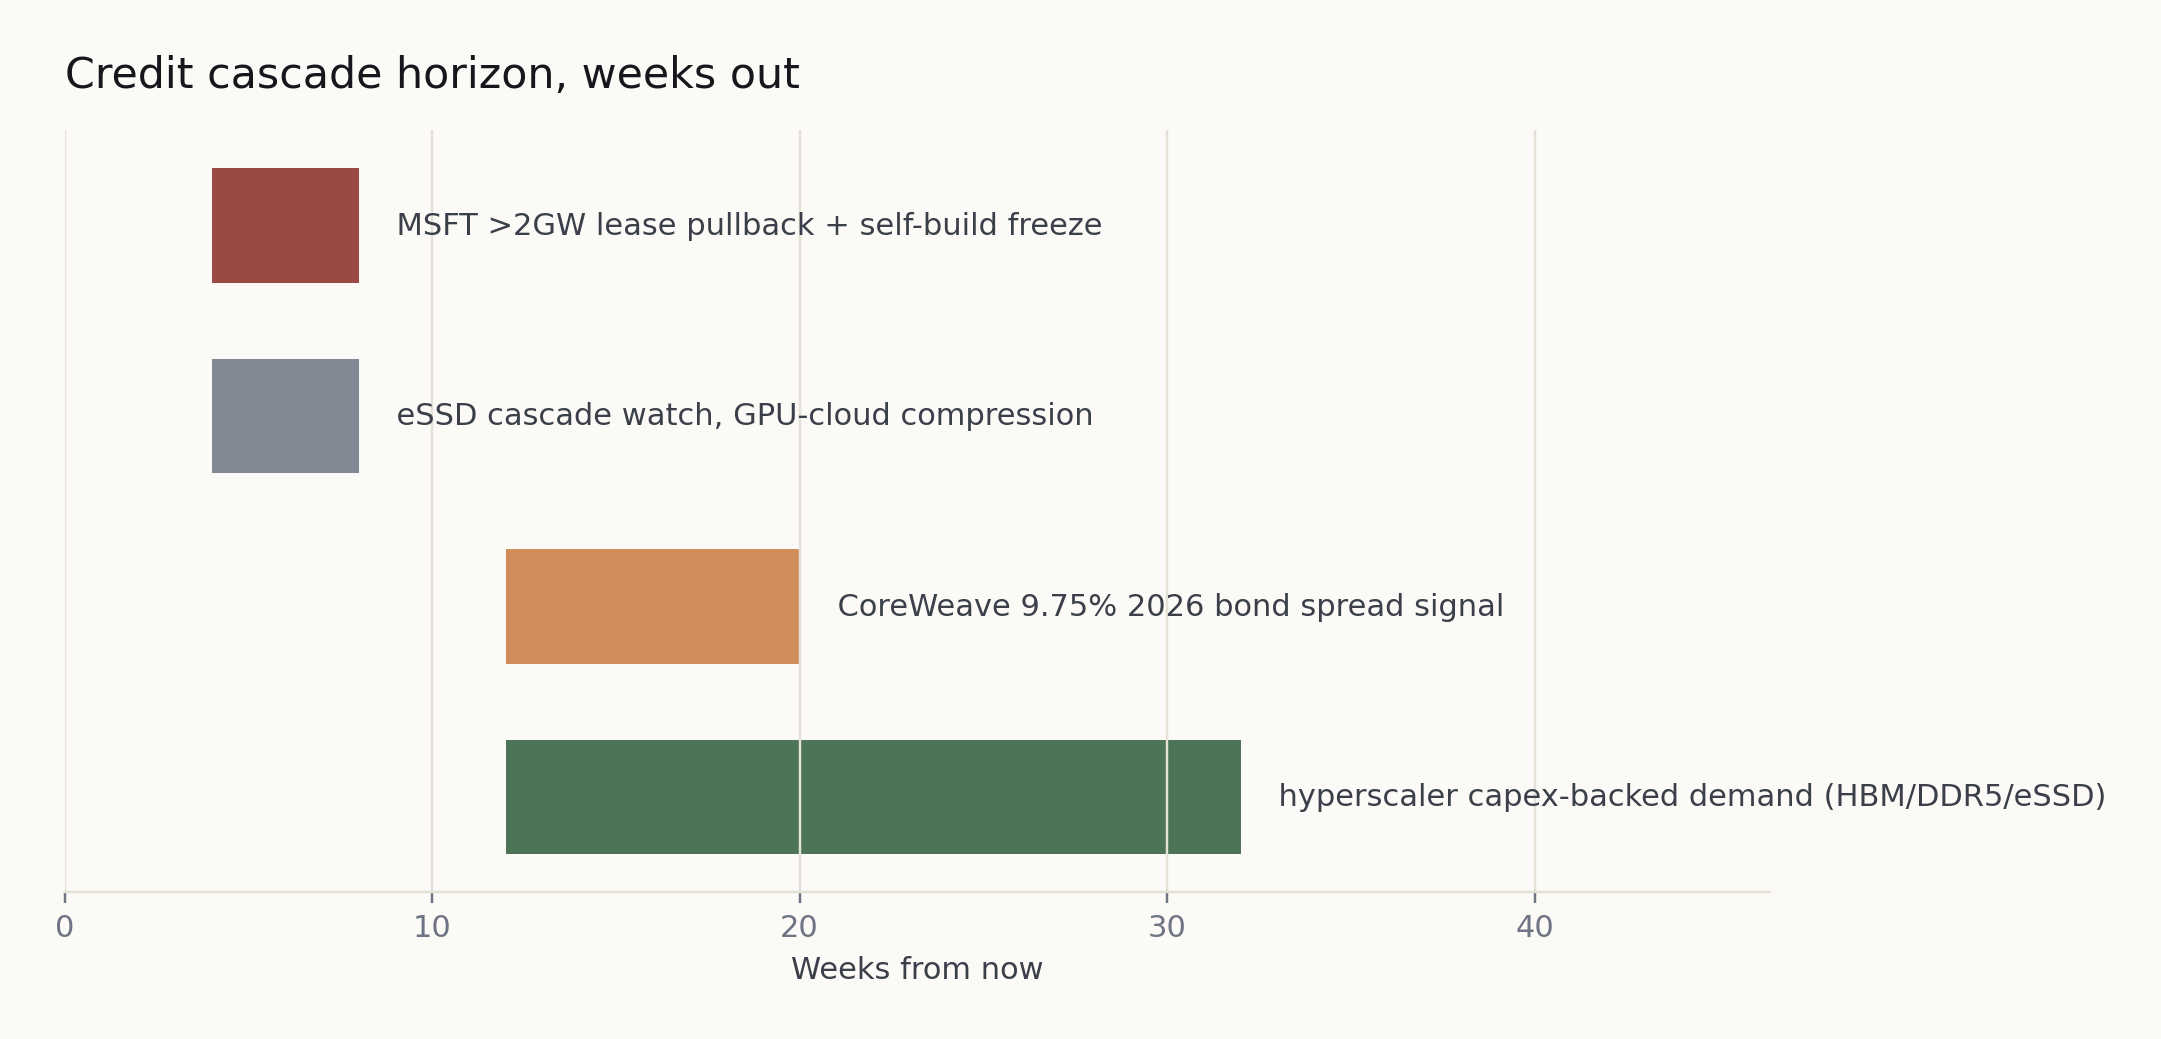
Through the Q2 BDC 10-Q window across August and September. hold the hbm demand story as durable but the near-term supply and credit confirmation as unconfirmed, not broken. the msft lease pullback and coreweave spread are the near-term overhangs on the same ddr5-server and essd lanes the capex thesis supports. hbm is sold out through 2026 on ~$725-800b capex, but nvidia's hbm anchor has been silent 45+ days. msft pulled >2gw of third-party leases and froze 1.5gw of self-build inside the 4-8 week credit window; coreweave's 9.75% 2026 bond sits inside 12-20 weeks.