From the editor
tkal is a daily synthesis of the credit, demand, and capex cascades I've been running for myself. Receipts published weekly: every dated call gets graded, blindly, against what actually happened. The premise is that most market writing is unfalsifiable by design — vague enough to be re-narrated after the fact. This is the opposite. The conviction level is on the call. The horizon is on the call. The falsifier — the thing that would prove it wrong — is on the call. If the call misses, it's in the scorecard. If it hits, also in the scorecard. The newsletter is what the model saw this week; the scorecard is whether the model has been right. Not investment advice. Positions may exist in the names discussed.
The Read
sk hynix locked its hbm4 output to nvidia for $500 billion in the same week that pc shipments fell 4.9% and a bdc lender went non-accrual, so the deficit and the cracks are now both hard data.
deficit deepens as consumer and credit crack
Watch · the week in 3 minutes
01 · Signal
the hbm oligopoly just got locked
sk group and nvidia formalized a $500 billion infrastructure loi that ties sk hynix hbm4 to the vera rubin platform, and amd's helios entered mass production with 31tb of samsung hbm4 per rack. sk hynix also filed to accelerate 7.1 trillion won of p&t7 back-end packaging for 2h27. three incumbents, two flagship draws, and no phantom signature on the hbm line.
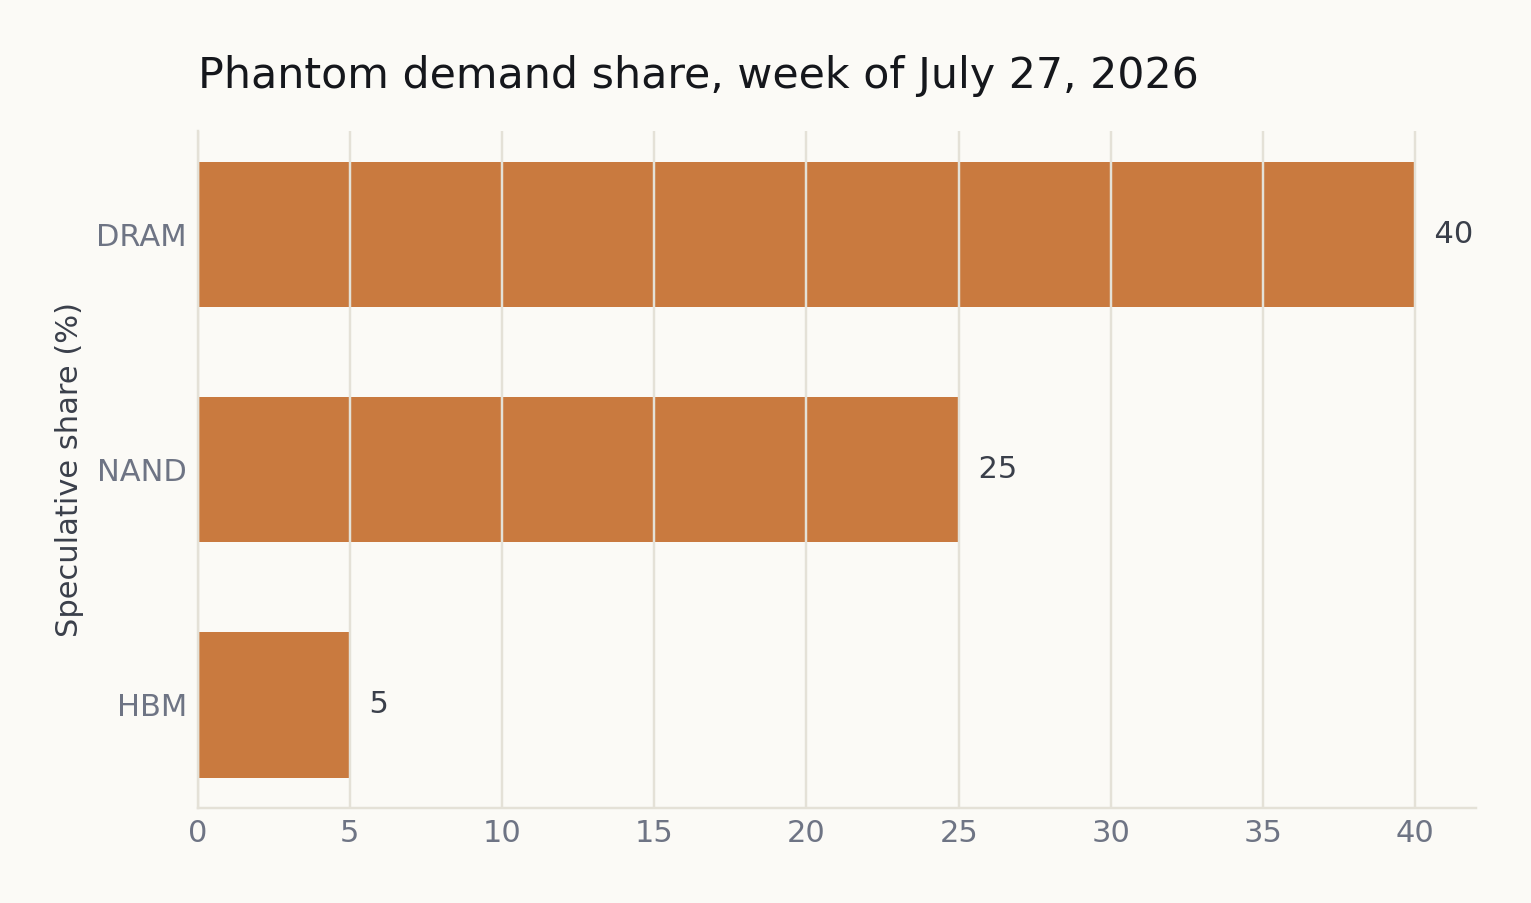
hbm phantom share sits at 5%. that is demand you can underwrite, not demand you have to discount.
02 · Signal
the consumer lane stopped being a forecast
idc put q2 pc shipments down 4.9% year over year to 68.2 million units, the first annual decline in nine quarters, and counterpoint logged the weakest q2 for smartphones in thirteen years at down 11%. published distributor pricing trackers still show uniform up direction across every sku, but the phantom fraction on client dram now runs near 40%. the split between server and client is no longer analytical. it is in the hard data.
client dram at 40% phantom is a channel telling a story the end units are not.
03 · Signal
credit moved from footnote to co-weight
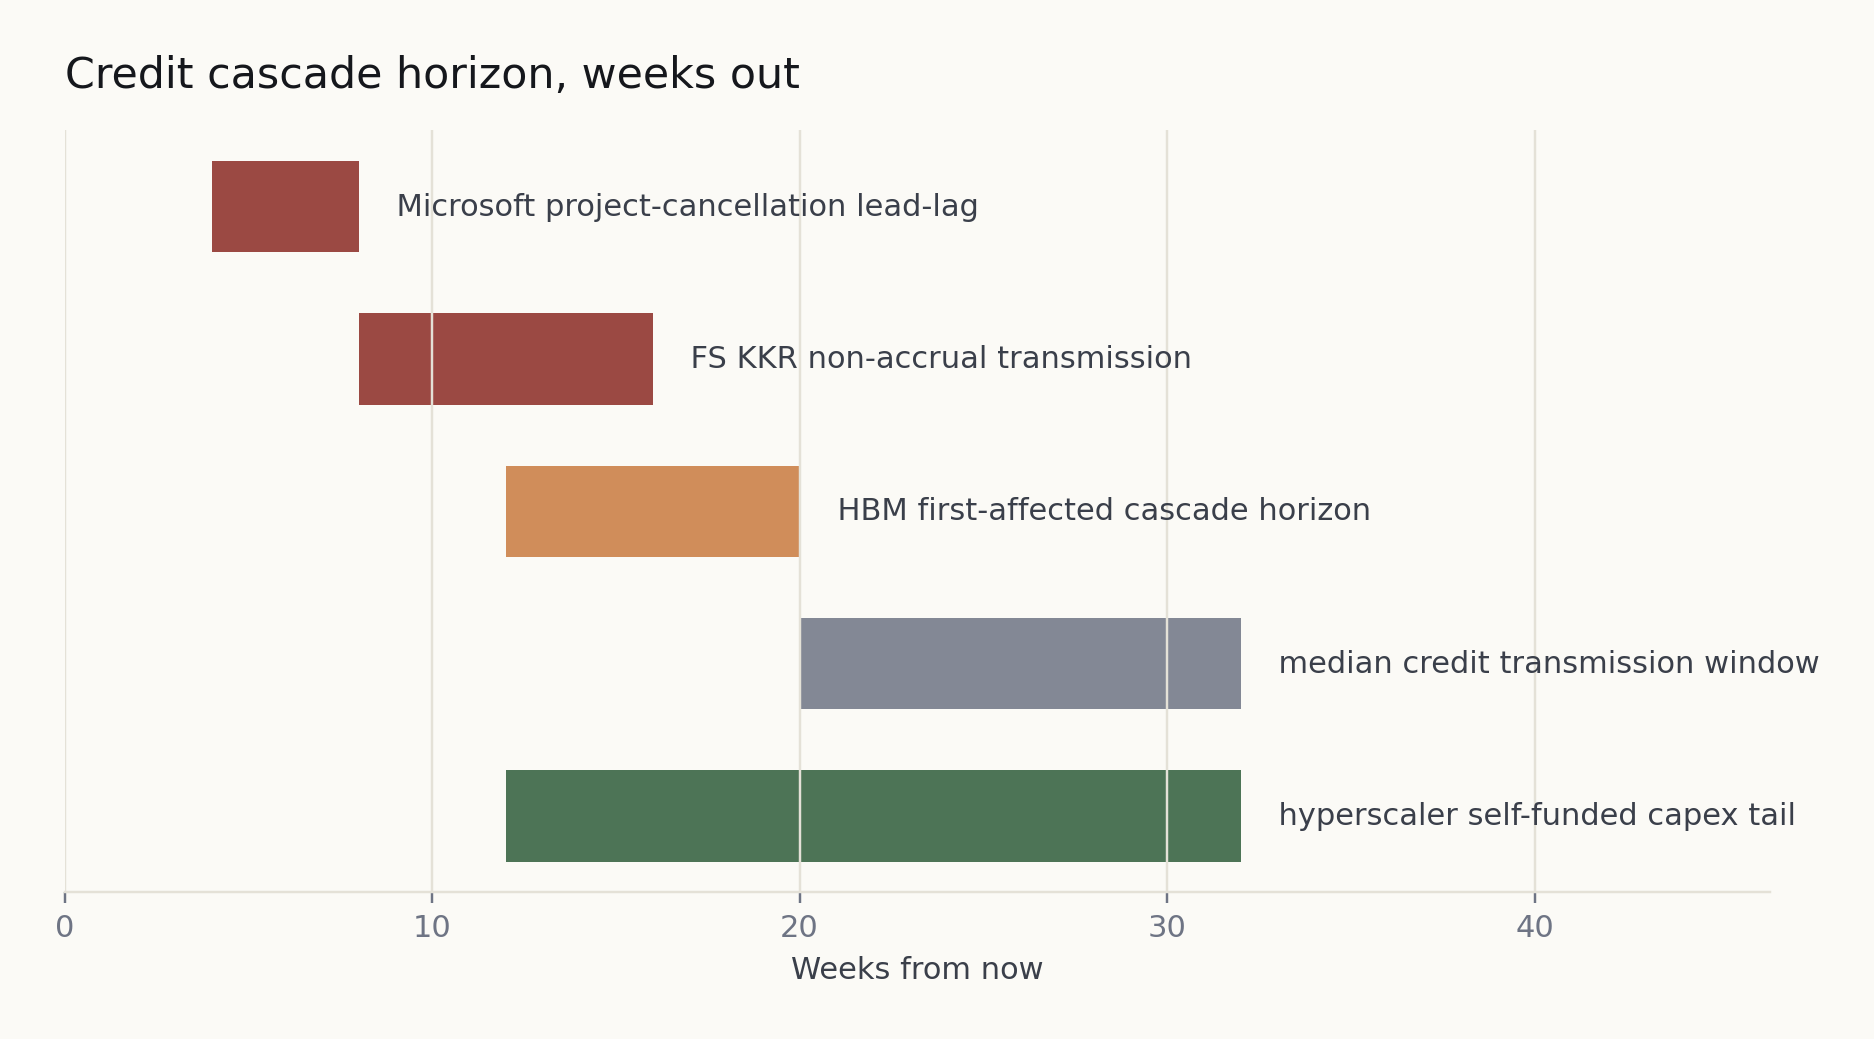
fs kkr capital confirmed a non-accrual at 4.2% inside a $5.7 billion bdc watchlist pool, and microsoft voided roughly 200 megawatts of leases plus a 1.5 gigawatt self-build. the credit horizon now carries a near-term flag for the first time, with a six-week cascade that names hbm as first-affected. the hyperscaler capex anchor is self-funded and sits outside the lender network, so the anchor holds. the gpu-cloud borrowers do not.
a non-accrual naming a specific gpu-cloud borrower is the line between structural lag and current-quarter stress.
The Call · Credit Stress HIGH
the credit near-term flag is true with a six-week cascade into hbm. a non-accrual naming a specific gpu-cloud borrower (coreweave, lambda, nebius, applied digital) before september 7 confirms the cascade. absent that, hyperscaler self-funded capex keeps the deficit intact.
Segment State · Week of
Phantom demand share — at-a-glanceSOURCE · tkal estimate from public shipment, pricing, inventory, earnings & channel data — excludes employer, customer, supplier & other nonpublic information
Segment
State
Tape
Phantom %
DRAM
Tightening
UP · Moderate
40%
NAND
Tightening
UP · Moderate
25%
HBM
Tight
UP · Strong
5%
What the evidence suggests
§
before sk hynix's q2 print on july 29. the evidence currently favors the hbm and high-end server lane, where demand is hyperscaler and sovereign self-funded rather than lender-financed. treat it as the anchor that holds even if the bdc layer keeps fraying. sk hynix hbm4 is locked to nvidia vera rubin, samsung hbm4 goes into amd helios, and micron is the third incumbent. the amd-samsung contract is still unsigned per lisa su, so a signed deal with disclosed volumes before end-3q26 is the confirming falsifier.
§
watch arrow electronics' book-to-bill on july 30. don't read blended dram strength as uniform. the server tier is real; the client tier is where the phantom sits. a book-to-bill under 1.0 on in-line revenue would confirm the channel is overstating end-demand by 20 to 40%. idc pc down 4.9% and counterpoint down 11% already mark the end-unit destruction. cxmt's $8 billion star market debut on july 28 funds ddr5 and lpddr5x substitution at xiaomi, huawei and lenovo, a longer-horizon drag on samsung, sk hynix and micron china tam at the low and mid tier.
§
through the maga capex prints, july 29 to 31. enterprise nand is the second underwritable lane. kioxia is sold out for 2026 and 30tb tlc has moved two to three times on the same sku. the evidence points to elevated datacenter nand, which reads separately from the credit-sensitive gpu-cloud segment. sk hynix nand up 330% yoy in the q2 preview, and kioxia allocation is the hardest concentration signal in the run. a wdc-kioxia merger (tier-2 chatter only) or a gpu-cloud non-accrual would each reset the nand read, in opposite directions.