From the editor
tkal is a daily synthesis of the credit, demand, and capex cascades I've been running for myself. Receipts published weekly: every dated call gets graded, blindly, against what actually happened. The premise is that most market writing is unfalsifiable by design — vague enough to be re-narrated after the fact. This is the opposite. The conviction level is on the call. The horizon is on the call. The falsifier — the thing that would prove it wrong — is on the call. If the call misses, it's in the scorecard. If it hits, also in the scorecard. The newsletter is what the model saw this week; the scorecard is whether the model has been right. Not investment advice. Positions may exist in the names discussed.
The Read
hyperscalers are signing uncapped multi-year memory contracts while published distributor data show commodity dram and nand demand that end customers are not actually placing.
price caps come off, hynix print looms
01 · Signal
the contract lane stops negotiating
sk hynix pulled the price caps off its long-term agreements this week and extended csp contracts to three-to-five years. micron is sold out of hbm through 2026 with 2027 largely spoken for. the hbm4 ramp slipped a quarter to q3 and tsmc's cowos packaging is still the binding constraint. hyperscalers are accepting uncapped multi-year terms, which is not how buyers behave when they expect prices to fall.
uncapped multi-year contracts are a willingness-to-pay signal you cannot fake.
02 · Signal
published channel data show demand that isn't there
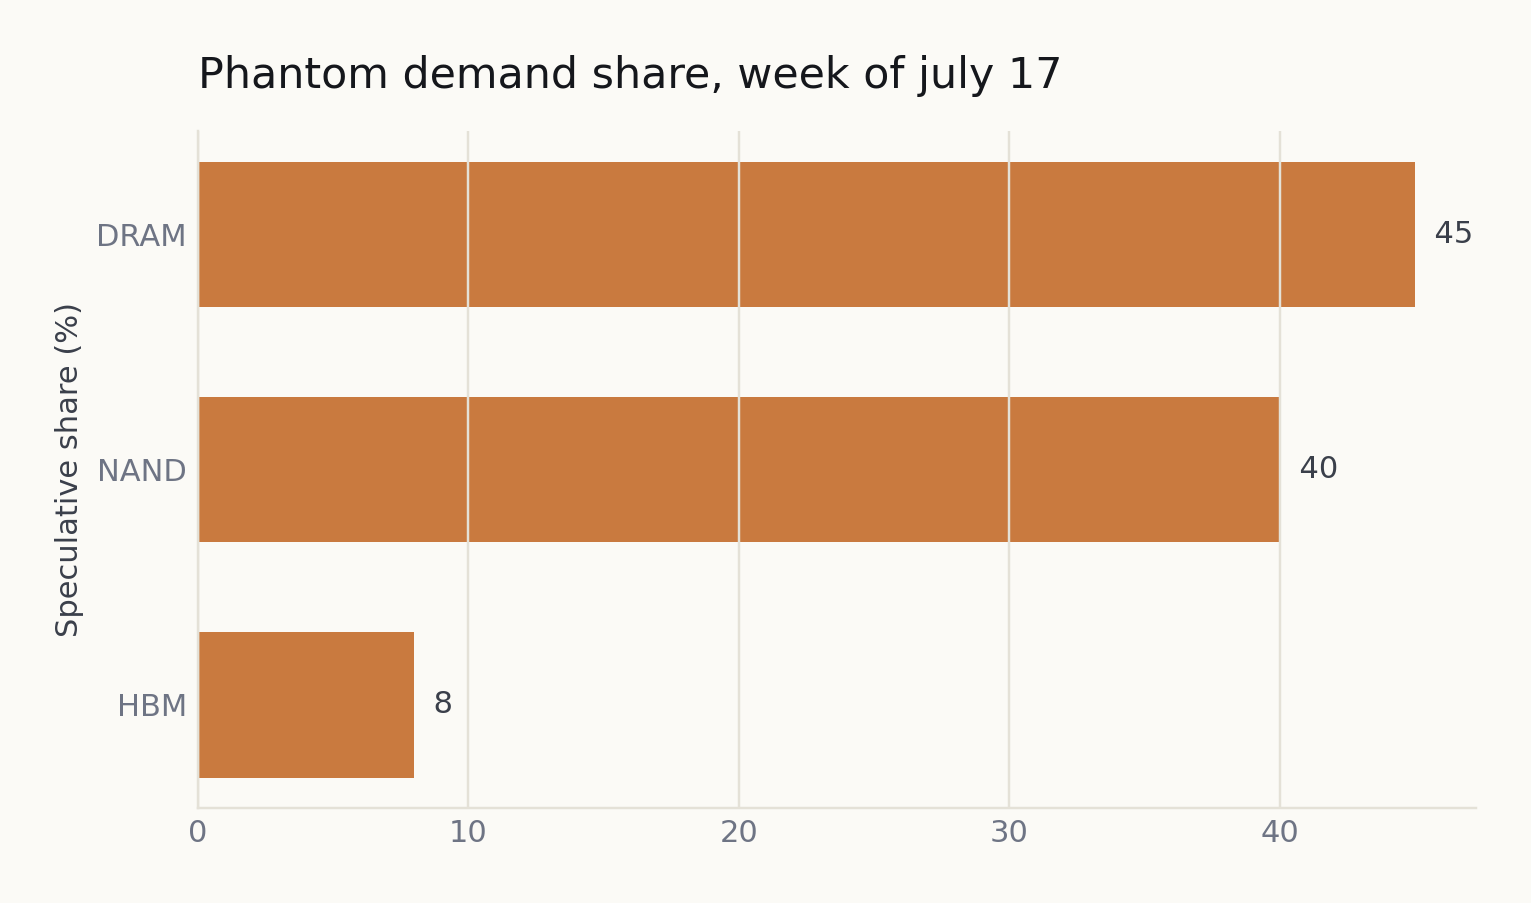
franchise distributors posted loud quarters. td synnex billings ran +33% and arrow +39%. those are asp-inflated figures, not unit demand. the anchor underneath is counterpoint's q2 smartphone read: down 11% year over year, the worst second quarter since 2013. published commodity ddr and nand channel data are running near 45% phantom, meaning close to half the apparent demand is positioning rather than end consumption.
when the distributor beats and the end market falls 11%, the beat is inventory, not demand.
03 · Signal
the credit clock starts in september
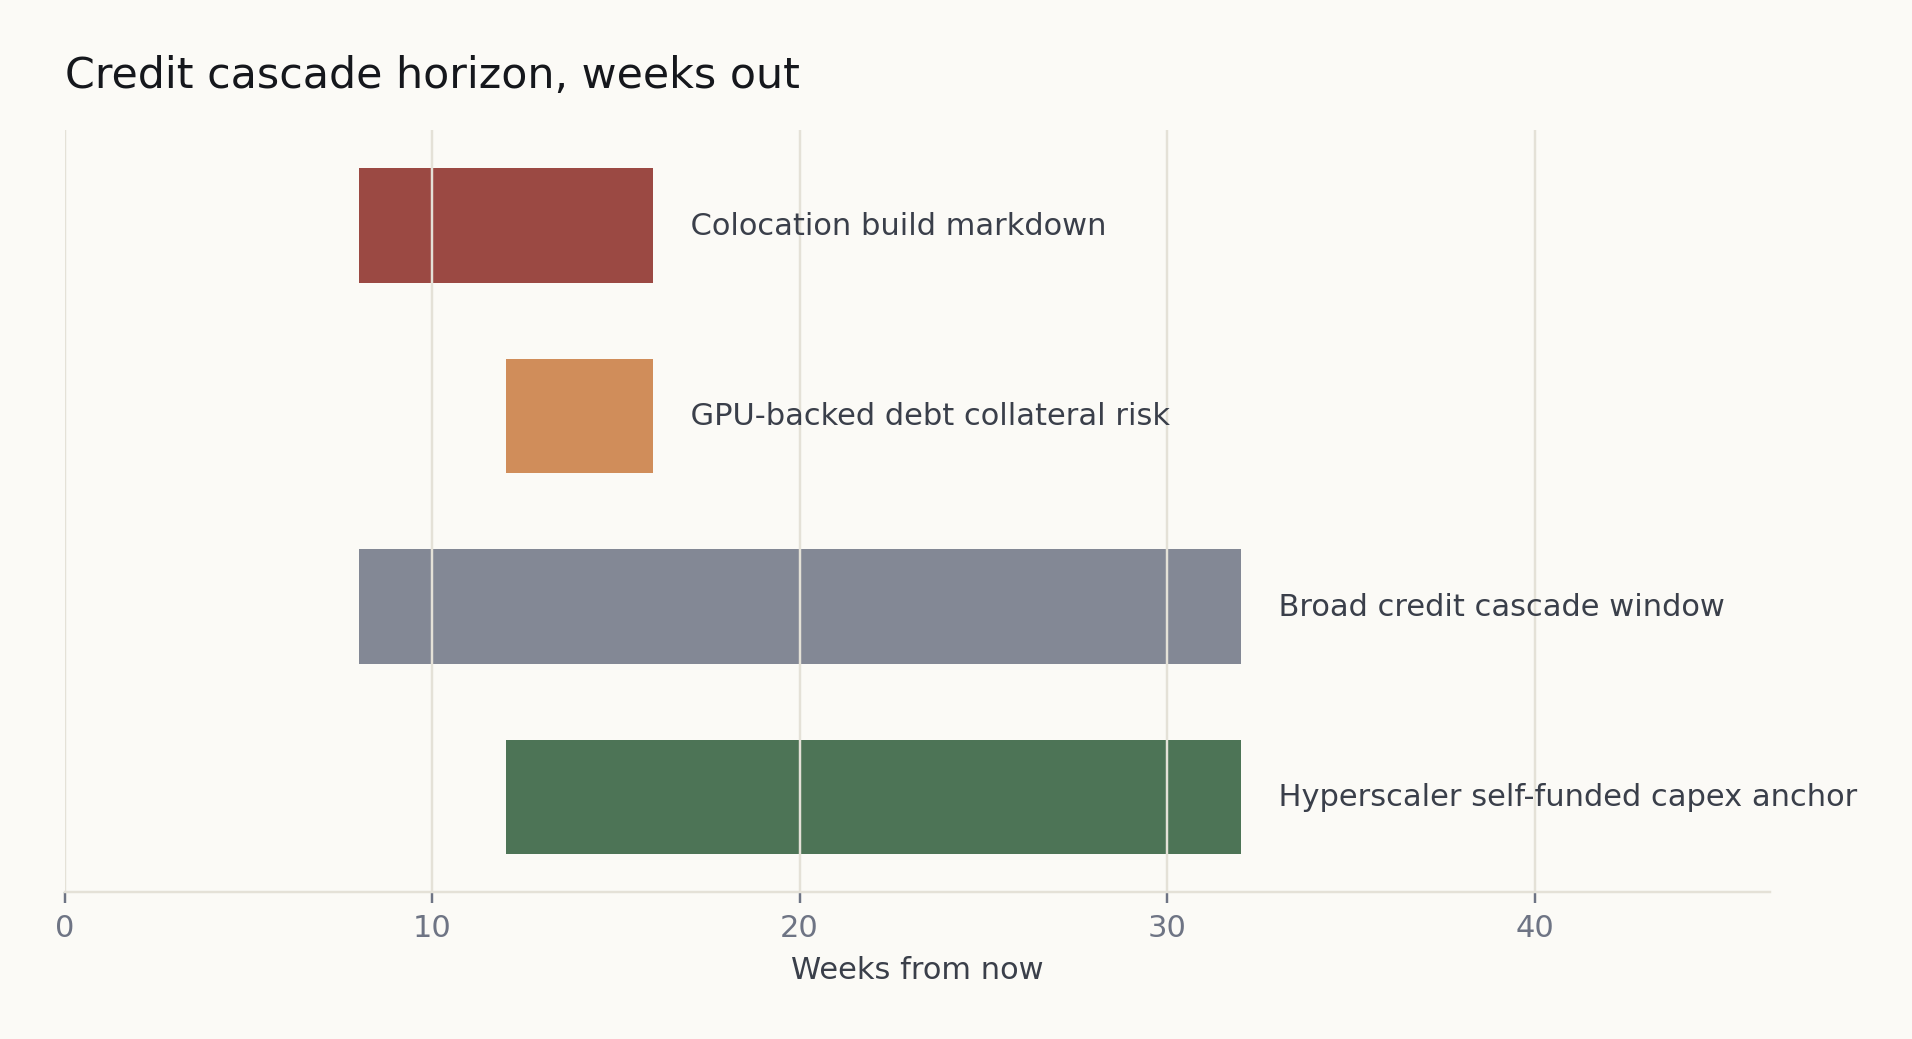
the credit pipeline reads stressed with the near-term flag active. semianalysis now puts 30 to 50% of 2026 us datacenter capacity as delayed or canceled, an 8-to-16 week lead that lands the first pinch in the september-to-november window. hyperscaler self-funded capex, roughly 725 billion for 2026, stays the durable anchor for hbm and enterprise ssd. the credit-financed layer, colocation and gpu cloud, is where any pullback shows first.
the anchor holds on cash flow; the commodity lanes ride on credit that is tightening.
The Call · Hynix Q2,
sk hynix reports q2 on july 22 with three memory triggers forming: hbm4 timing, non-hbm dram asp, and nand asp. a hbm4 reset back to q2 or dram guidance below +13 to 18% would break the tightness read; confirmation escalates it.
Segment State · Week of
Phantom demand share — at-a-glanceSOURCE · tkal estimate from public shipment, pricing, inventory, earnings & channel data — excludes employer, customer, supplier & other nonpublic information
Segment
State
Tape
Phantom %
DRAM
Tightening
UP · Moderate
45%
NAND
Tightening
UP · Moderate
40%
HBM
Tight
UP · Strong
8%
What the evidence suggests
§
Before sk hynix's july 22 q2 print. the durable position remains long the ai contract lane, not the commodity tier. hbm and server ddr5 are anchored by hyperscaler cash flow, not credit. sk hynix, micron and samsung carry the tightness; the falsifier is a hbm4 timing reset to q2 or dram asp guidance below +13 to 18% qoq on tuesday's print.
§
Into the september-to-november credit window. treat commodity ddr and nand as the credit-sensitive lane, and do not read distributor strength as end demand. td synnex +33% and arrow +39% are asp-inflated against counterpoint mobile down 11%; a new non-accrual on a colocation or gpu-cloud lender is the trigger to watch.
§
As samsung and cxmt redraw the supply map. the sk hynix hbm monopoly is narrowing, not broken; the china dram tail is a long-run asp risk, not a near-term one. samsung won the amd mi455x hbm4 socket, its first meaningful hbm4 win; cxmt closed a $4.1b ipo at roughly 8% dram share with hp and dell qualifying ddr5. watch for a public oem cxmt disclosure.