From the editor
tkal is a daily synthesis of the credit, demand, and capex cascades I've been running for myself. Receipts published weekly: every dated call gets graded, blindly, against what actually happened. The premise is that most market writing is unfalsifiable by design — vague enough to be re-narrated after the fact. This is the opposite. The conviction level is on the call. The horizon is on the call. The falsifier — the thing that would prove it wrong — is on the call. If the call misses, it's in the scorecard. If it hits, also in the scorecard. The newsletter is what the model saw this week; the scorecard is whether the model has been right. Not investment advice. Positions may exist in the names discussed.
The Read
korea customs confirmed the ai pull is real, with semi exports up 199.5% year over year, even as a fifth of commodity dram demand turns phantom and one lender flags its first non-accrual.
real pull, phantom noise, first credit flag
01 · Signal
the ai pull cleared the customs layer
korea's june semiconductor exports hit $44.82B, up 199.5% year over year, with HBM at $12.68B (+171%) and NAND +388%. that is the customs layer, the cleanest downstream read available, and it says the pull is shipping, not just quoted. micron's FQ3 print shows HBM3E and HBM4 sold out through CY2027 with demand running into 2028. enterprise SSD ran +86% quarter over quarter in Q1 as makers reallocate supply from client to server AI storage.
when the customs office and the sold-out book agree, the pull is real. everything else this week is noise around that one signal.
02 · Signal
a fifth of commodity dram is now phantom
L8B puts a 20-40% phantom fraction on commodity DDR5, DDR4, and LPDDR5, driven by taiwan distributor 1:1 motherboard-memory bundling, sourceability double-ordering, and huaqiangbei bid-surge. those are classic late-upcycle behavioral tells. samsung is reportedly negotiating a 20% quarter-over-quarter dram ask into 3Q26, and trendforce forecasts conventional dram up 13-18%. but the weekly settlement sheet has now been silent six weeks, so the price signal rests on forecast, not print.
the same ddr5 label carries two demand curves now. the phantom one reverses first, and the settlement sheet is the tell.
03 · Signal
one lender flagged the first crack
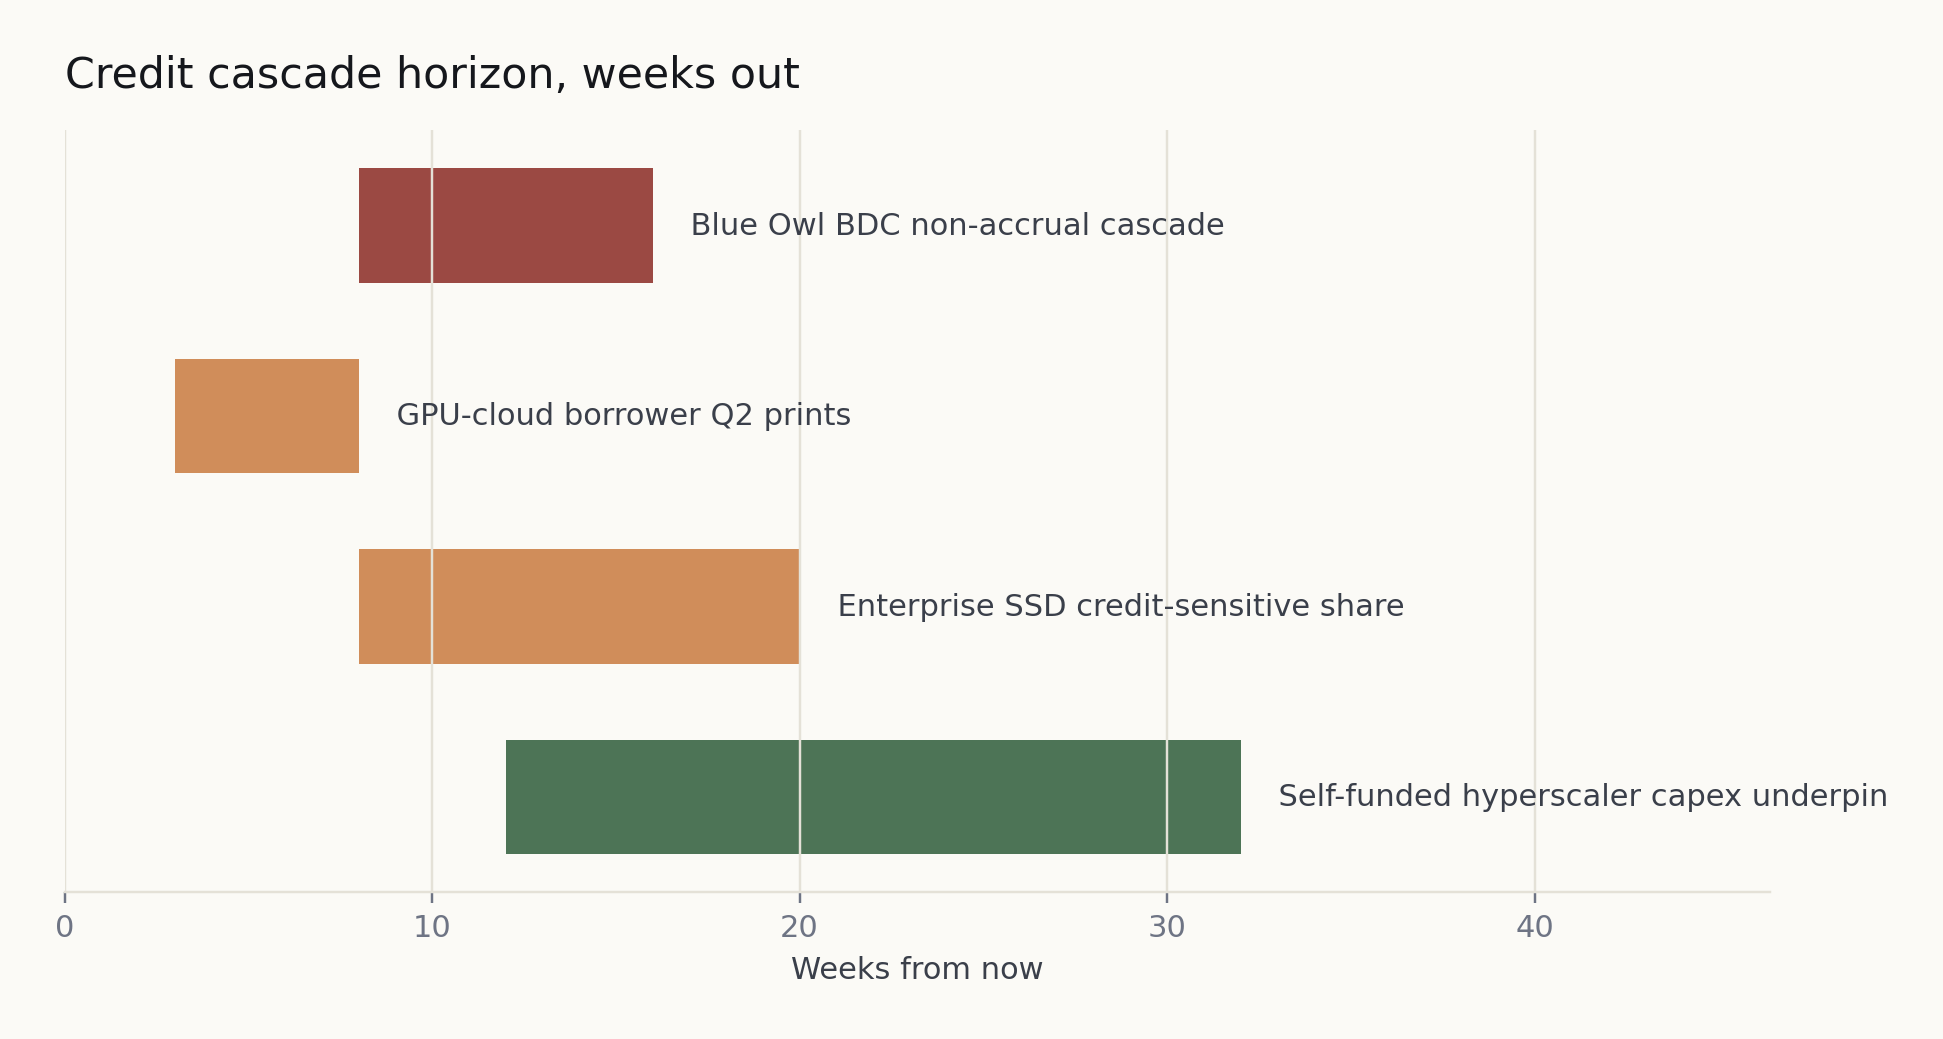
the credit pipeline stays stressed with stable financing direction: roughly 85% of AI infrastructure demand is structural and self-funded, 15% credit-sensitive. private-credit majors keep anchoring meta's $48B hyperion, oracle michigan, and KKR helix. the near-term wrinkle is blue owl capital, whose BDC tech vehicle flagged non-accrual despite a 0.6% headline rate, alongside $14B in redemption requests, 40.7% of Q1 shares. that places 8-16 week cascade risk on enterprise SSD.
structurally bullish through 2q27, but the first non-accrual has a date attached. blue owl's q2 10-q lands late july.
The Call · Blue Owl 10-Q, Late July
blue owl's Q2 2026 10-Q lands around july 31; a second non-accrual, or a redemption honor rate under 30%, opens an 8-12 week cascade to enterprise SSD and server DDR5. until then it stays a near-term flag, not an active alert.
Segment State · Week of
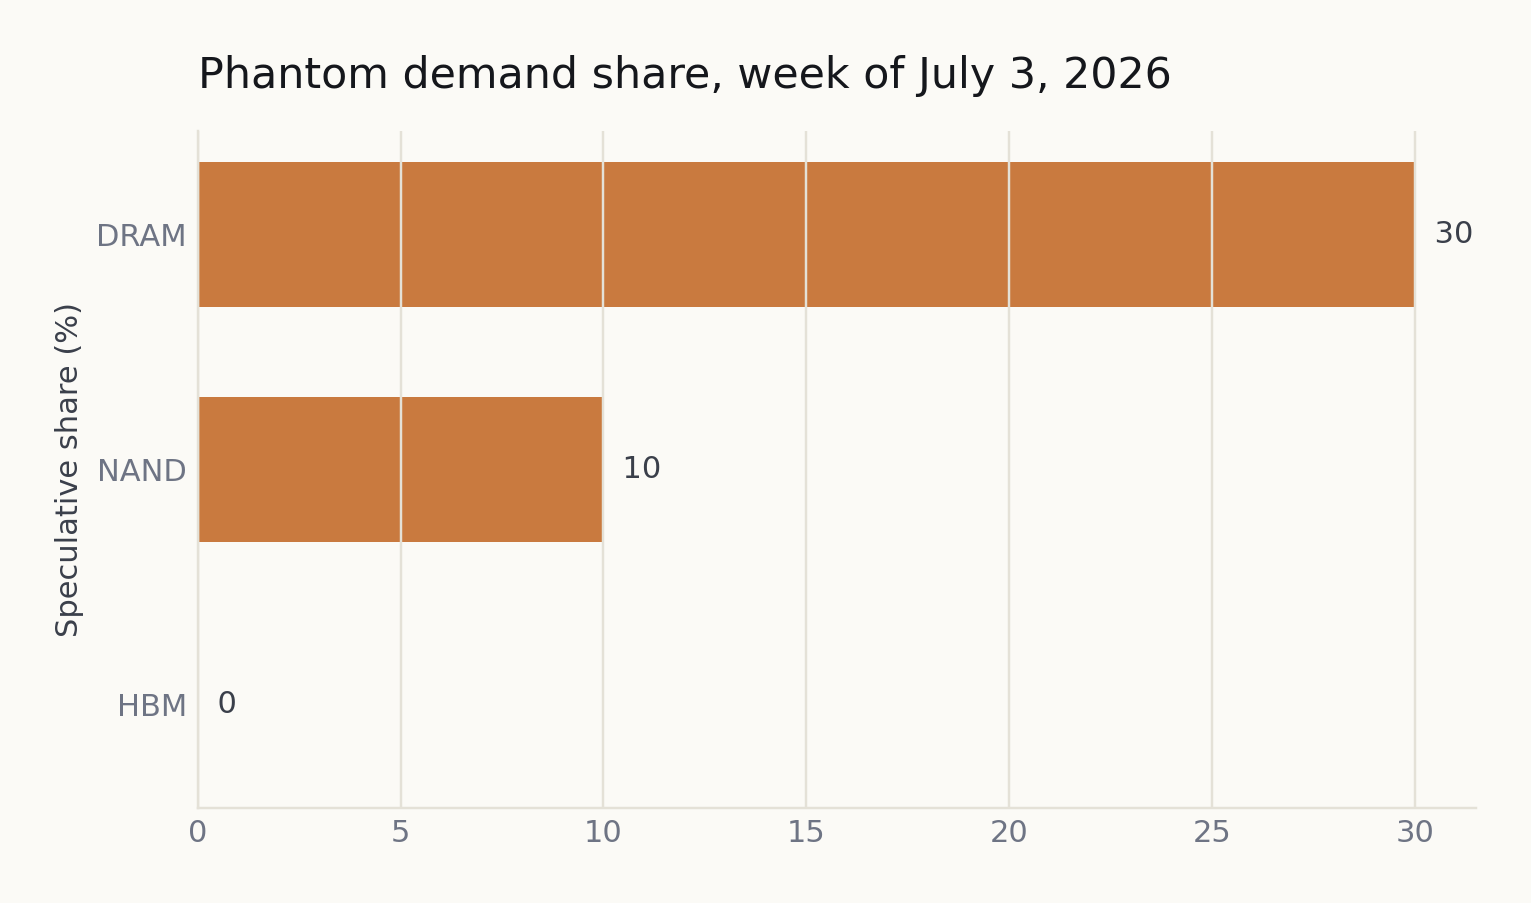
Phantom demand share — at-a-glanceSOURCE · tkal estimate from public shipment, pricing, inventory, earnings & channel data — excludes employer, customer, supplier & other nonpublic information
Segment
State
Tape
Phantom %
DRAM
Tightening
UP · Moderate
30%
NAND
Tight
UP · Strong
10%
HBM
Tight
UP · Strong
0%
What the evidence suggests
§
Before the hyperscaler capex guides. the evidence currently favors server DDR5 and HBM, where demand is committed capex, not channel fill. micron, SK hynix, and samsung sit on the supply side of a book that is already sold out into 2027. micron HBM3E/HBM4 sold out through CY2027; ~$710B self-funded US hyperscaler capex underpins the pull. falsifier: any capex guide cut at MSFT, GOOGL, AMZN, or META on july 28 reframes HBM acceleration as a 1H26 peak.
§
Watch the overdue TrendForce settlement sheet, expected around . don't read blended dram strength as uniform. the commodity and client tier carries a 20-40% phantom fraction, and its price signal rests on forecast while the weekly settlement print has been silent six weeks. samsung's 20% ask and trendforce's +13-18% forecast anchor the bull case; counterpoint smartphone shipments -13.9% year over year anchor the bear. falsifier: a soft or absent settlement print, or a foxconn july revenue print below +40% YoY on august 5, argues the phantom fraction runs higher than the tape.
§
Before the Blue Owl Q2 10-Q, due around . treat enterprise SSD as structurally strong but credit-sensitive, not bulletproof. the demand is real, but the marginal buyer sits closest to the private-credit stress that blue owl just flagged. blue owl BDC non-accrual plus $14B redemptions (40.7% of Q1 shares) place 8-16 week cascade risk on enterprise SSD; micron and sandisk are the exposed names. falsifier: a second non-accrual at blue owl, apollo, or ares, or a GPU-cloud guide cut at coreweave or crusoe in late july, activates the cascade.