From the editor
tkal is a daily synthesis of the credit, demand, and capex cascades I've been running for myself. Receipts published weekly: every dated call gets graded, blindly, against what actually happened. The premise is that most market writing is unfalsifiable by design — vague enough to be re-narrated after the fact. This is the opposite. The conviction level is on the call. The horizon is on the call. The falsifier — the thing that would prove it wrong — is on the call. If the call misses, it's in the scorecard. If it hits, also in the scorecard. The newsletter is what the model saw this week; the scorecard is whether the model has been right. Not investment advice. Positions may exist in the names discussed.
The Read
a tier-0 micron print reset every memory lane back to up this week, and the credit-stress scare from seven days ago receded from the near-term window, leaving one commodity lane still on the clock.
Micron Re-Anchors, Credit Steps Back
01 · Signal
micron re-anchors the whole book
the tier-0 micron fiscal q3 print did the heavy lifting. hbm3e and hbm4 are sold out through cy2027 with demand stretching into 2028, fy26 capex steps to $27b, and nand bit demand runs near 20% against constrained supply. enterprise ssd contracts jumped 48 to 53% in the quarter. every segment moved the same direction off one tier-0 source.
one print, three segments, one direction. the bull case now has a tier-0 anchor, not an analyst estimate.
02 · Signal
credit steps back from the near-term window
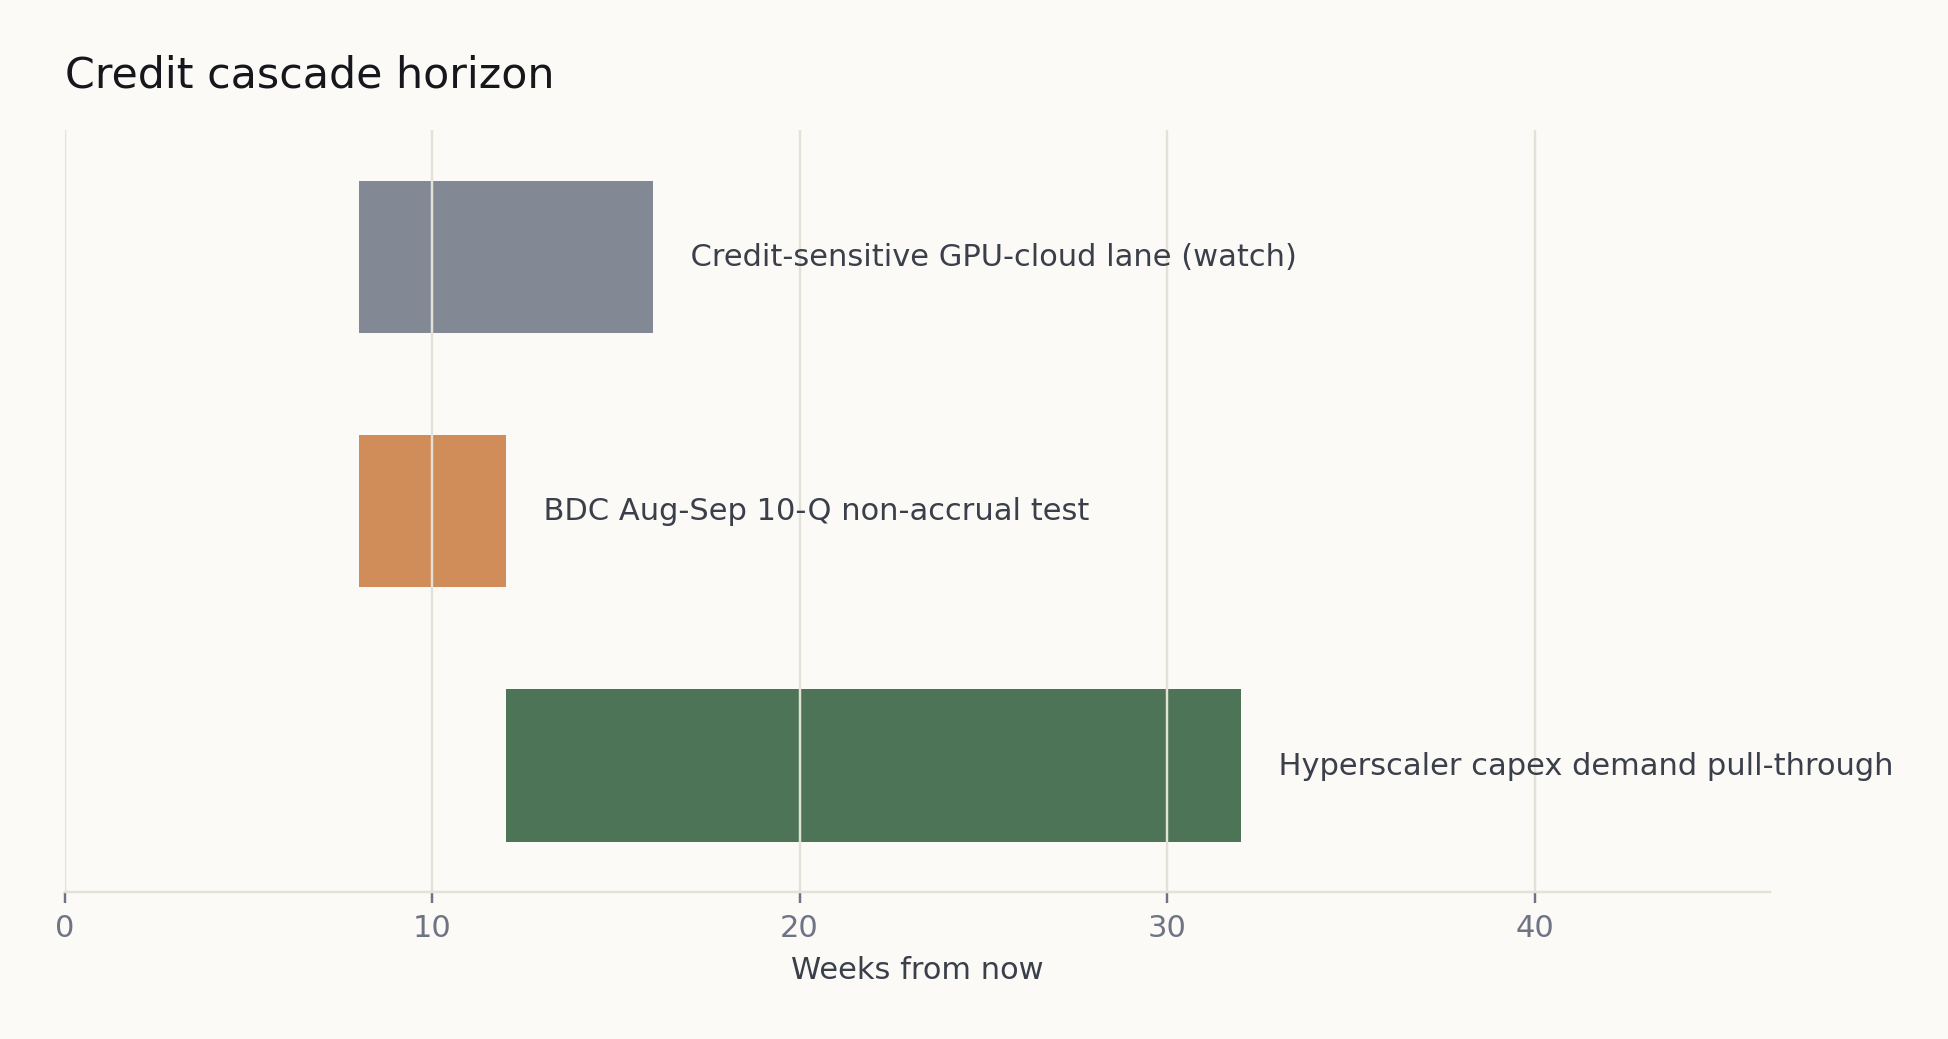
last week the pipeline flashed stressed credit with an active near-term cascade flag. it did not propagate. the signal reverted to stable this week, near-term flag off, with the lead-lag horizon back at a median sixteen weeks. apollo, blackstone, and blue owl keep originating ai-infra credit at scale, so the six-to-twelve-month read stays structurally bullish.
no cascade sits inside the pricing window today. the august-to-september bdc 10-q cycle is the next thing that could pull it back in.
03 · Signal
the split now lives in one lane
the bifurcation narrowed to the commodity ddr5 client lane. retail prices ran roughly 3x while pc units fell 11.3% and smartphones logged their worst print on record, a 35% phantom-demand ratio that reads as speculative inflation, not real pull. server ddr5, enterprise ssd, and hbm carry genuine demand. section 232 phase-2 lands july 1 as the binary swing.
july 1 is the disambiguator. tariff without a carve-out deepens the client rollover; a carve-out unwinds the front-running.
The Call · Section 232 Fires
section 232 phase-2 lands july 1. implementation without a memory carve-out deepens the commodity ddr5 client rollover; a carve-out relieves the front-running and starts unwinding the 35% phantom ratio.
Segment State · Week of
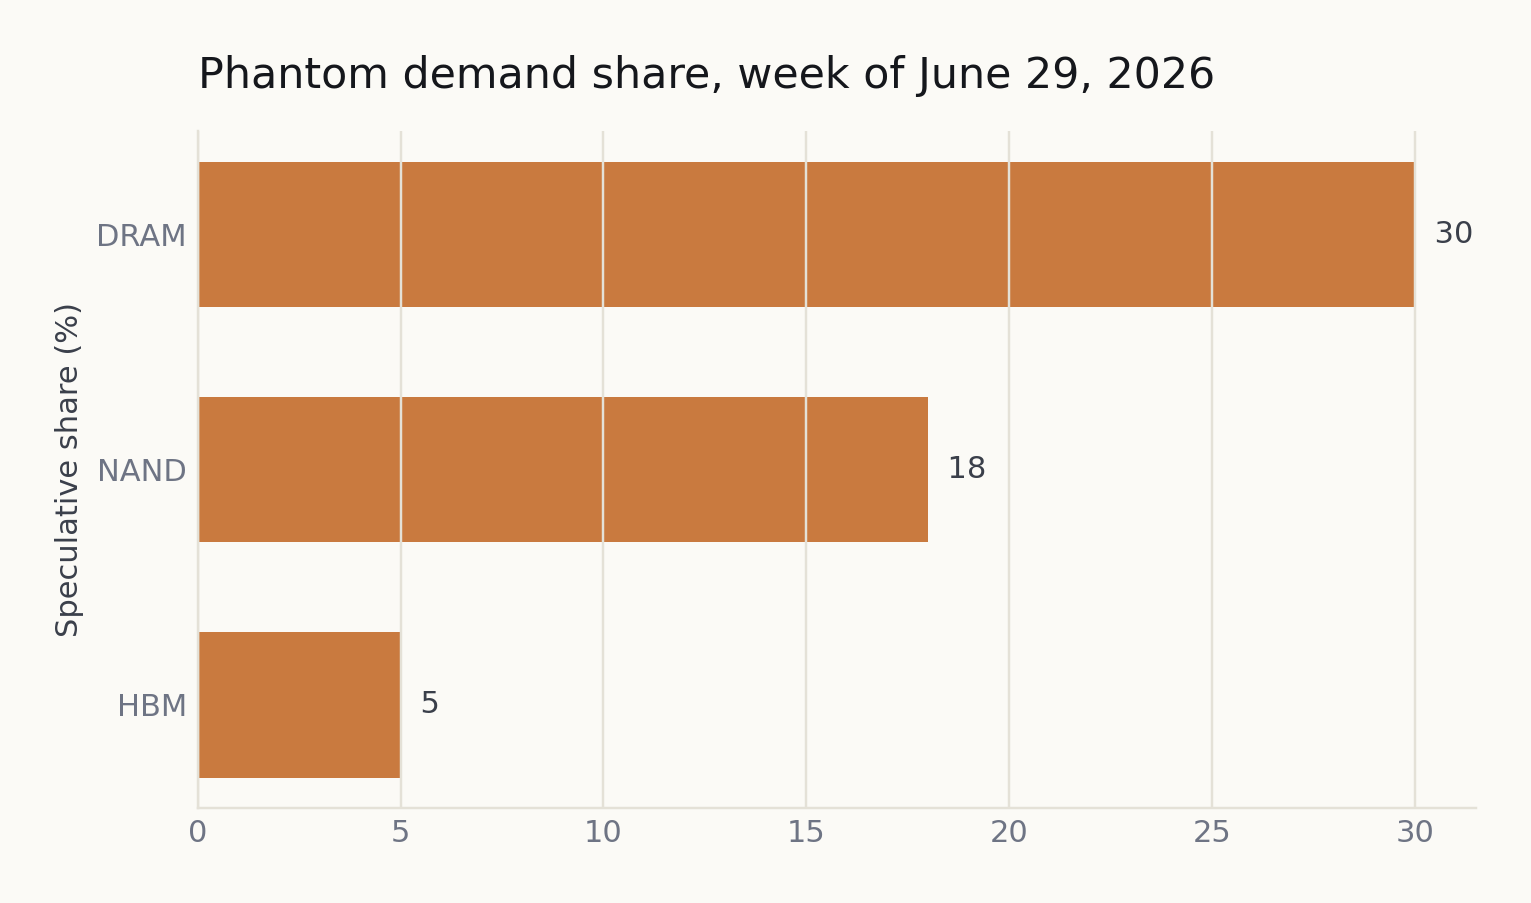
Phantom demand share — at-a-glanceSOURCE · tkal estimate from public shipment, pricing, inventory, earnings & channel data — excludes employer, customer, supplier & other nonpublic information
Segment
State
Tape
Phantom %
DRAM
Tightening
UP · Moderate
30%
NAND
Tight
UP · Strong
18%
HBM
Tight
UP · Strong
5%
What the evidence suggests
§
Before section 232 phase-2 on july 1. the evidence currently favors ai memory — hbm, server ddr5, and enterprise ssd — where demand, capex, and credit all point the same way. micron carries the read with hbm sold out through cy2027 and fy26 capex at $27b; sk hynix and samsung sit alongside, with enterprise ssd contracts up 48 to 53% in the quarter.
§
Through the q2 contract settlement near june 30. don't read blended dram strength as uniform. the server lane holds while commodity client carries the phantom flag, and the settlement is the disambiguator. samsung is reallocating wafers from ddr4 toward hbm and ddr5; sk hynix m15x ddr5 capacity arriving 3q26 is the loosening offset to watch.
§
On the cxmt and ymtc timelines into year-end. treat china substitution as live counter-pressure to the multi-year deficit thesis, not as something already priced in. cxmt holds about 8% dram share with an hbm3 mass-production milestone targeted near year-end; ymtc's wuhan fab 3 ramps in 2h26 toward roughly 15% nand share.