From the editor
tkal is a daily synthesis of the credit, demand, and capex cascades I've been running for myself. Receipts published weekly: every dated call gets graded, blindly, against what actually happened. The premise is that most market writing is unfalsifiable by design — vague enough to be re-narrated after the fact. This is the opposite. The conviction level is on the call. The horizon is on the call. The falsifier — the thing that would prove it wrong — is on the call. If the call misses, it's in the scorecard. If it hits, also in the scorecard. The newsletter is what the model saw this week; the scorecard is whether the model has been right. This is a mid-year edition: a 1H'26 review of the semiconductor and hyperscaler tape — the half's recap and the four themes that ran it — with the week's live, dated call still below. Not investment advice. Positions may exist in the names discussed.
1H'26 in Review
the first half of 2026 settled the debate: ai infrastructure stopped being a capex story and became a supply story. hyperscaler spend stepped to roughly $725b for the big four, high-end memory sold out into 2027, and the binding constraint moved from chips to power — one industry now running two clocks at once.
Supply Becomes the Story, and Power Becomes the Ceiling
four themes ran the half. one — hyperscaler capex inflected to a step-function: the big four guided ~$725b for 2026 (about +77% year over year) and the top-nine csp aggregate sat near $830b, with the bottleneck shifting to power rather than silicon as azure carried a multi-billion backlog it couldn't energize. two — the memory cycle turned structural, not cyclical: high-bandwidth and high-end dram booked through 2027 into 2028, makers guiding tightness past 2027, and micron printing a record june quarter led by data-center demand. three — the bifurcation hardened: the ai lane (hbm, server ddr5, enterprise ssd) stayed anchored while the commodity lane (ddr4, client) ran its own softer clock. four — the compute layer stayed supply-controlled: tsmc grew ~35% with hpc past 60% of mix and nvidia's data-center line still set the pace. the one thing to watch into 2h: whether the commodity lane's rollover is real — which is exactly what this week's print and settlement decide.
01 · Signal
the bifurcation is now textbook
the ai lane is fully anchored. trendforce revised top-9 csp 2026 capex up to $830b, +79% year over year, with buyers locking supply through long-term agreements. korea's may exports hit a record $87.75b on chip strength. the commodity lane went the other way. ddr4 spot fell for a third straight week and counterpoint logged a 6% smartphone drop tied to the memory crunch. one industry, two directions.
the split is no longer a forecast. it sits in the tape, in two opposite columns.
02 · Signal
credit is easing, not cracking
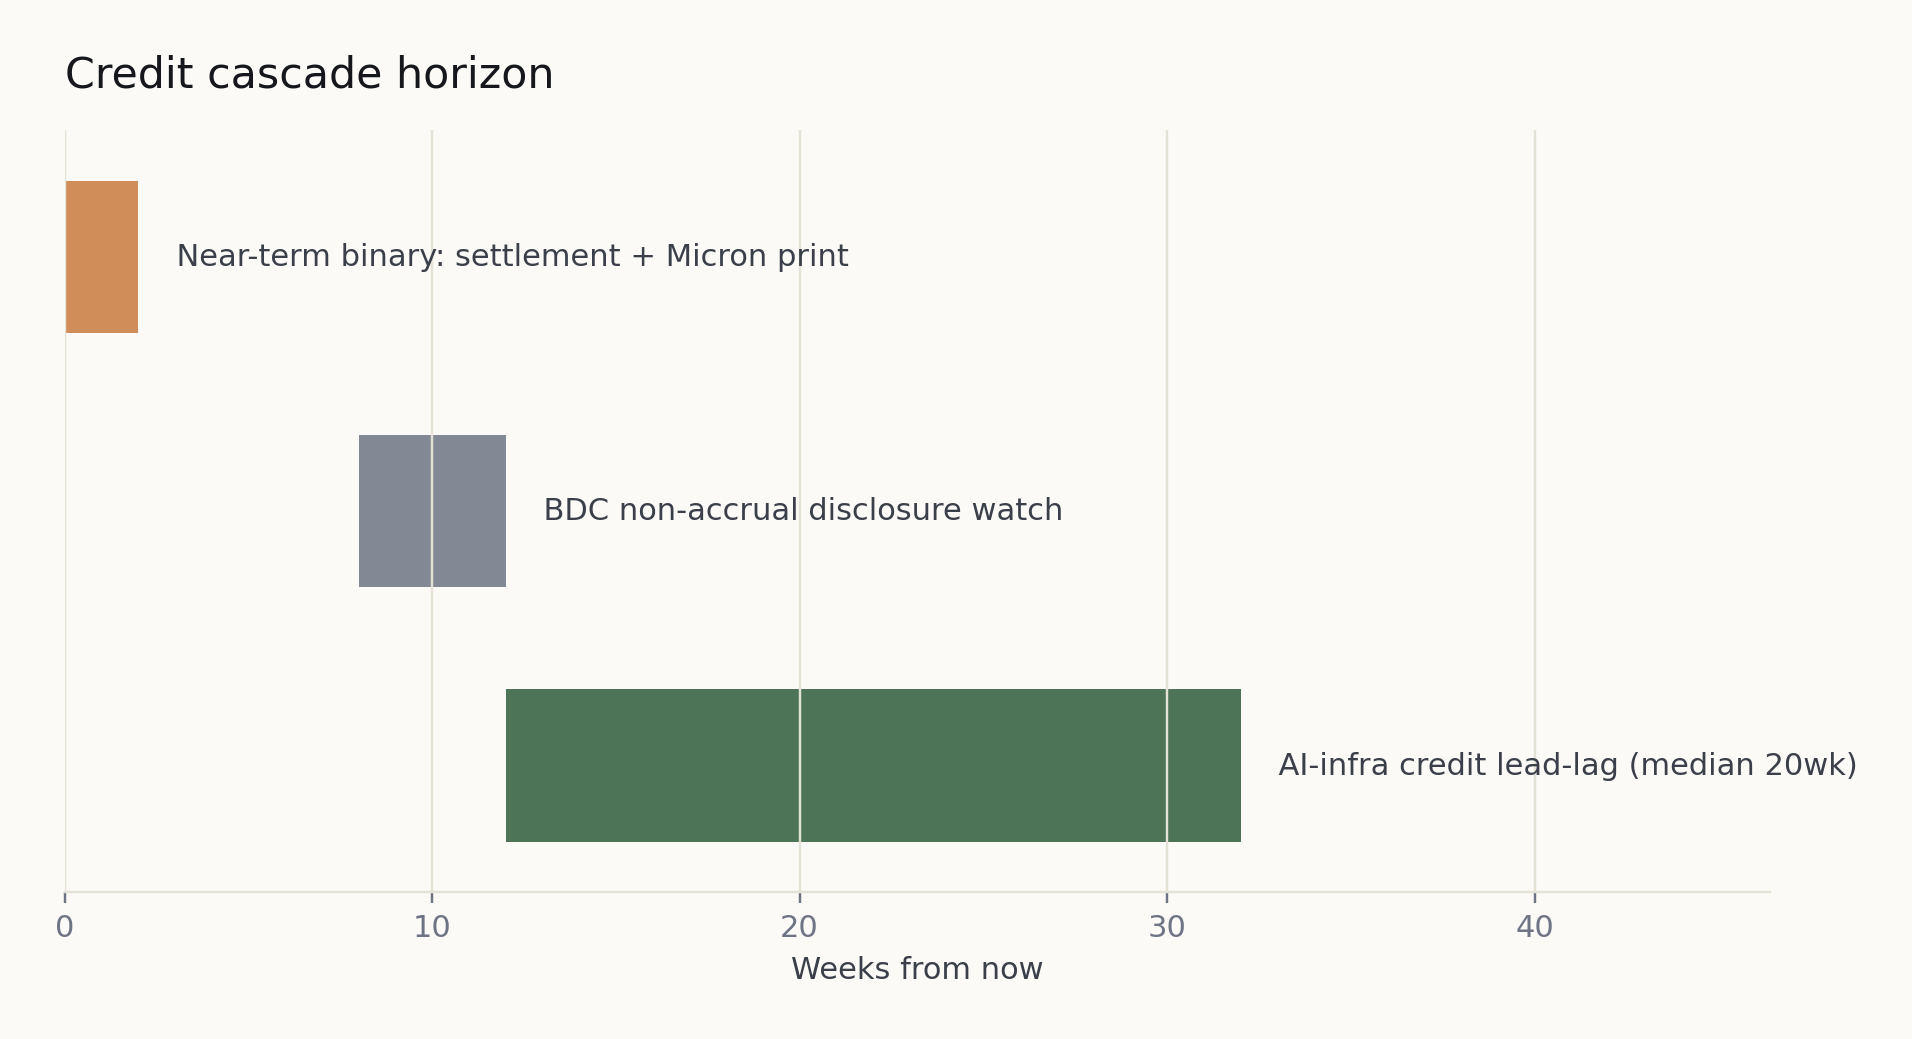
the financing side stayed constructive. apollo expanded origination with a $35b broadcom ai facility plus a $3.5b xai deal; blackstone anchored an $8.5b coreweave facility and a $10b firmus project. the pipeline reads easing with accelerating ai-infra lending and no active stress alert. the lead-lag horizon sits at 12 to 32 weeks, which places confirmed demand impact in late q4 2026 into early 2027.
no cascade is visible today. the first bdc mark below 90 cents would change that, and the next batch lands in august.
03 · Signal
one week resolves four open questions
micron reports fiscal q3 on june 24 and the q2 samsung, sk hynix, and micron contract settlement lands around june 30. both fall inside nine days, and together they decide whether the speculative inflation flagged on commodity ddr5 client, ddr4, and client ssd becomes a visible reversal or holds. the asterisk: underlying evidence is 21 days stale, so every read this week carries a confidence downgrade.
conviction is medium by design. the print and the settlement are what turn it.
The Call · DDR4 Fourth Print Decides
ddr4 spot has fallen three weeks running. a fourth decline on the june 26 trendforce print escalates the segment to dumping and confirms the commodity rollover.
Segment State · Week of
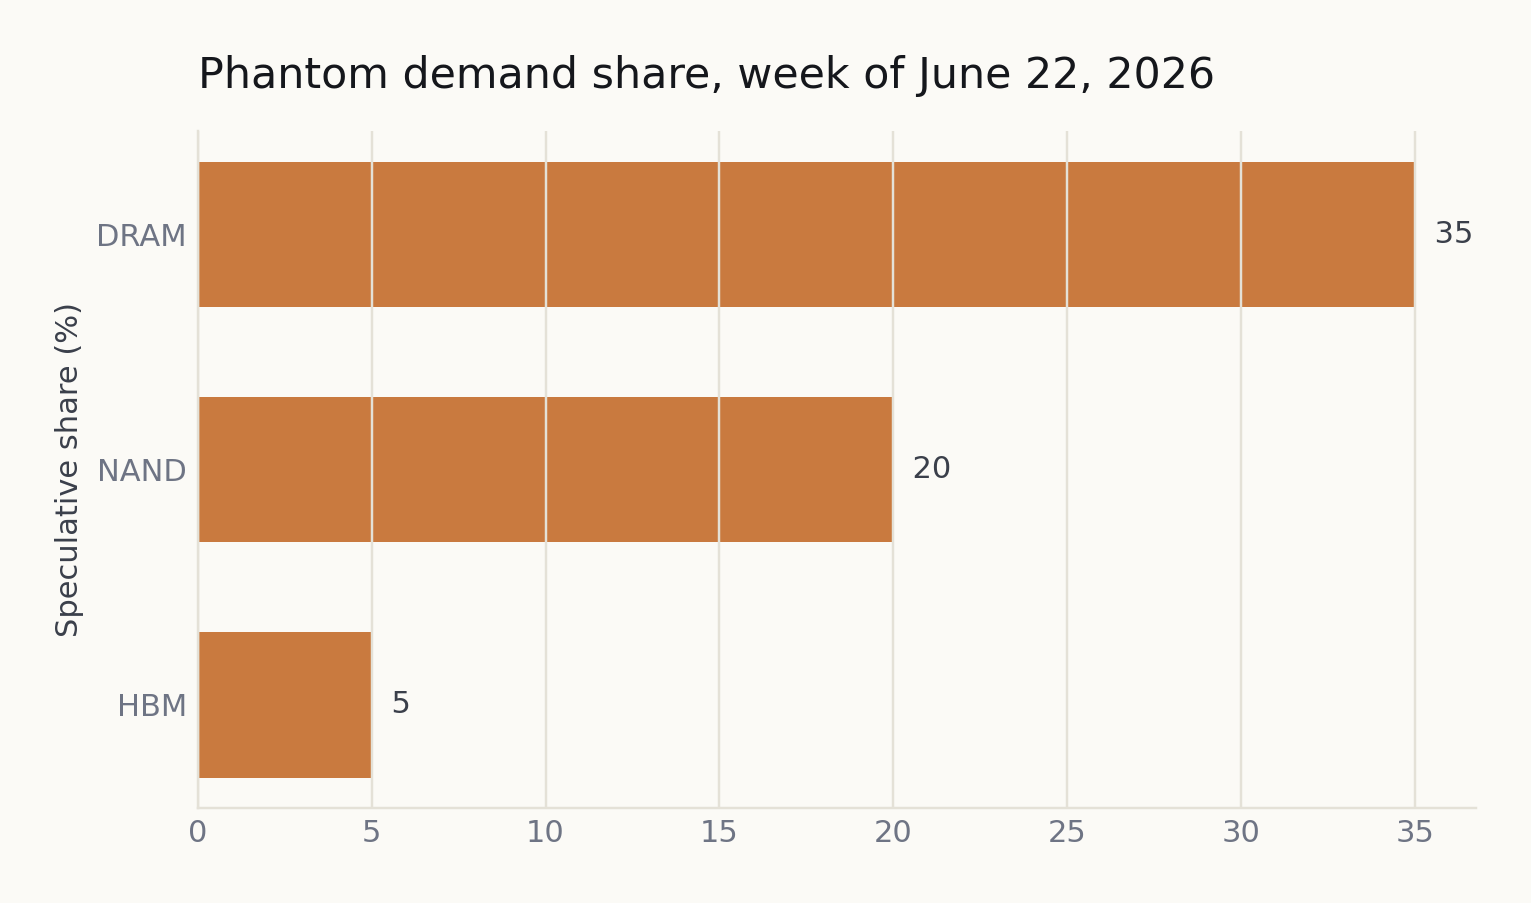
Phantom demand share — at-a-glanceSOURCE · tkal estimate from public shipment, pricing, inventory, earnings & channel data — excludes employer, customer, supplier & other nonpublic information
Segment
State
Tape
Phantom %
DRAM
Tightening
UP · Moderate
35%
NAND
Firm
UP · Slight
20%
HBM
Tight
UP · Strong
5%
What the evidence suggests
§
Before micron's june 24 print. the evidence currently favors ai memory — hbm, server ddr5, and enterprise ssd — where demand, capex, and credit all point the same way. sk hynix, micron, and samsung carry the read; samsung's commercial hbm4 and the sk hynix m15x pilot near june 30 are the loosening offsets to watch.
§
Through the q2 settlement near june 30. don't read blended dram strength as uniform. the server lane holds while commodity ddr4 and client ddr5 carry a phantom-demand flag, with the settlement as the disambiguator. hk broker ddr5 hoarding and pc build-ahead sit against counterpoint's 6% smartphone drop; the settlement print tells you which side was real.
§
On any cxmt ramp disclosure within 90 days. treat china supply as the live counter-pressure to the multi-year deficit thesis, not as something already priced in. cxmt's ipo is china's largest since 2022 and it now holds 8% global dram share entering corsair, hp, dell, and lenovo lines; an accelerated ramp would pressure commodity dram.