From the editor
tkal is a daily synthesis of the credit, demand, and capex cascades I've been running for myself. Receipts published weekly: every dated call gets graded, blindly, against what actually happened. The premise is that most market writing is unfalsifiable by design — vague enough to be re-narrated after the fact. This is the opposite. The conviction level is on the call. The horizon is on the call. The falsifier — the thing that would prove it wrong — is on the call. If the call misses, it's in the scorecard. If it hits, also in the scorecard. The newsletter is what the model saw this week; the scorecard is whether the model has been right. Not investment advice. Positions may exist in the names discussed.
The Read
No vendor moves before Micron prints on . Beneath the freeze, server DDR5 and HBM keep tightening on $830B hyperscaler capex while client memory carries phantom pull-forward.
Server Tightens, Client Softens, Everyone Holds
01 · Signal
hbm has zero phantom in it
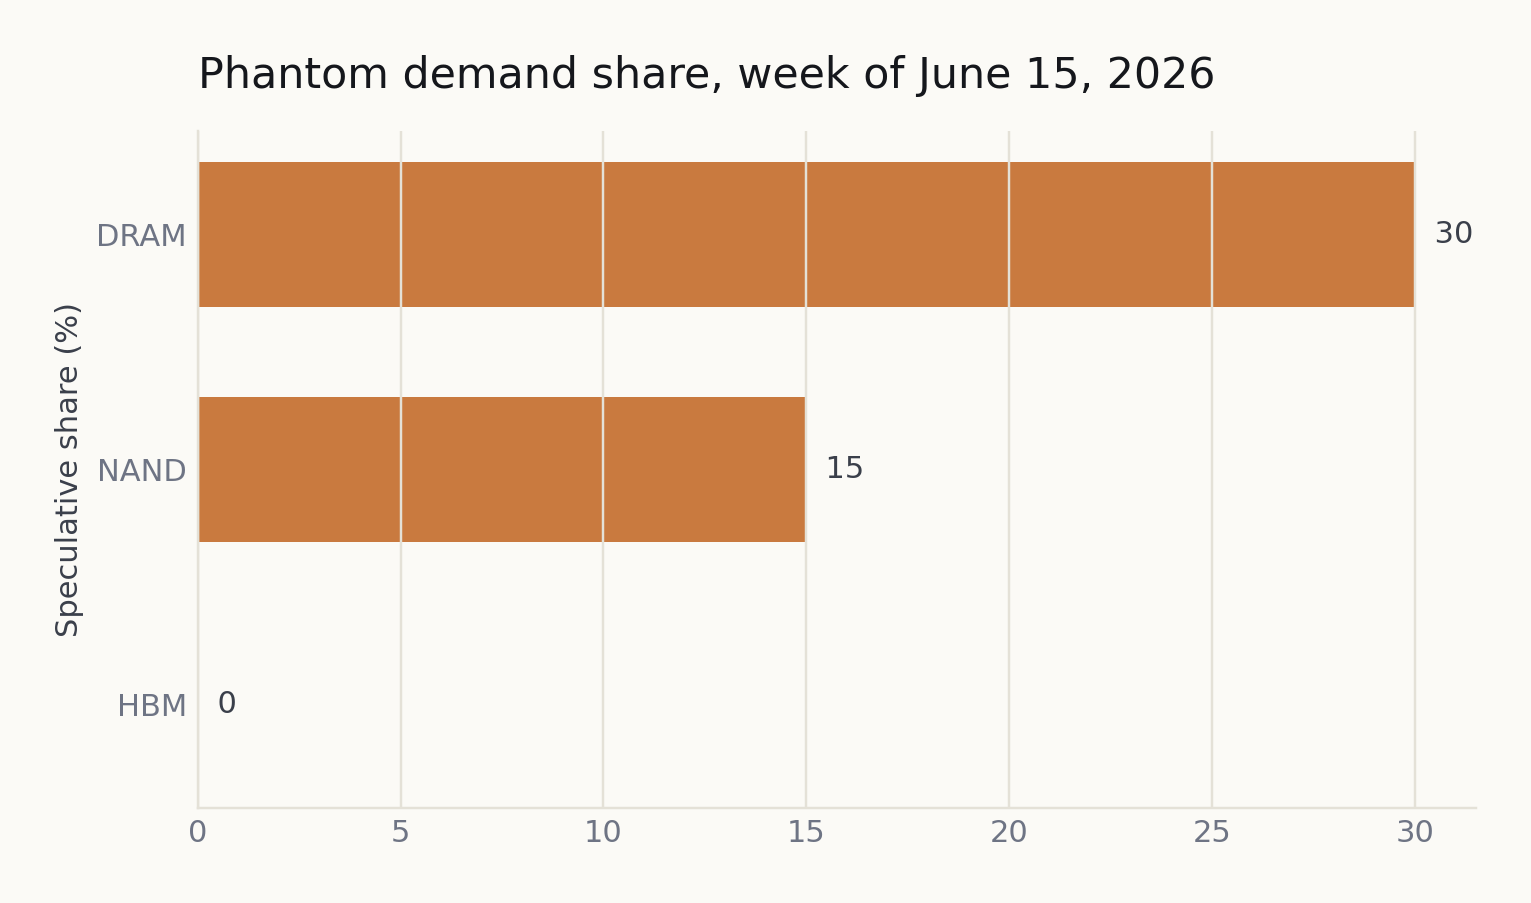
HBM is the only segment in the registry with a clean read. SK hynix holds 62% share and delivered final HBM4 samples to NVIDIA. Micron is sold out through CY2026. Phantom demand sits at 0% and pull-through is confirmed, so there is no speculative inventory waiting to unwind. Every other segment carries some mix of genuine and borrowed demand. HBM does not.
When the cycle turns, HBM is the last thing to crack, not the first.
02 · Signal
credit flipped from stressed to easing
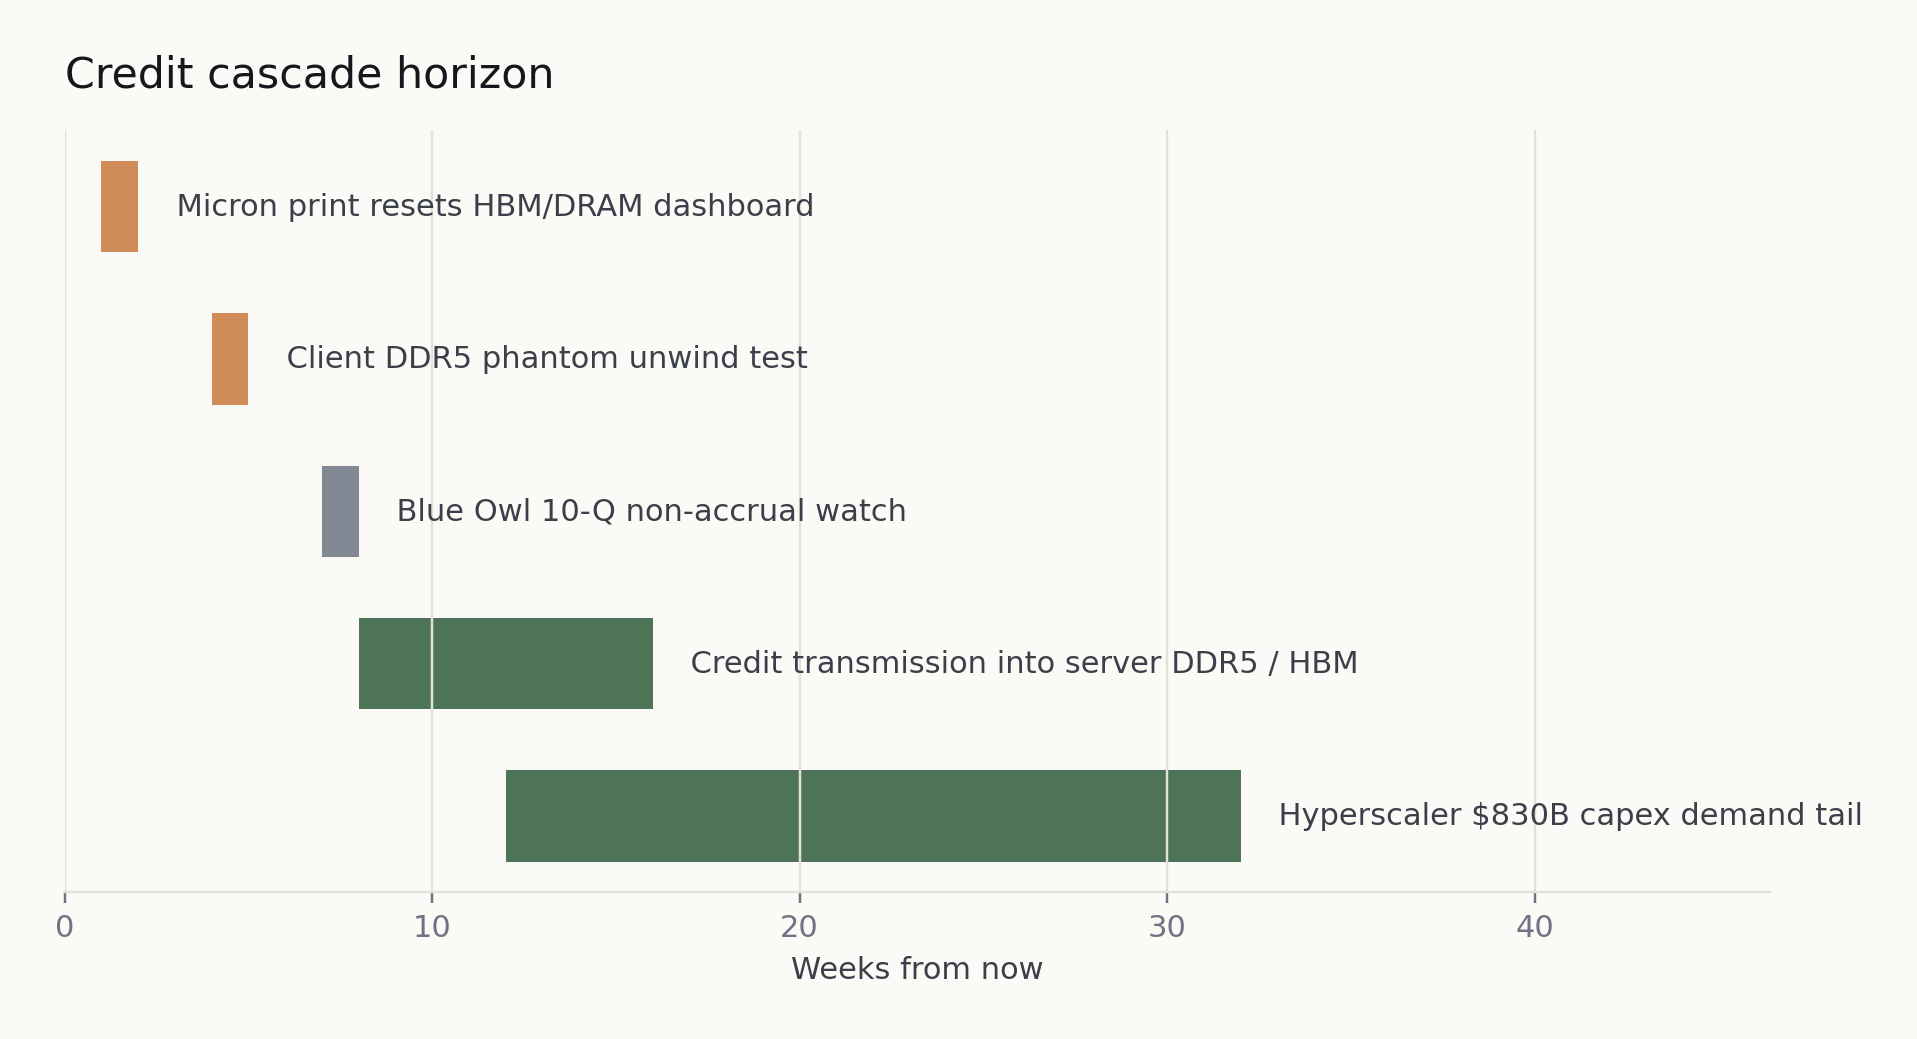
The credit backbone moved from STRESSED to EASING in a single week, with AI financing accelerating. The transmission window is 8 to 16 weeks and it is already visible: TrendForce reports 2Q26 DRAM contracts up 58 to 63% QoQ. Brookfield, Blackstone, PIMCO and Apollo all sit in expanding posture. The demand floor is hyperscaler self-funded capex at $830B, with project finance like Meta Hyperion layered on top, not a credit-sensitive GPU-cloud story.
Credit stopped being a forward indicator this week. It is now a current-quarter catalyst.
03 · Signal
china doubled its memory share in two quarters
The counter-thesis is structural. CXMT now holds 8% of global DRAM, the fourth largest position, and Qualcomm confirmed a qualified state on CXMT parts. YMTC sits at 13% of NAND, level with Micron and SanDisk. Total Chinese memory demand is still rising through CSP capex, but it increasingly routes through CXMT and YMTC rather than the tracked western vendors. Capture is compressing even as the aggregate climbs.
Demand and captured demand are diverging. The gap is the China substitution lane.
The Call · Micron Prints
Micron's fiscal Q3 print on is the universal pivot anchor. Softening HBM 2027 allocation visibility or weaker DRAM contract guidance resets the entire hold-with-upside-bias dashboard.
Segment State · Week of
Phantom demand share — at-a-glanceSOURCE · tkal estimate from public shipment, pricing, inventory, earnings & channel data — excludes employer, customer, supplier & other nonpublic information
Segment
State
Tape
Phantom %
DRAM
Tight
UP · Strong
30%
NAND
Firm
UP · Slight
15%
HBM
Tight
UP · Strong
0%
What the evidence suggests
§
Before Micron's fiscal Q3 print on . The evidence currently favors HBM and server DDR5, where demand is hyperscaler-funded rather than credit-sensitive. The print is the read on whether HBM 2027 allocation visibility holds. SK hynix at 62% share and Micron sold out through CY2026 anchor the setup; Samsung HBM4E stays unconfirmed at NVIDIA, the live second-source catalyst.
§
Before the Q2 PC shipment print around . Don't read blended DRAM strength as uniform. Split server from client. Server DDR5 is genuine; client DDR5 carries phantom pull-forward that Gartner already labels artificially inflated. Tom's Hardware shows 32GB DDR5 kits near $375 and DDR4 at 3 to 5x mid-2025 levels; the July data tests whether Q1 pull-forward unwinds.
§
Watch Blue Owl's Q2 10-Q around . Treat the easing credit signal as intact but one print from reversing. A first non-accrual would flip the read from easing back toward tightening. Meanwhile CXMT at 8% global DRAM and YMTC at 13% NAND keep compressing tracked-vendor capture for SK hynix, Micron and SanDisk even as aggregate demand rises.