From the editor
tkal is a daily synthesis of the credit, demand, and capex cascades I've been running for myself. Receipts published weekly: every dated call gets graded, blindly, against what actually happened. The premise is that most market writing is unfalsifiable by design — vague enough to be re-narrated after the fact. This is the opposite. The conviction level is on the call. The horizon is on the call. The falsifier — the thing that would prove it wrong — is on the call. If the call misses, it's in the scorecard. If it hits, also in the scorecard. The newsletter is what the model saw this week; the scorecard is whether the model has been right. Not investment advice. Positions may exist in the names discussed.
The Read
The memory upcycle is splitting in two: hyperscaler and enterprise demand stays firm against tight supply while the consumer commodity tier quietly unwinds beneath the same DDR5 label.
Bifurcation Sharpens Inside One Upcycle
01 · Signal
the ai lane keeps pulling through
Top-9 cloud capex for 2026 is now tracking 830 billion dollars, up 79 percent year over year, with roughly 450 billion tied explicitly to AI infrastructure. IDC put Q4 server revenue up 61 percent, and the EMS triplet of Quanta, Foxconn and Wistron now runs 79 to 80 percent server mix. HPE booked Q1 DRAM contracts up 90 to 95 percent and added right-to-reprice clauses. Supply stays tight on Kioxia 1Tb TLC, SK hynix HBM4 and server DDR5.
Memory is about 30 percent of datacenter spend. That is the multiplier turning capex into orders, and it is still firing.
02 · Signal
consumer ddr5 borrowed from the future
Underneath the AI lane, the commodity tier is unwinding. Huaqiangbei DDR5 has retraced 15 to 35 percent, US retail sits 20 percent below its March peak, and Counterpoint and Gartner flagged Q1 PC growth of 3.2 percent as strength borrowed from the future ahead of memory-led price hikes. The mobile budget tier is in early demand destruction, with India sub-100-dollar entry phones down 59 percent year over year.
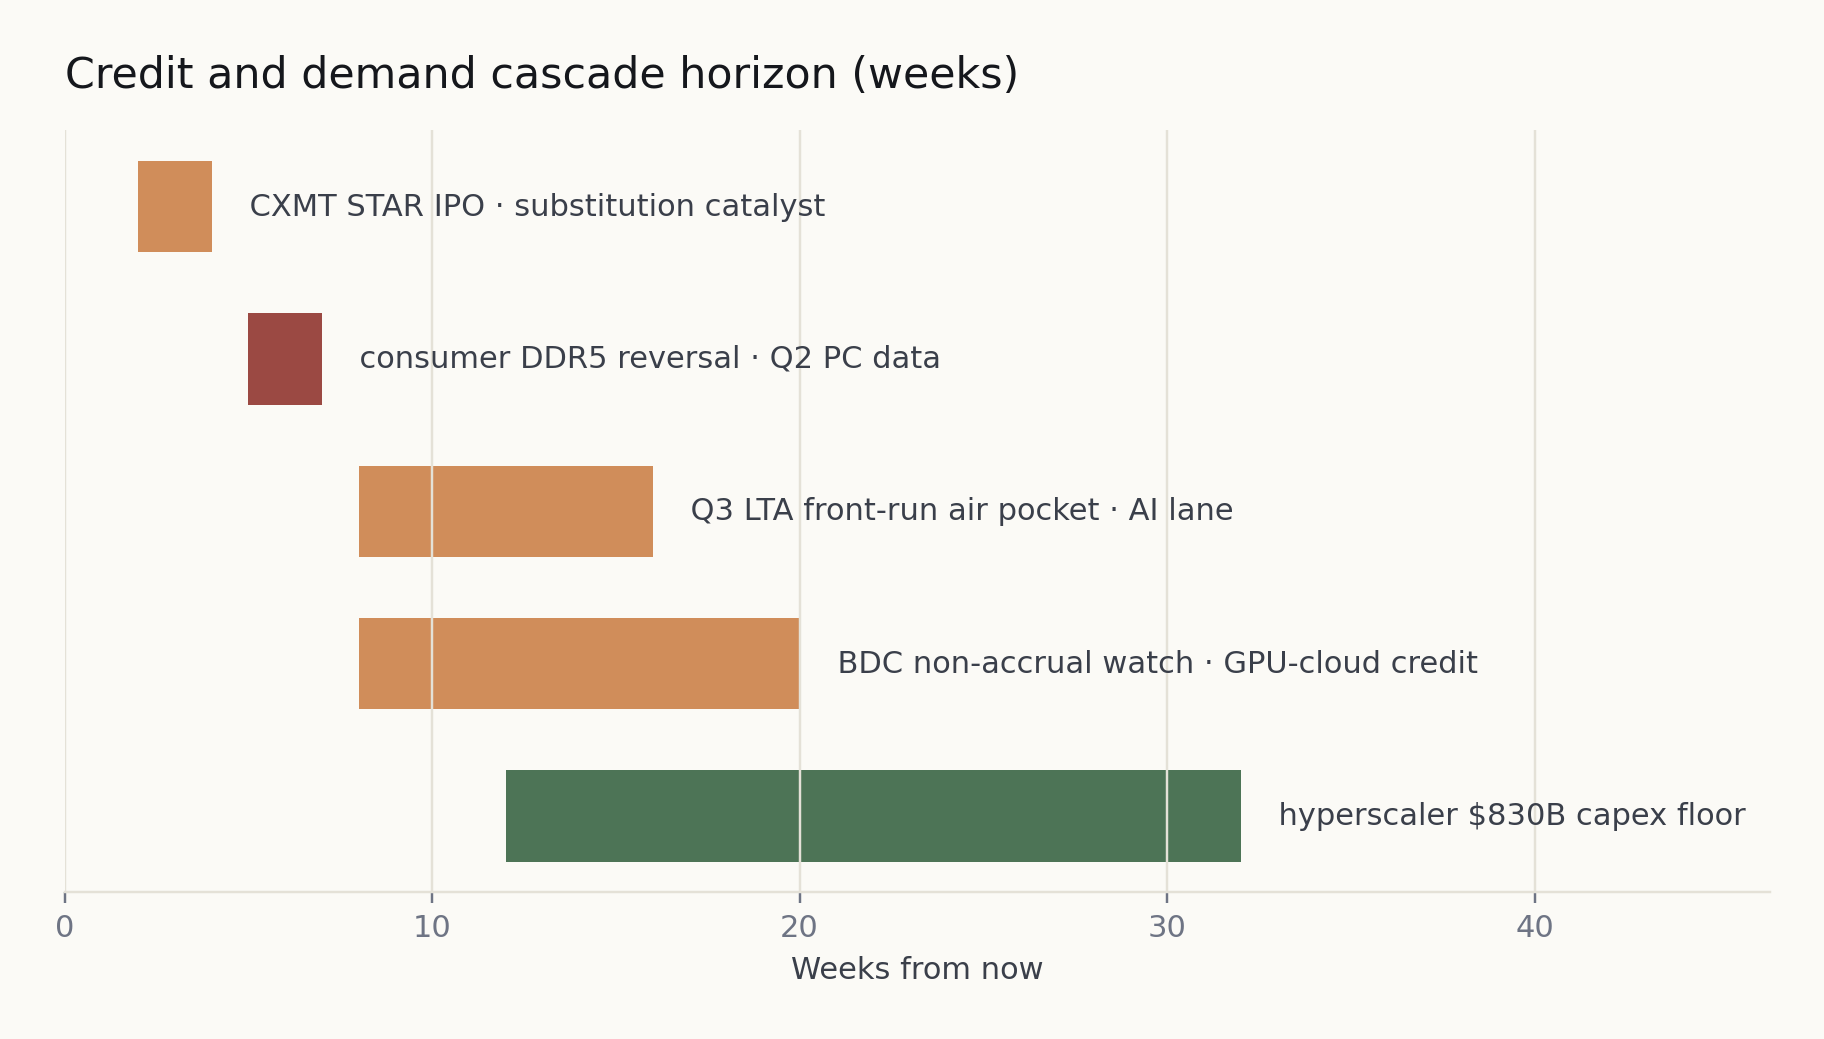
Q2 PC shipment data lands around . If it confirms the pull-forward, the consumer reversal stops being a forecast.
03 · Signal
china dram share is doubling
CXMT cleared its STAR Market IPO review and lifted global DRAM share from 3.97 to 7.67 percent in two quarters, supplying Xiaomi, OPPO, Vivo, Lenovo, Alibaba, ByteDance and Tencent. Samsung is discontinuing LPDDR4 and LPDDR4X by end-2026, and a CXMT and GigaDevice 825-million-dollar joint venture is taking over that legacy production. YMTC Q1 revenue rose 445 percent year over year, lifting NAND share near 13 percent, level with Micron and SanDisk.
Tracked-vendor capture is compressing structurally. The end-June IPO is the next dated catalyst on substitution risk.
The Call · Watch Capex
The whole pull-through read rests on cloud capex holding its 830-billion-dollar pace. The Q2 hyperscaler earnings cluster around is the falsifier: a first crack below that trajectory invalidates the AI lane thesis.
Segment State · Week of
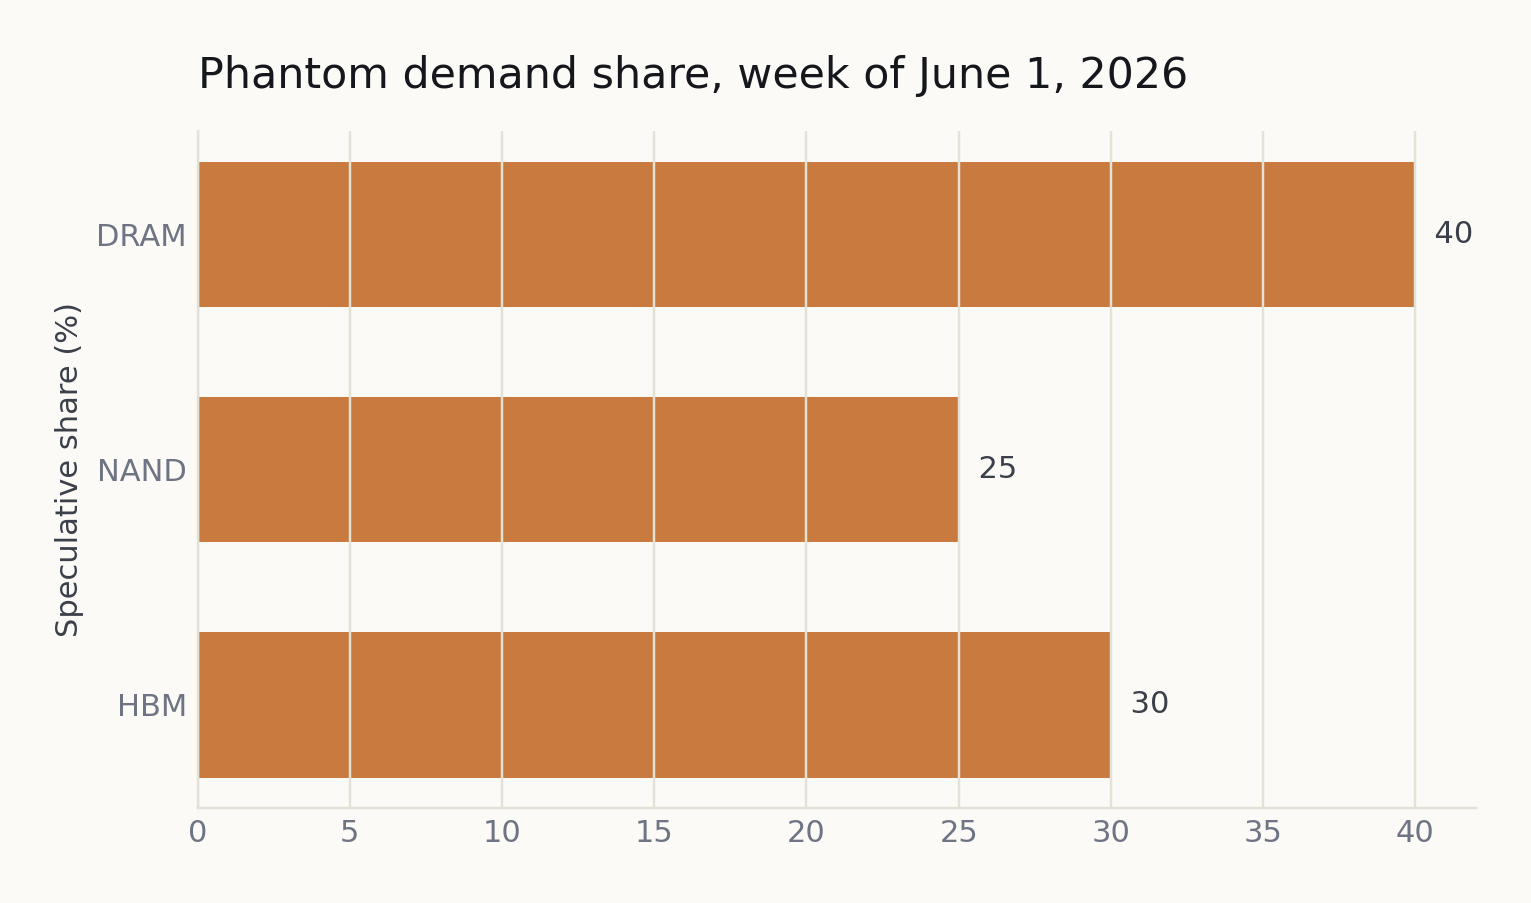
Phantom demand share — at-a-glanceSOURCE · tkal estimate from public shipment, pricing, inventory, earnings & channel data — excludes employer, customer, supplier & other nonpublic information
Segment
State
Tape
Phantom %
DRAM
Tightening
UP · Moderate
40%
NAND
Tightening
UP · Moderate
25%
HBM
Tight
UP · Moderate
30%
What the evidence suggests
§
Into the summer 2026 Kioxia 1Tb TLC sampling window. The evidence currently indicates greater pricing durability in enterprise and datacenter NAND than in the commodity tier. Record industry revenue near 46 billion dollars and a Gen.10 332-layer roadmap on schedule back the structural read. Watch whether Kioxia and Phison hold capex discipline as YMTC, up 445 percent year over year, fragments the top tier toward Micron and SanDisk share.
§
Until the contract-pricing window reopens after 65 silent days. Treat the SK hynix HBM concentration story as unconfirmable right now, not broken. Roughly 70 percent Vera Rubin HBM4 share still points to single-source leadership, but TrendForce contract pricing has stayed dark and Samsung and Micron HBM4 qualification did not refresh. The reopening of either lane is the catalyst that moves conviction off hold.
§
Before the Q2 PC shipment print. Do not read blended DRAM strength as uniform; split server from consumer. Server DDR5 sits on a hyperscaler capex floor; consumer DDR5 carries the reversal risk if Q2 PC data confirms the pull-forward. CXMT and YMTC doubling DRAM and NAND share in two quarters is the structural pressure on tracked-vendor capture at Samsung, SK hynix and Micron.