From the editor
tkal tracks the real economy through capital flows. By the time earnings move, the demand cycle is usually already visible upstream — in credit, construction, equipment orders, power, and supply chains.
Each week, connected pipelines across semiconductors, data centers, power, construction, cyber, and AI deployment surface where demand is building or breaking first. Every call ships with a horizon, a conviction level, and an explicit falsifier — then gets graded against reality.
Not investment advice. Positions may exist in securities discussed.
The Read
Record EPC backlogs, but working capital is the first thing to crack — DSO extends before the backlog does.
All-time backlogs mask the first late-cycle working-capital signal of the build-out
Sector Snapshot · Engineering & Construction
The sector is mid-cycle and demand-led. Tier-1 EPC backlogs are at all-time records across the cohort — MasTec, EMCOR, Quanta, Comfort Systems and Sterling all printed record Q1 backlogs and raised full-year guidance — powered by the AI data-center build-out, grid and transmission spend, and broad electrification. The question has shifted from demand to conversion: working capital (DSO) is beginning to extend at the largest names, the classic late-cycle tell that leads margins by two to three quarters.
01 · Signal
Backlogs are at all-time records across the cohort
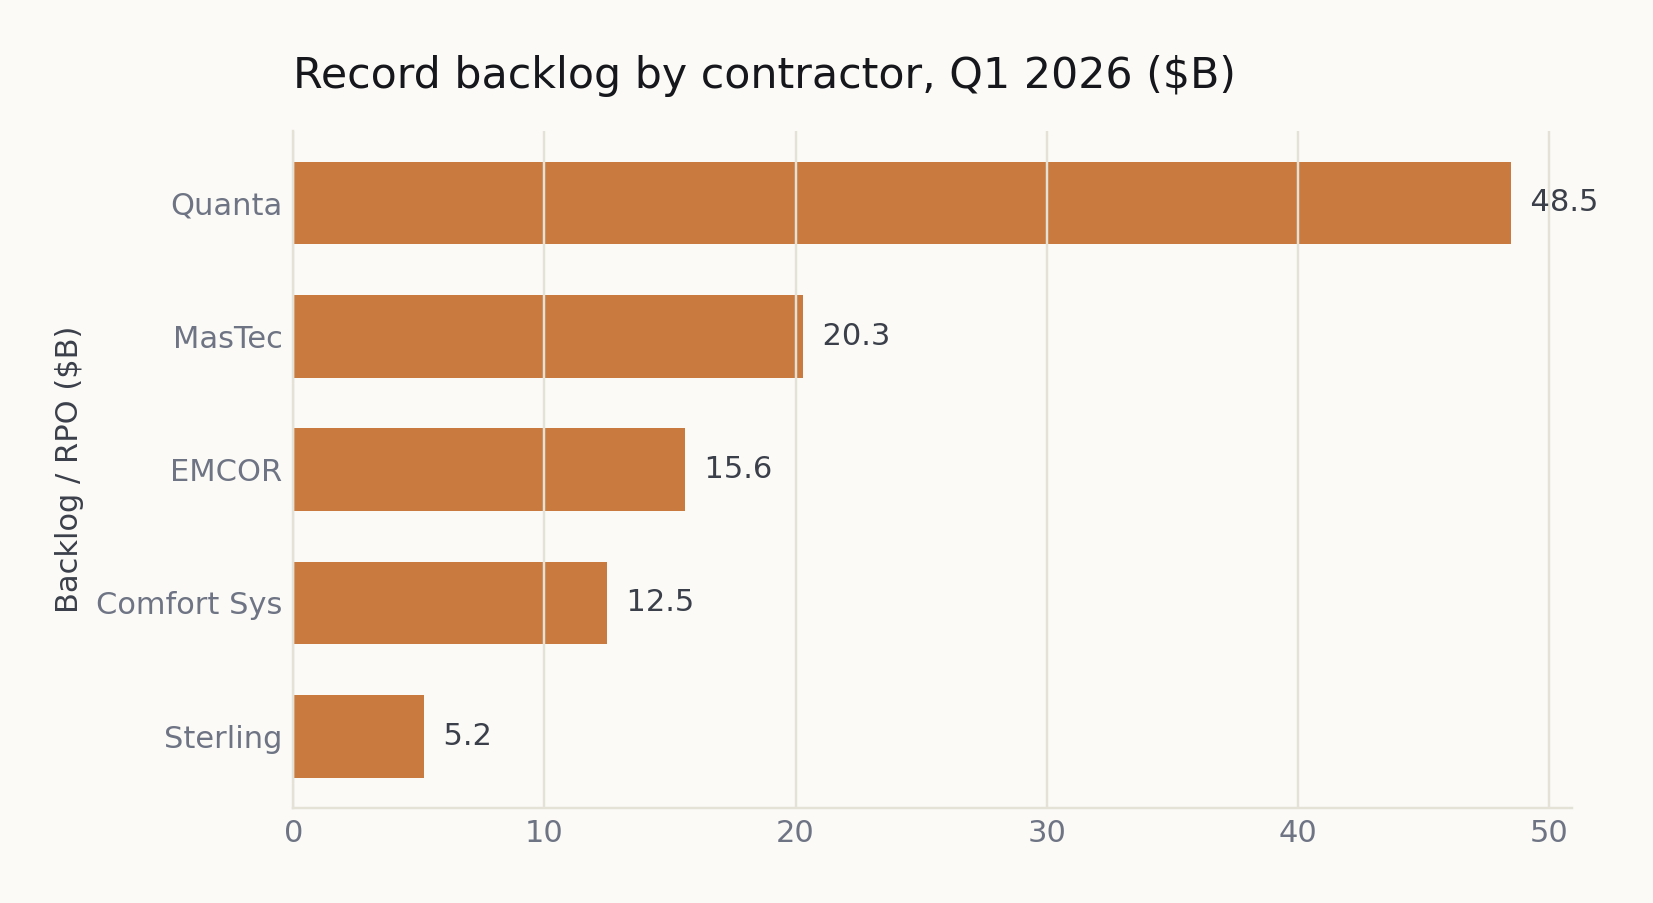
Q1 prints were uniformly strong: MasTec backlog a record $20.3B (+$1.4B QoQ), EMCOR remaining performance obligations a record $15.6B (+33% YoY), Comfort Systems $12.5B (more than double a year ago), Sterling combined backlog $5.2B (+131%), and Quanta a record $48.5B. Demand is not the question this cycle — every name raised full-year guidance.
Record backlog by contractor, Q1 2026SOURCE · company 8-Ks · pipeline L1
Backlog is a necessary-but-not-sufficient signal late in a build-out. When every name is at a record and guidance is rising, the marginal information has already moved off the order book and onto the balance sheet.
02 · Signal
Working capital is where the cycle turns first
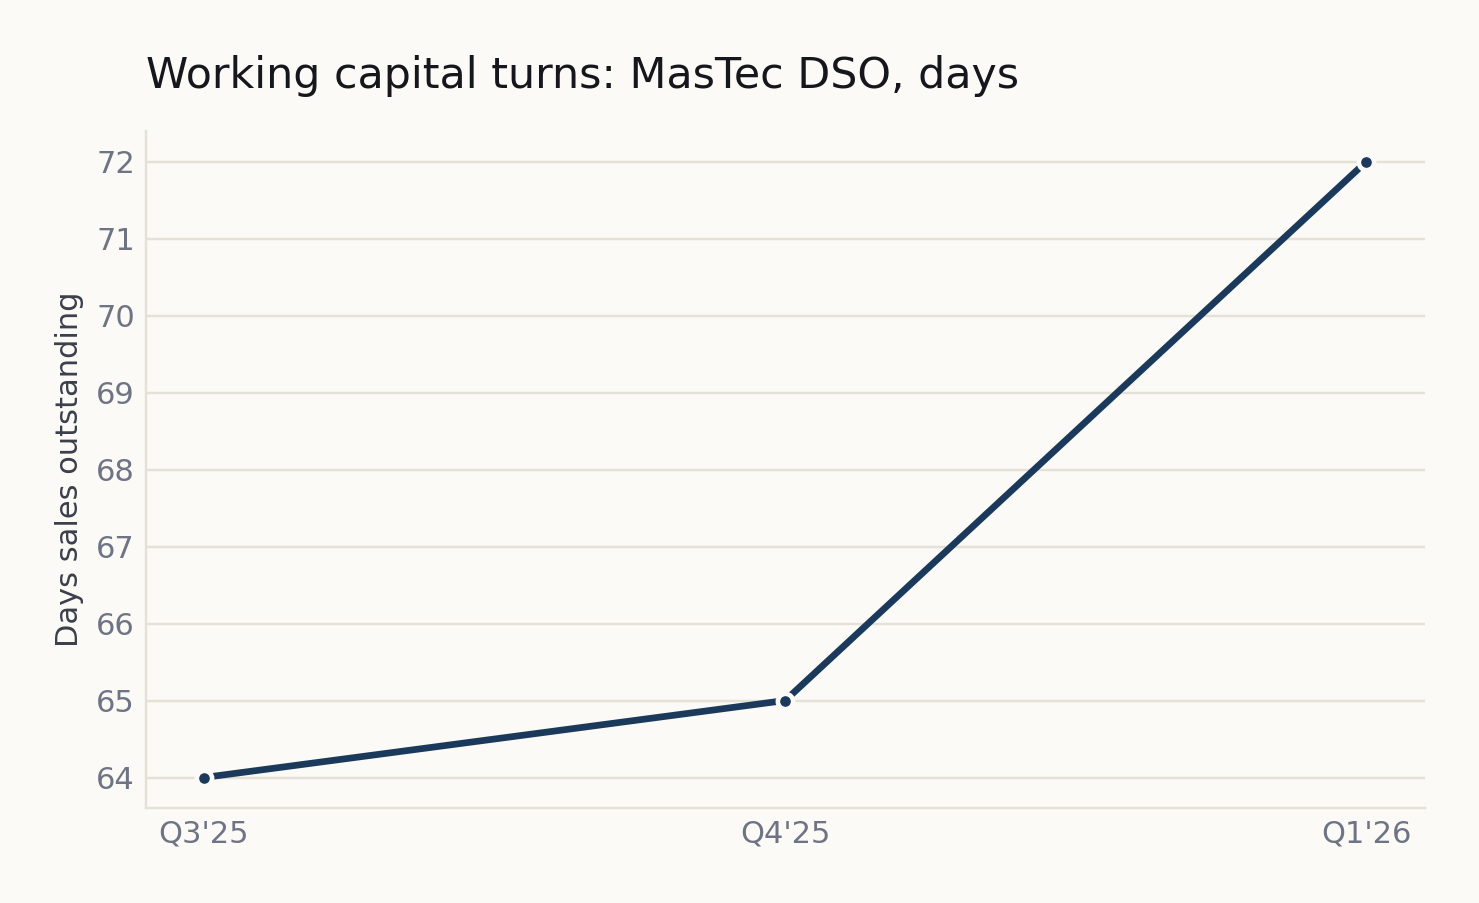
MasTec days-sales-outstanding extended to 72 from 65 at year-end — a seven-day step the company expects to walk back to the mid-60s over the year. The pipeline reads Quanta extending on a similar order this quarter. DSO extension on a record backlog is the classic late-cycle EPC tell: revenue is booked faster than it converts to cash, and the gap shows up two to three quarters before it reaches margins.
Working capital turns before the income statementSOURCE · company 8-Ks · pipeline L8D track
One quarter is noise; the question the Q2 prints answer is whether DSO normalizes — confirming the cycle has room — or extends across the cohort, which would be the first durable late-cycle signal of this build-out.
03 · Signal
The split: data-center mechanical pull is genuine; the stretch is in the largest names
Demand quality is highest in the data-center mechanical/electrical names — Comfort Systems organic revenue +51%, EMCOR and Sterling e-infrastructure both accelerating on AI build-out. The working-capital stretch is concentrated in the largest, most utility- and telco-exposed contractors, where project mix and customer-payment timing are extending the cash cycle. Same end-market, two different balance-sheet stories.
The aggregate read stays constructive on demand and watchful on conversion: a record backlog funded by a structural AI-infrastructure build, with the first working-capital caution flag now on the tape.
The Call · EPC Working Capital
2 of {MasTec, EMCOR, Comfort Systems, Sterling Infrastructure} report DSO extension greater than 5 days QoQ on their Q2 prints. By . Wrong if all four maintain or compress DSO.
Segment State · Week of
Segment
State
Tape
Q1 read
Backlog (cohort)
Record
UP · Strong
+33% YoY
Data-center M/E/P
Tightening
UP · Strong
+51% org
Utility & grid T&D
Firm
UP · Moderate
record
EPC working capital
Extending
WATCH
+7 days
What the evidence suggests
§
Into the Q2 prints (late July–August). Track DSO and cash conversion across the four EPC names, not just backlog and bookings. Record backlog is necessary-not-sufficient; the working-capital turn is the metric that leads the cycle by two to three quarters.
§
On the data-center mechanical/electrical cohort. Demand quality is genuine and accelerating; the open question is margin durability as record backlog converts, not whether the demand is real. Comfort Systems organic +51%, EMCOR and Sterling e-infrastructure both inflecting on AI build-out.
§
On the largest utility- and telco-exposed names. DSO is the single metric to watch into Q2. Normalization back toward the mid-60s confirms the cycle has room; continued extension across the cohort is the first durable late-cycle working-capital tell of this build-out.
 AI Capital Flows