From the editor
tkal tracks the real economy through capital flows. By the time earnings move, the demand cycle is usually already visible upstream — in credit, construction, equipment orders, power, and supply chains.
Each week, connected pipelines across semiconductors, data centers, power, construction, cyber, and AI deployment surface where demand is building or breaking first. Every call ships with a horizon, a conviction level, and an explicit falsifier — then gets graded against reality.
Not investment advice. Positions may exist in securities discussed.
The Read
Durable AI-led strength, but a softening commodity tape and a credit cascade risk that the data can no longer ignore.
Evidence Blackout Stalls Conviction as Commodity Memory Rolls Over
01 · Signal
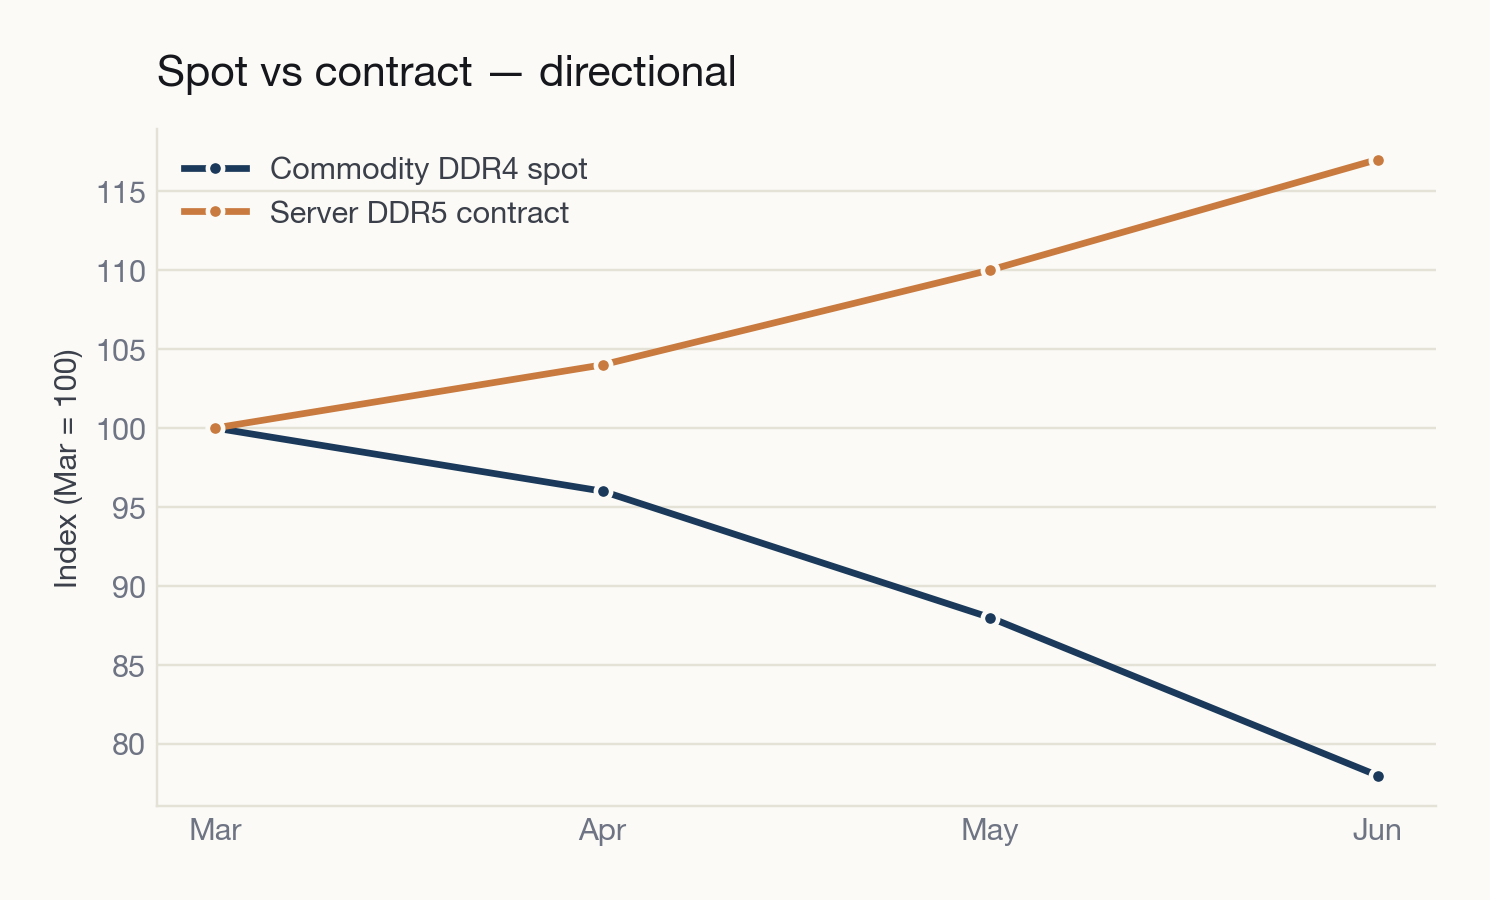
DRAM reads firm, but the tape disagrees
AI/server DDR5 genuinely accelerating, but commodity DDR4/DDR5 'UP' is misleading (speculative inflation) and de-stocking. Evidence-gated week: all supply beliefs degraded to LOW/2, zero L4 decisions; conviction collapsed.
Spot vs contract — directional, indexed Mar = 100SOURCE · pipeline L8D track
Commodity DDR4/DDR5 channel strength is misleading — roughly 20-40% is speculative front-running, and spot is now softening as buyers de-stock.
02 · Signal
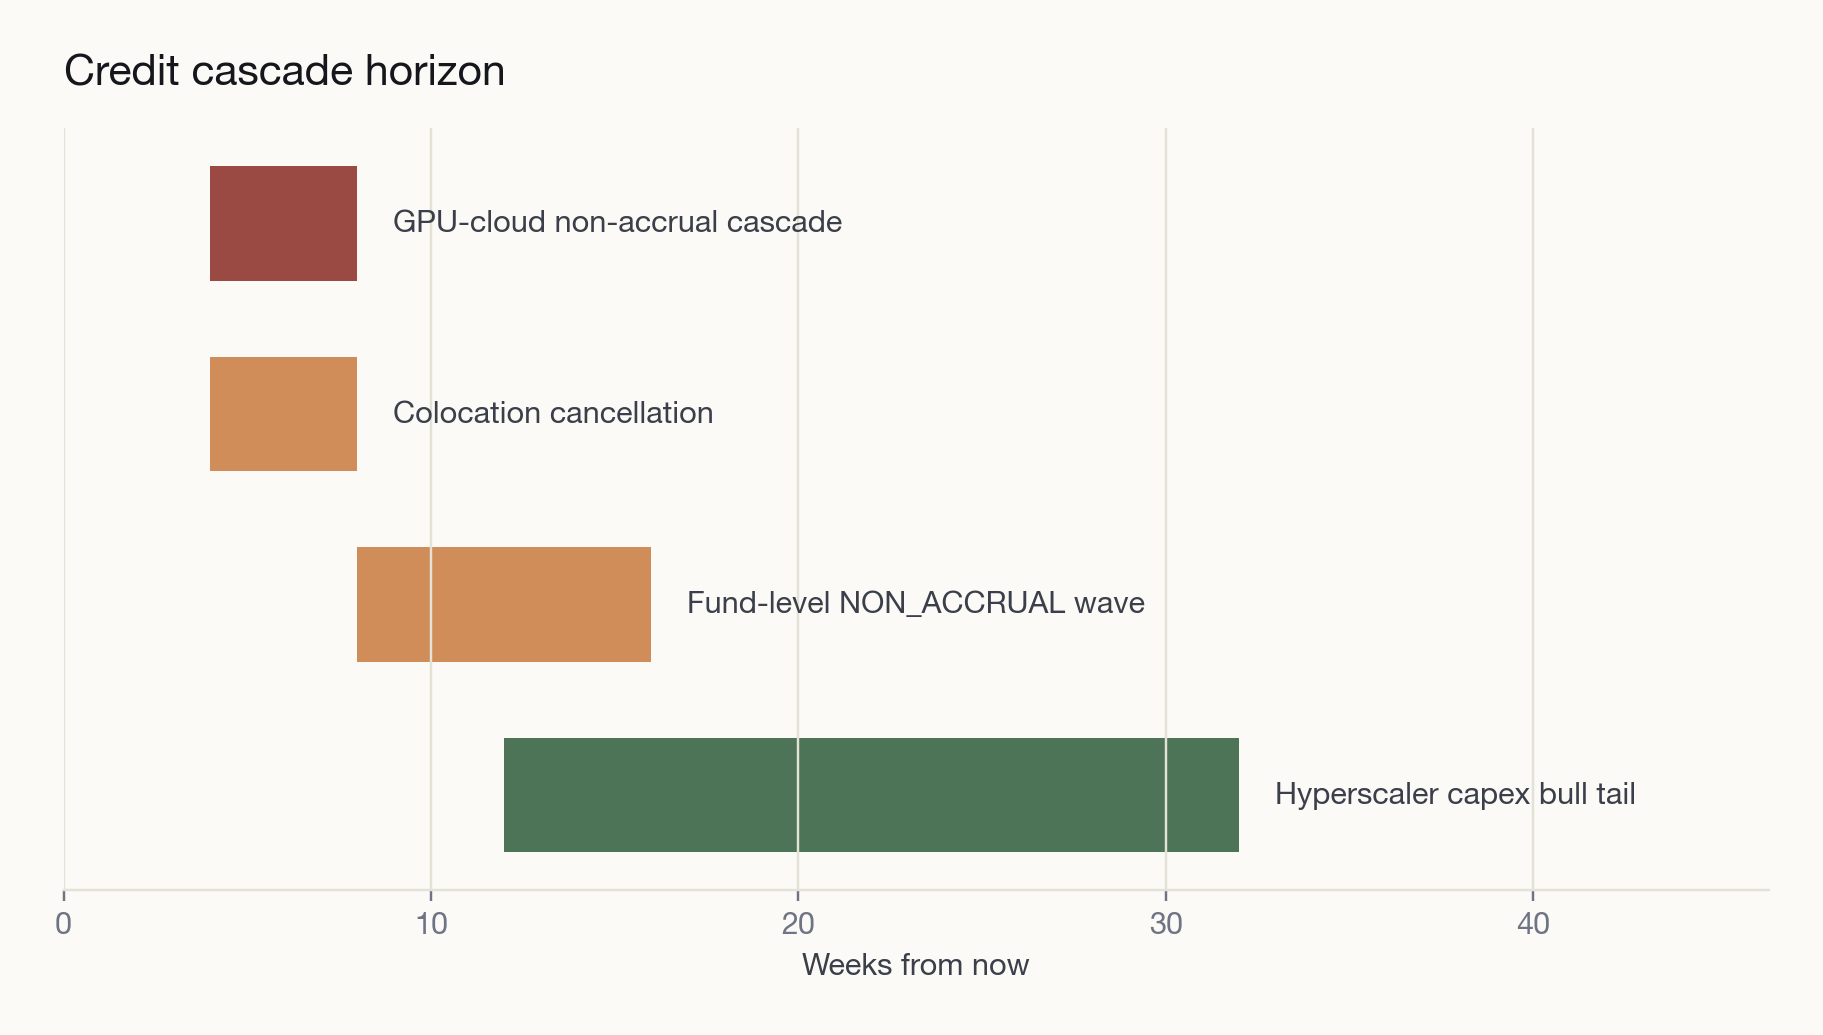
Credit stress goes near-term — high alert active
Active HIGH credit stress: a GPU-cloud (CoreWeave/xAI) non-accrual could compress enterprise SSD and server DDR5 demand within ~8 weeks if it spreads. An Oracle/Stargate colocation project cancellation (4-8 wk) plus a fund-level NON_ACCRUAL (Q1 >$20B redemption wave, 8-16 wk) sit inside the 12-32 week bullish origination horizon, pulling a downside transmission into the current quarter.
Over the 6-12 month horizon, AI-infrastructure financing remains overwhelmingly structural — roughly 81% hyperscaler/colocation origination plus ~$720B+ self-funded capex — which is a durable bullish tailwind for HBM, server DDR5 and enterprise SSD demand.
03 · Signal
Conviction is gated by an evidence drought
Zero Tier-0/Tier-1 evidence this window — all supply beliefs degraded to LOW/2 and L4 emitted zero decisions (evidence-gated pause). TrendForce/DRAMeXchange contract pricing silent ~54 days — no primary pricing/MOS calibration; conviction capped.
Posture stays defensive until a Tier-0 print or a calendar binary clears.
The Call · Credit Stress HIGH
Active HIGH credit stress: a GPU-cloud (CoreWeave/xAI) non-accrual could compress enterprise SSD and server DDR5 demand within ~8 weeks if it spreads.
Segment State · Week of
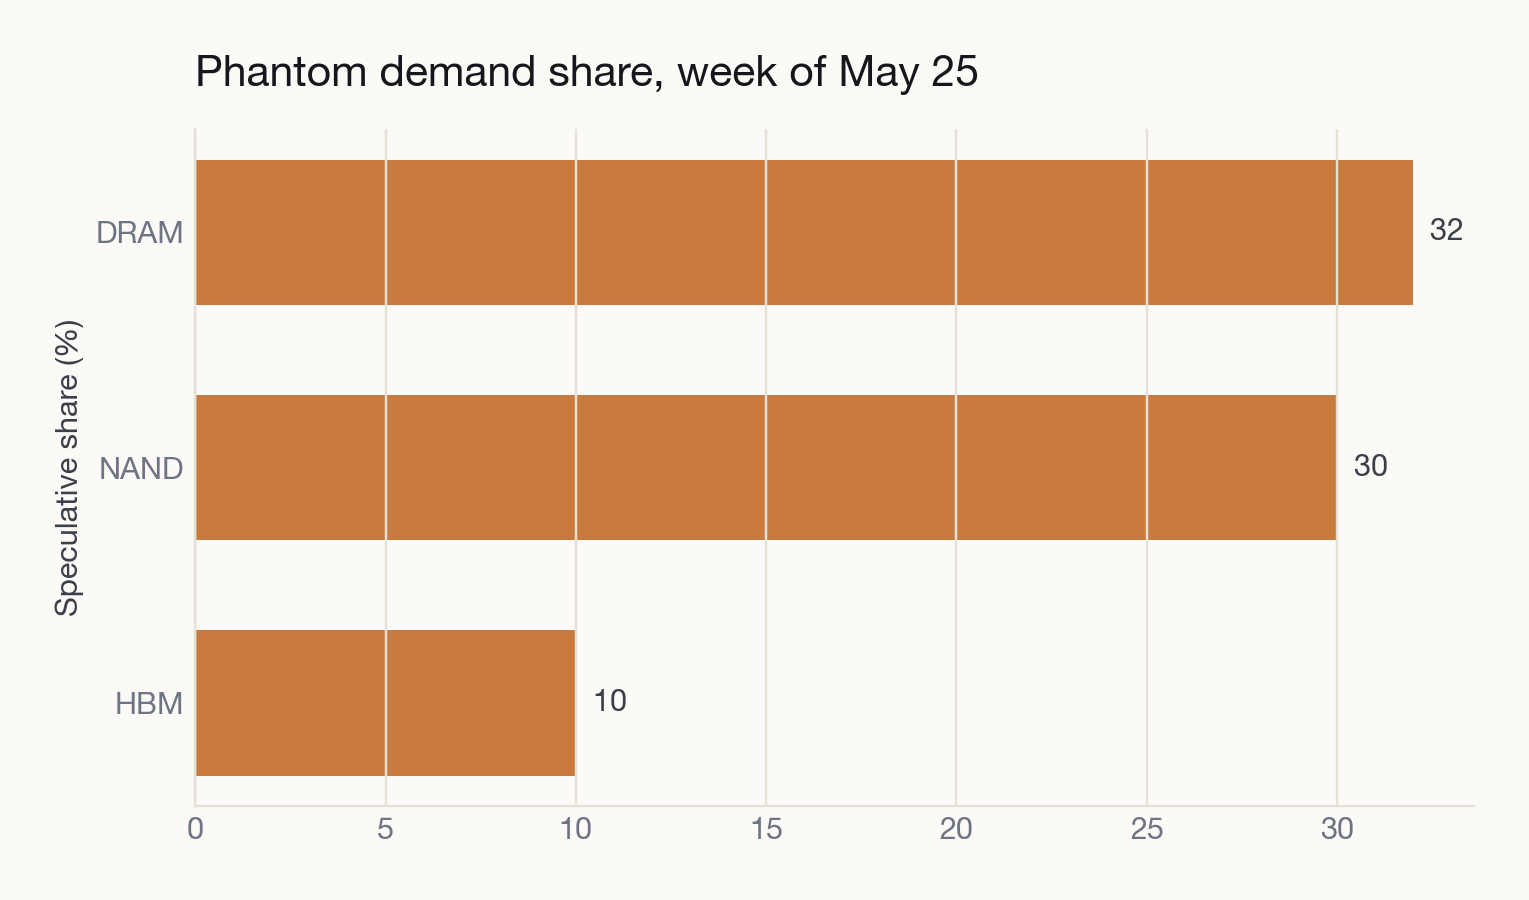
Phantom demand share — at-a-glanceSOURCE · tkal estimate from public shipment, pricing, inventory, earnings & channel data — excludes employer, customer, supplier & other nonpublic information
Segment
State
Tape
Phantom %
DRAM
Firm
UP · Slight
32%
NAND
Balanced
FLAT · Slight
30%
HBM
Tightening
UP · Moderate
10%
What the evidence suggests
§
Before the Samsung ratification vote. Hold all commodity DDR5/DDR4 and client SSD forward-lock offers; quote to a real-demand-adjusted reference, do not chase distributor spot. Commodity DRAM/NAND is speculative-inflation with ~30-35% non-genuine demand now de-stocking (NAND spot down 30-40%, DDR4 spot turning down); channel MISLEADING_UP vs end-customer DECELERATING.
§
This week, ahead of the June Q2 contract settlement. Lock forward server DDR5 (64GB/32GB) and HBM POs with verified BOM-pull integrators only — do not extend to spot buyers. Genuine AI/hyperscaler pull (~US$725B Big-4 capex) and credit-financed colocation tailwind; capture POs before AI tightens, but conviction is LOW this evidence-gated week.
§
Within ~8 weeks (~2026-07-20). Flag enterprise SSD (TLC) allocations for credit-stress review before extending any new forward commitments. Active HIGH credit stress alert names enterprise SSD as first-affected with a ~8-week cascade horizon.
 AI Capital Flows